For company directors, late tax filing can become more than an administrative problem. An overdue company return may attract penalties, while delayed reporting of PAYG withholding, GST or superannuation guarantee charge (SGC) can create a different and potentially personal exposure. We begin by separating those obligations, because the correct response depends on what is overdue, whether the liability has been reported and whether the ATO has issued a notice.
Our priority is to protect financial health while restoring compliance. That means identifying time-sensitive risks, preparing reliable lodgements and assessing whether the business can fund its obligations without compromising solvency.
Separate lodgement deadlines from payment deadlines
We distinguish between two failures: not reporting an obligation on time and not paying it on time. They can occur together, but they have different consequences. A business that cannot pay should not assume it should also delay lodging.
We also confirm the actual due date for each entity and reporting period. Company tax return deadlines vary, and registered tax agent arrangements do not automatically resolve an existing overdue obligation. For late tax filing, the first useful document is an obligation register, not a generic calendar reminder.
| Overdue obligation | Main exposure we assess | Immediate priority |
|---|---|---|
| Company income tax return | Failure-to-lodge penalties, possible default assessment and unresolved tax liabilities | Confirm the deadline and prepare an accurate return |
| BAS reporting GST or PAYG withholding | Lodgement penalties, unpaid liabilities and potential director penalties | Check reporting dates and director penalty exposure |
| SGC statement | Superannuation shortfalls and potential director penalties, including lockdown exposure | Establish the shortfall and applicable statement deadline |
| FBT return | Lodgement penalties and interest on unpaid FBT | Reconcile benefits provided and the outstanding obligation |
| Director’s personal return | Personal penalties and tax debt, separate from company obligations | Review the individual’s lodgement position separately |
An ordinary company income tax debt does not become a director penalty merely because the return is overdue. We keep that distinction clear while assessing other possible director liabilities and governance concerns.
How late tax filing can expose directors personally
The director penalty regime applies to certain unpaid company liabilities, including PAYG withholding, net GST and SGC. Personal liability can arise under the legislation before a director receives a director penalty notice (DPN). The notice is part of the ATO’s recovery process, not necessarily the event that first creates the exposure.
We use the ATO’s director penalty guidance to assess each liability against its reporting history and the relevant statutory rules.
Reporting delays can restrict remission options
For PAYG withholding and net GST, reporting the liability more than three months after its due date can result in a lockdown director penalty. For SGC, the reporting threshold is stricter: failure to lodge the SGC statement by its due date can create lockdown exposure.
This makes late tax filing particularly serious when the missing document is a BAS or SGC statement rather than an annual income tax return. Lodging later does not necessarily restore options that have already been lost.
For eligible non-lockdown penalties, remission may be available through payment or specified formal steps, such as appointing an administrator or small business restructuring practitioner, or beginning winding up, within the applicable timeframe. Those appointments do not generally remit a lockdown penalty.
We therefore assess reporting dates before recommending a recovery strategy. Where personal exposure is possible, we coordinate tax remediation with independent legal or insolvency advice rather than treating the issue as routine catch-up bookkeeping.
Treat a director penalty notice as urgent
A DPN generally provides a 21-day statutory window before the ATO can commence recovery proceedings. That period runs from when the notice is posted or otherwise given under the legislation, not when the director opens the envelope.
We recommend same-day professional review of any DPN. Changing accountants, resigning as a director or negotiating a payment plan does not automatically remove an existing director penalty.
Our review identifies the liabilities covered, whether they are locked down and which statutory options or defences warrant specialist assessment. We also check that company and director address records are current, because missed correspondence can consume an already short response window.
Measure the full financial cost of delay
We assess late tax filing through three separate cost categories: lodgement penalties, interest on unpaid liabilities and the operational cost of unreliable financial information. These should not be combined into one unexplained estimate.
Under the standard failure-to-lodge framework, penalties are generally calculated for each 28-day period, or part of a period, that a document remains overdue, up to five periods. Entity size and status can increase the amount. We check the ATO’s failure-to-lodge penalty rules rather than assuming every business faces the same charge.
General interest charge (GIC) can accrue on overdue tax. Its rate changes quarterly, and a payment arrangement does not automatically stop interest. GIC and shortfall interest charge incurred on or after 1 July 2025 are not deductible, increasing their effective cost to the business.
We assess whether penalty or interest remission is supportable using the circumstances and evidence. A request is not a guarantee, and we do not delay remediation while waiting for a favourable decision.
The commercial cost also matters. Unresolved tax liabilities can distort cash-flow forecasts and complicate lending, transactions or distributions. Reliable compliance records give directors a firmer basis for strategic advisory decisions, including whether expansion remains affordable.
Our first 72 hours: risk triage before catch-up work
We use the first 72 hours as a practical triage framework, not a promise that every backlog can be cleared within three days. A director penalty notice or active recovery action may require immediate intervention before ordinary reconstruction work begins.
Establish the complete exposure
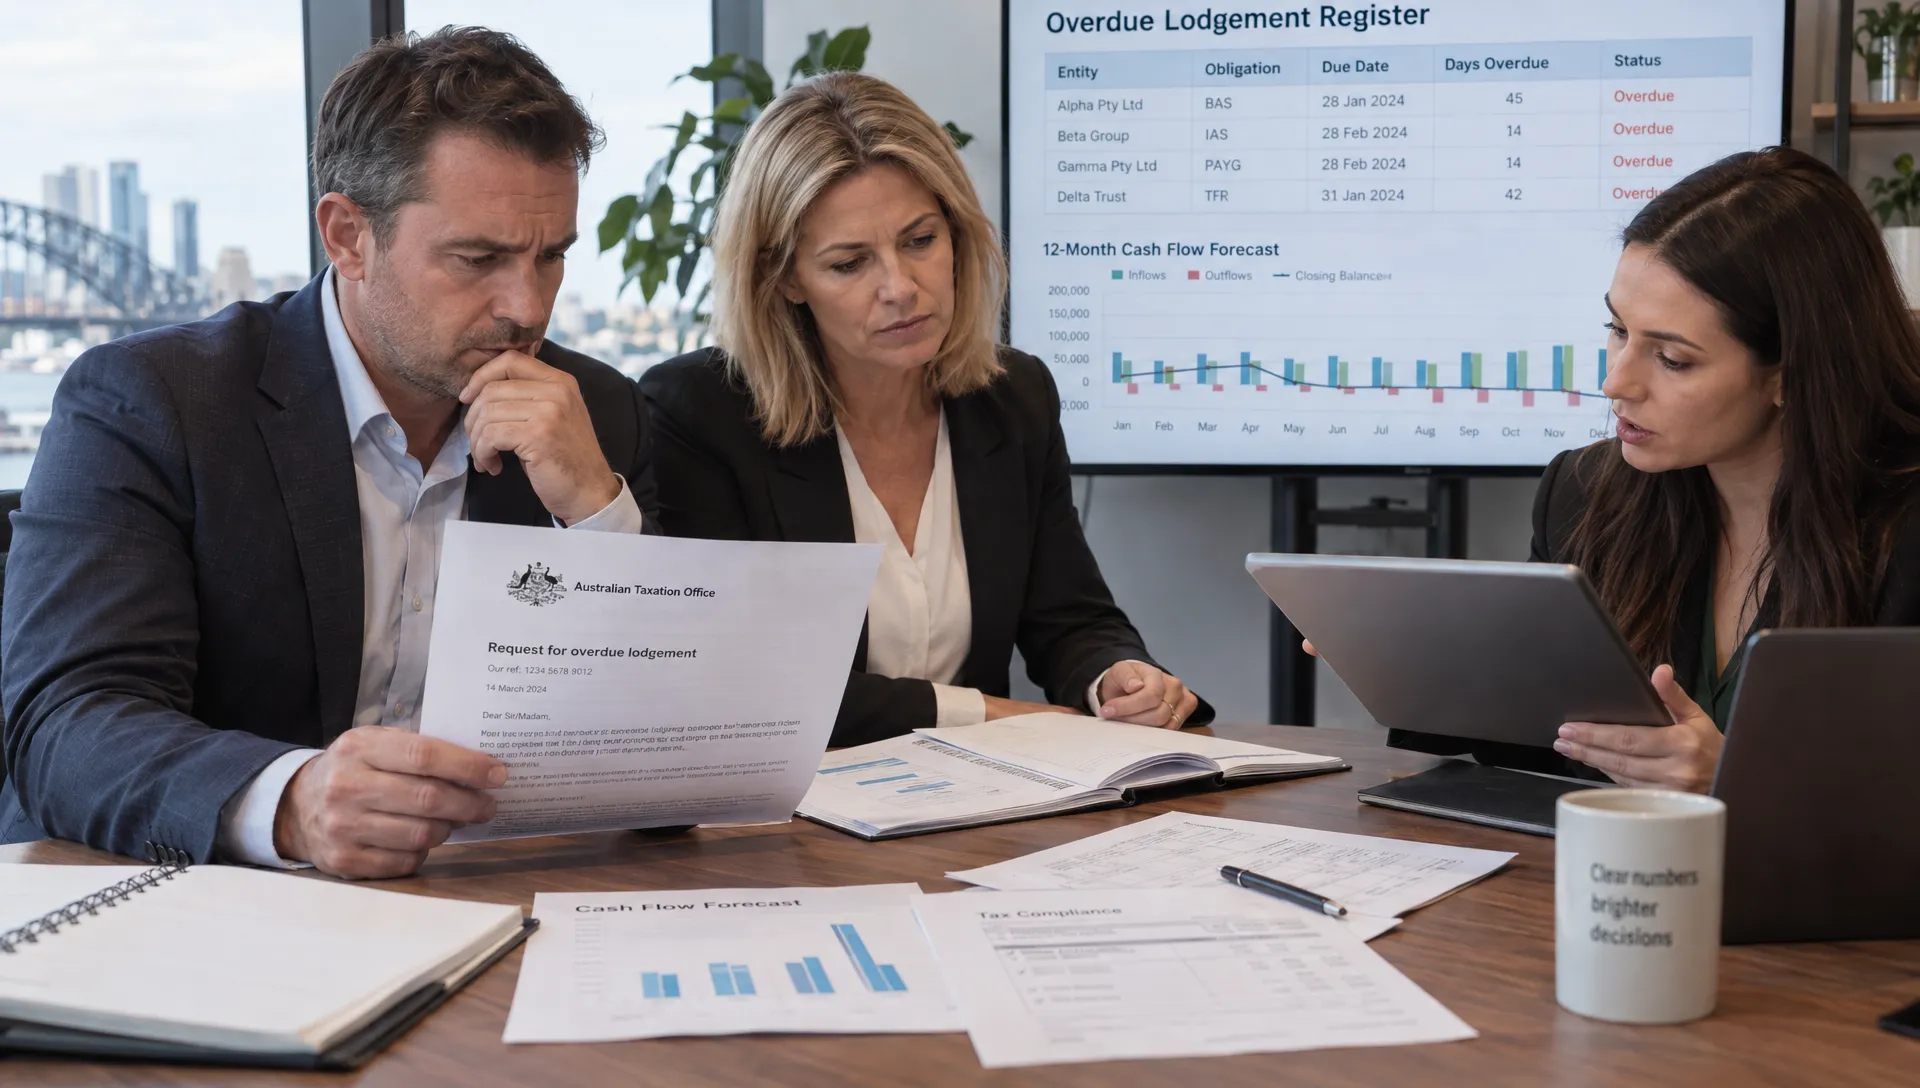
We assemble one register covering outstanding returns, BAS, SGC statements and other relevant obligations. It records due dates, lodgement status, payment status, notices received and responsibility for the next action.
For late tax filing, we review the underlying ATO account transactions rather than relying only on a single balance. We distinguish assessed debts, interest, penalties and amounts that have not yet been reported. We also check whether the company has received default assessments or estimated liabilities, which may require a specific response.
Directors with trusts, investment entities or significant personal assets need separate entity-level records. We do not assume that resolving the trading company’s backlog also resolves a family trust’s return or the director’s personal position.
Rebuild reliable records and prioritise lodgements
We reconcile bank transactions, payroll, GST coding and supporting documents before relying on the figures. Where records are incomplete, we identify the missing evidence and establish a defensible reconstruction method. Speed matters, but unsupported figures can replace a lodgement problem with an assessment dispute.
We prioritise statutory deadlines and director exposure alongside the practical dependencies between reporting periods. The oldest return is not always the first document requiring action.
Our approach to late tax filing combines AI-driven automation with professional review to reduce manual handling and surface discrepancies earlier. AI-assisted document organisation and transaction checks can accelerate preparation, but tax treatment, substantiation and final lodgement decisions require qualified judgement.
We also review company tax return errors that can attract ATO attention where reconstructed records reveal inconsistent revenue, payroll or related-party balances. Catch-up work should resolve those discrepancies, not carry them into another reporting period.
Align payment arrangements with solvency
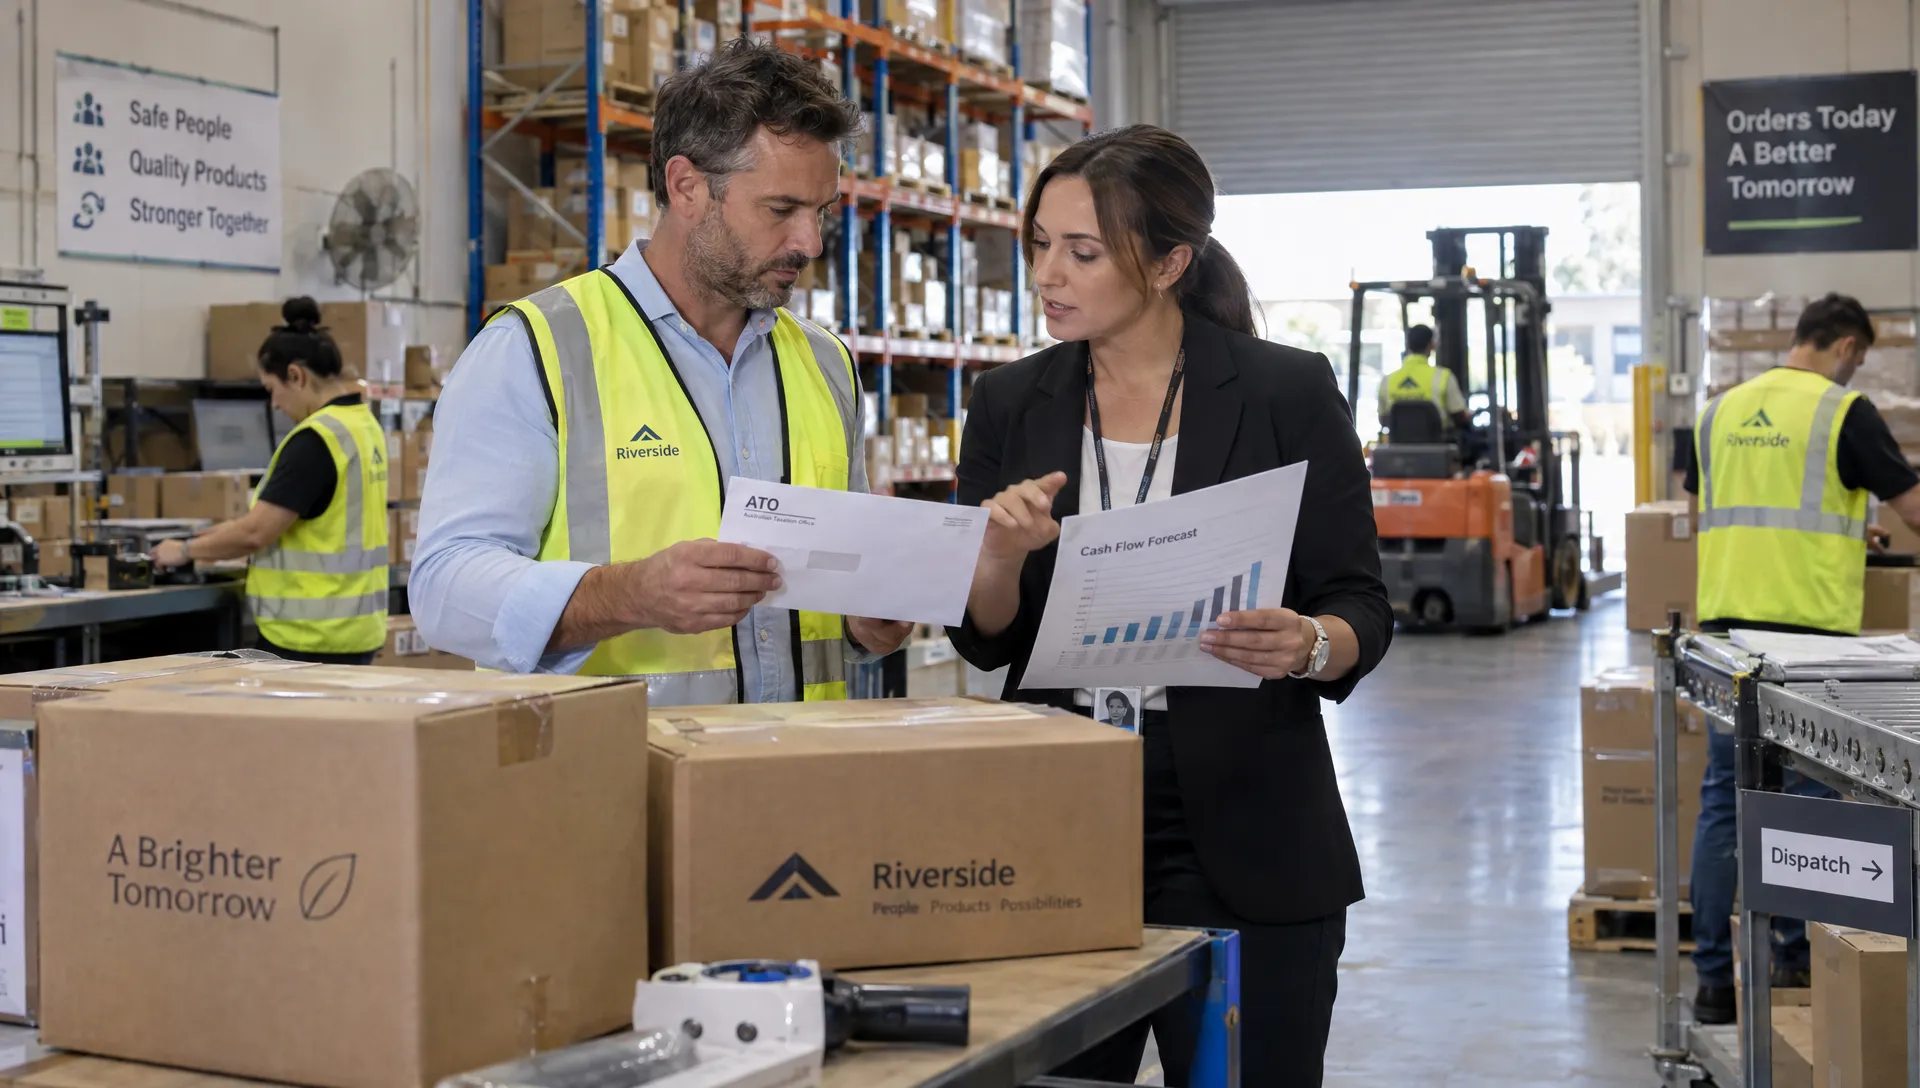
We prepare a cash-flow forecast that separates historic tax arrears from current obligations. A repayment proposal is not sustainable if it leaves the company unable to meet new BAS liabilities, wages or superannuation obligations.
We assess realistic payment capacity before approaching the ATO. Payment plans address debt collection arrangements; they do not erase lodgement failures, guarantee interest remission or automatically remit director penalties.
Where forecasts indicate an inability to pay debts as they fall due, we recommend urgent independent insolvency advice. Directors should not treat a pending return, an expected refund or an anticipated asset sale as proof of solvency.
This is the point where compliance becomes strategic advisory. We use the reconstructed position to assess working capital, funding requirements and whether planned distributions or investment should be reconsidered.
Prevent recurrence with board-level financial controls
Once immediate risks are addressed, we treat late tax filing as a control failure to investigate, not simply a missed deadline to close. The cause may be unclear ownership, poor source records, an unresolved software migration or a cash shortage that led management to postpone reporting.
We recommend a single compliance register with named owners, advance reminders and escalation rules. Directors should receive confirmation that documents were lodged, not merely prepared. Payment status belongs alongside lodgement status so that an accepted return is not mistaken for a settled liability.
Digital transformation strengthens this process when it makes exceptions visible early. Automated reminders, transaction matching and document capture can reduce repetitive work. Regular reconciliation and professional review are what make the resulting financial visibility reliable.
Our integrated accounting and advisory services support clients across Australia, including Adelaide, Sydney and Melbourne. For cross-state businesses, a unified view of obligations helps prevent local teams or advisers from assuming that another office has handled the task.
We use that foundation to support corporate growth: more dependable forecasts, better funding decisions and earlier identification of financial pressure. The objective is a controlled reporting cycle that informs management throughout the year.
Frequently asked questions
Should a company lodge if it cannot pay the tax? We generally recommend lodging accurate documents by the required deadline and addressing payment separately. Delaying reporting can add penalties and, for relevant liabilities, worsen director penalty exposure. We assess payment options against the company’s cash flow and any active notices.
Does late tax filing automatically make directors personally liable? No. We distinguish ordinary company income tax obligations from liabilities covered by the director penalty regime. Unpaid PAYG withholding, net GST and SGC can create personal exposure, and delayed reporting can restrict remission options.
Can a tax agent obtain an extension after the deadline? We check whether a deferral or other relief is available for the specific obligation and circumstances. Engaging an agent after a deadline does not automatically provide a retrospective extension or remove existing penalties.
Can the ATO waive penalties or interest? We can assess a remission request and prepare supporting evidence. The ATO decides whether relief is justified. We do not assume that financial difficulty alone will produce full remission.
Will AI resolve an overdue tax backlog without professional review? No. We use automation to improve processing speed and consistency, while retaining professional review of tax treatment, evidence and exceptions. Incomplete records and legal exposure require judgement, not just faster data processing.
Next steps: restore compliance and financial visibility
We recommend bringing all ATO notices, an outstanding-obligations list, recent financial records and current cash-flow information to an initial consultation. Any DPN should be identified immediately rather than held for a routine appointment.
Our team at Perfect Accounting & Tax Services combines 25 years of professional experience with AI-driven automation and strategic advisory. We help assess late tax filing risks, establish a prioritised remediation plan and strengthen the financial controls behind ongoing compliance.
Contact our team for a consultation to review director exposure, overdue obligations and how our automated accounting workflows can support more accurate reporting and clearer financial decisions.