As business tax specialists, we generally favour a sole trader structure for a low-risk, owner-operated business that needs simplicity and draws out most of its profit. We consider a company when liability exposure, retained earnings, staffing or investment plans justify the additional obligations.
We do not recommend a structure on turnover alone. For Australian owners and directors, the better choice depends on how profit is earned, how much cash is needed personally and what the business will become.
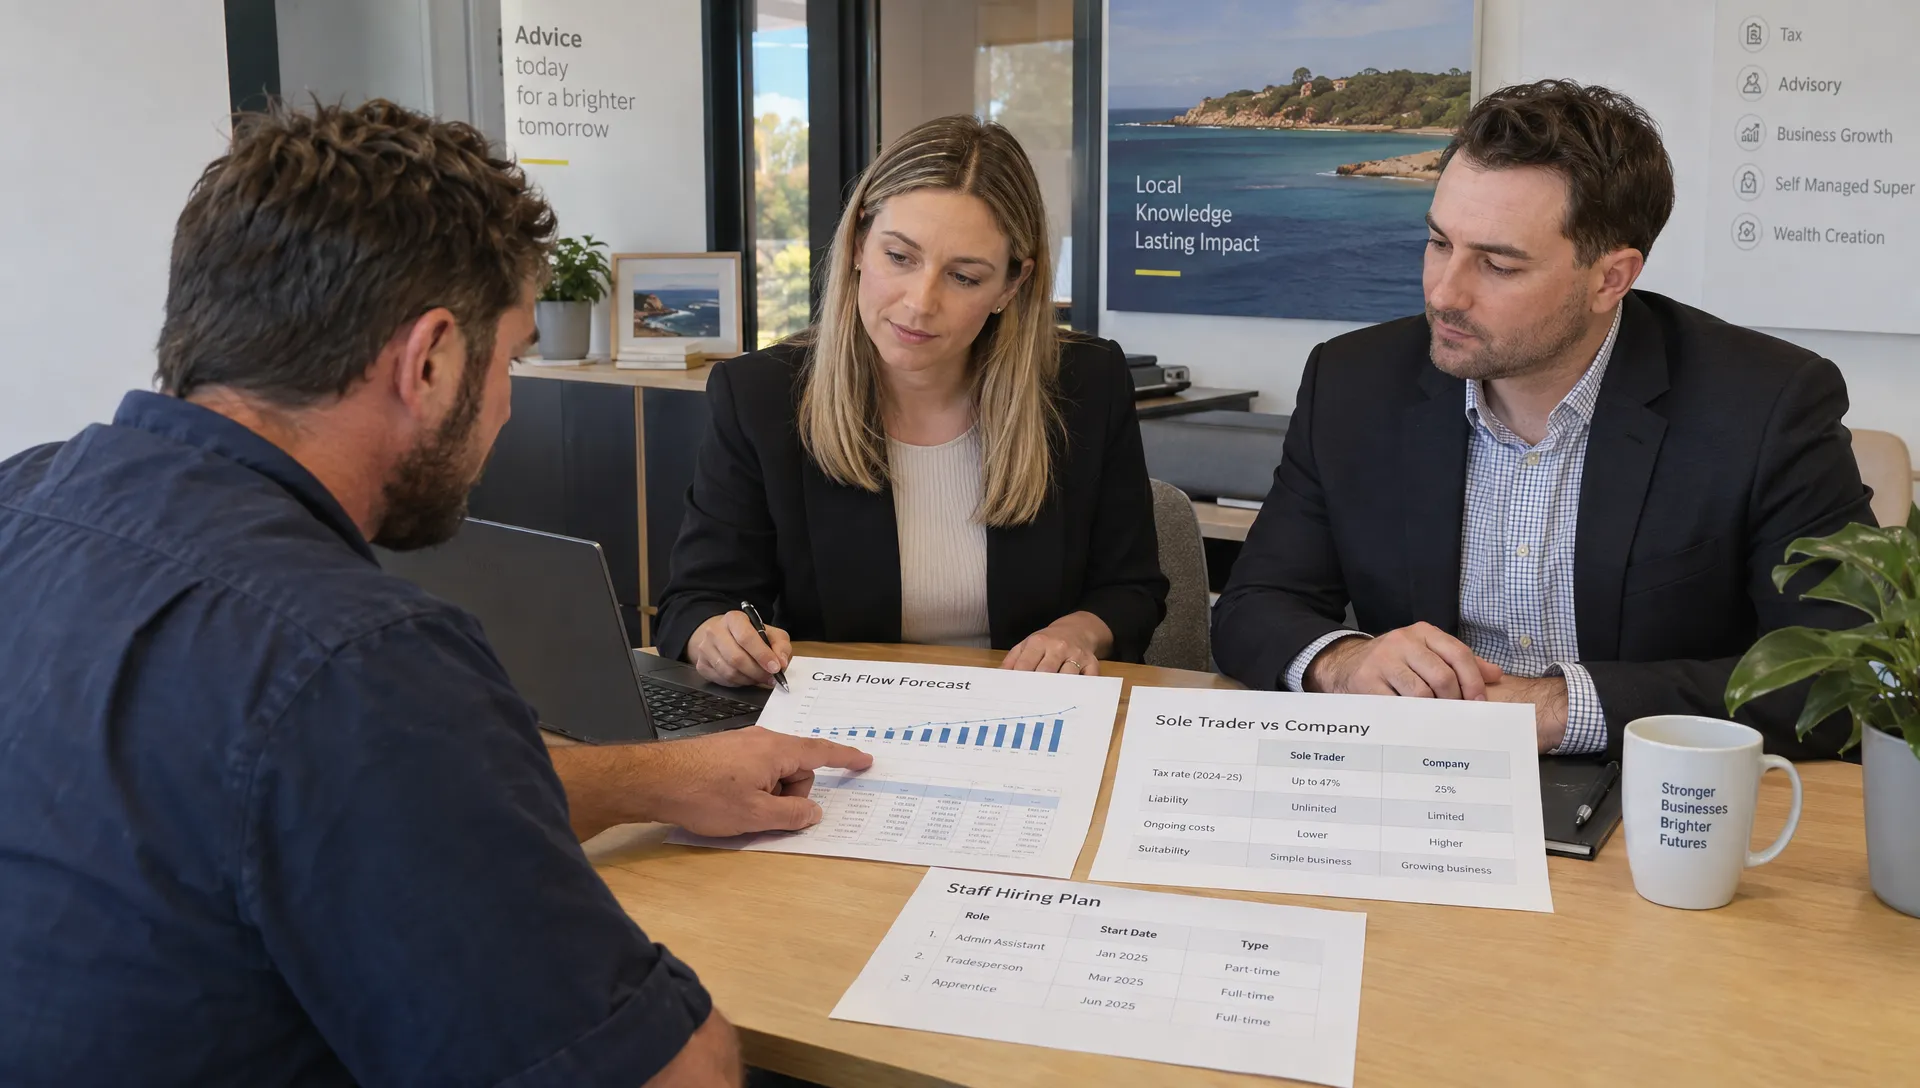
Our starting comparison
We begin with the commercial differences rather than assuming a company automatically delivers a better tax outcome.
| Decision factor | Sole trader | Company |
|---|---|---|
| Legal identity | Owner and business are the same legal person | Separate legal entity |
| Income tax | Business profit is taxed at the owner's individual rates | Company pays tax on its taxable income; owners may also pay tax when receiving money |
| Liability | Owner is personally responsible for business debts | Shareholder liability is generally limited, but director exposure and guarantees remain |
| Access to money | Drawings are not wages or deductible expenses | Payments need an appropriate basis, such as salary, dividends or documented loans |
| Administration | Generally simpler and less costly | ASIC obligations, separate tax reporting and director duties |
| Ownership changes | Cannot issue shares | Can introduce shareholders, subject to appropriate arrangements |
We weigh these differences against a three-year forecast. A structure that suits today's consultancy may be unsuitable once it employs a team or brings in investors.
How business tax specialists compare the tax outcome
The company rate is only the first calculation
We distinguish tax paid by the business from tax ultimately paid by its owner.
A sole trader pays individual income tax on net business profit, whether that profit is withdrawn or left in the business bank account. Personal drawings do not reduce taxable profit.
Under the ATO's company tax rate rules, eligible base rate entities pay 25%. Broadly, eligibility requires aggregated turnover below $50 million and no more than 80% of assessable income comprising base rate entity passive income. Other companies generally pay 30%.
A company can retain after-tax profit for working capital or investment. However, that money belongs to the company. When it reaches an individual shareholder as a dividend, further personal tax may arise after allowing for franking credits.
A $200,000 profit example
We use the following simplified illustration to show why the headline rate can mislead. We assume $200,000 taxable business profit, no owner salary, a company eligible for the 25% rate and an Australian-resident individual owner with no other income.
Using 2026–27 resident individual tax rates and the standard 2% Medicare levy, the comparison is:
| Treatment | Sole trader | Company retaining all after-tax profit |
|---|---|---|
| Taxable business profit | $200,000 | $200,000 |
| Initial income tax, including the owner's Medicare levy where applicable | $59,870 | $50,000 |
| Cash remaining after that tax | $140,130 available to the owner | $150,000 belonging to the company |
As business tax specialists, we then test what happens when the owner needs the retained cash.
If the company distributes the full $150,000 as a fully franked dividend in the same year, with sufficient franking credits, the shareholder includes $200,000 in assessable income and receives a $50,000 franking credit. Additional personal tax and Medicare levy total $9,870. Combined company and shareholder tax therefore reaches $59,870.
We exclude the Medicare levy surcharge, HELP repayments and other adjustments from this illustration. The potential advantage is the timing of personal tax and access to reinvestment capital, not an automatic permanent saving.
Liability protection has limits
We give greater weight to incorporation where a business takes on substantial contracts, employees, debt or operational risk. A separate entity can create a useful boundary between business obligations and shareholder assets.
That boundary is not absolute. Directors may face personal exposure through guarantees, insolvent trading, breaches of duty or director penalty provisions covering certain unpaid PAYG withholding, GST and Superannuation Guarantee Charge liabilities.
Our business tax specialists assess the structure alongside insurance, contract terms and director conduct. We do not treat incorporation as a substitute for sound risk management.
For example, an Australian transport business engaging overseas personnel may encounter an overseas online drug and alcohol assessment provider. We would check the service's jurisdiction and intended use rather than assume an overseas assessment satisfies Australian workplace or licensing requirements. Incorporation cannot resolve that operational compliance risk.
For a low-risk consultant, the additional protection may be less decisive than professional indemnity insurance and carefully drafted engagement terms. We recommend legal input where asset protection or contractual exposure drives the decision.
Drawing money out: where company owners get caught
We often find that the practical difficulty is not company tax itself, but the owner's access to cash.
A sole trader can transfer money to a personal account as drawings, provided enough remains for tax and business obligations. The transfer does not create a wage deduction.
A company requires greater separation. We assess payments as salary or director fees, dividends, reimbursements or loans. Each has different documentation and tax consequences.
When business tax specialists model a company structure, we therefore include the owner's household cash requirements. Retaining profit provides little flexibility if nearly all available cash must immediately fund personal living costs.
Private payments and shareholder loans can also trigger Division 7A, potentially producing an unfranked deemed dividend unless an exclusion or compliant arrangement applies. A year-end journal entry does not necessarily fix the problem.
We also budget for Superannuation Guarantee on eligible remuneration and consider FBT where benefits are provided. These obligations belong in the forecast before incorporation, not after the first payroll run.
Compliance costs should buy better decisions
We compare the full annual cost of each structure, not just the incorporation fee.
A company brings ASIC annual review obligations, corporate records, a separate tax return and additional governance. Payroll, BAS and FBT requirements depend on its activities. A sole trader can also have employees, GST obligations and complex reporting, so simpler does not mean compliance-free.
We recommend an itemised scope covering establishment, recurring compliance, payroll, management reporting and strategic advice. Without that breakdown, a low annual fee may exclude the work needed to operate the structure properly.
Our business tax specialists treat accurate bookkeeping as the foundation for Strategic Advisory and Corporate Growth. Reliable figures allow us to assess hiring capacity, tax reserves and the return on reinvesting profits.
We combine AI-driven automation with professional review to improve processing accuracy and speed while supporting real-time financial visibility. Automation is most valuable when it reduces repetitive work and gives us better information for decisions; it does not replace judgement about tax treatment or director obligations.
For owners remaining unincorporated, our sole trader tax setup guidance explains the foundations we would want in place before growth makes the records more demanding.
Three situations that can change our recommendation
A consultant whose income mainly rewards personal effort
We check the personal services income (PSI) rules before projecting company tax savings for consultants, contractors and other professionals.
Earning income through a company does not automatically prevent the PSI rules from applying. Where relevant, attribution and deduction restrictions can substantially change the expected outcome.
We assess whether the income is PSI, whether a personal services business determination or test applies and whether the overall arrangements raise other tax issues. Our recommendation may still favour a company for commercial reasons, but we would not promise income splitting or retained-profit benefits without examining the facts.
An owner building assets or preparing an exit
We separate the trading business decision from the ownership of valuable property, investments and intellectual property.
Companies cannot claim the general 50% CGT discount. Eligible individuals may qualify for that discount on assets held for at least 12 months. Small business CGT concessions are separate and require their own eligibility assessment.
We also distinguish a future sale of business assets from a shareholder's sale of shares. Buyers may prefer one transaction while sellers prefer another. Bringing family members into ownership adds succession and governance questions that deserve attention before shares or assets change hands.
A growing business retaining cash for expansion
We are more likely to favour a company where profits can genuinely stay inside the business to fund staff, equipment or a new location.
Our business tax specialists test that proposition against cash flow, not accounting profit alone. We deduct working capital needs, debt repayments, tax payments and the owner's remuneration before deciding how much can be reinvested.
We also assess whether incoming investors require shares and whether a shareholders agreement should address decision-making, departures and disputes. A company can support growth, but it needs governance that matches the ownership arrangements.
Moving from sole trader to company requires a transition plan
We do not recommend simply registering a company and directing future invoices into a new bank account. The business assets, contracts and obligations need a coordinated transfer.
A company needs its own ABN and TFN. GST registration, payroll arrangements, insurance and customer or supplier agreements may also need to change. Directors need to meet director ID and ASIC requirements.
Asset transfers can trigger CGT, GST or state-based duty consequences. Restructure rollovers or concessions may be available, but they are conditional and do not automatically remove every tax or duty cost.
We involve business tax specialists before the effective transfer date so that eligibility, valuations and documentation can be assessed while options remain open. State-specific legal advice may also be necessary, particularly where land or significant contracts are involved.
Our transition plan establishes an opening balance sheet, transfers assets and liabilities appropriately and separates pre-transfer from post-transfer trading. We also agree on the bookkeeping cut-off and responsibility for outstanding BAS and tax returns.
A focused tax consultation before lodgement can identify record gaps, although we prefer to model a restructure before transactions are committed.
Frequently asked questions
Is there a profit level where a company automatically becomes better? We do not use a universal threshold. Other personal income, cash withdrawals, PSI, liability exposure and recurring compliance costs can change the answer. A higher profit makes modelling more worthwhile, but does not settle the decision.
Can a sole trader employ staff? Yes. We can support a sole trader with employees, payroll and Superannuation Guarantee obligations. Hiring does not itself require incorporation, although the resulting risk and administrative demands may justify reviewing the structure.
Does changing to a company remove GST obligations? No. We generally assess GST registration when GST turnover reaches $75,000, subject to special rules such as those applying to taxi and ride-sourcing services. Changing the legal entity requires separate attention to registrations and reporting.
Can business losses reduce tax on other income? We assess sole trader losses against the non-commercial loss rules before offsetting them against salary or other income. Company losses generally remain within the company, with future use subject to the applicable loss rules. Our business tax specialists include downside scenarios rather than modelling profitable years alone.
Next steps: build a structure decision around your numbers
We recommend preparing three inputs before deciding:
- A three-year forecast: Expected profit, working capital needs, planned investment and likely hiring.
- A personal cash budget: Required drawings or remuneration, other income and existing financial commitments.
- A risk and ownership summary: Major contracts, borrowings, guarantees, valuable assets and potential investors or successors.
We bring 25 years of professional experience to these decisions, with integrated support across Adelaide, Sydney and Melbourne for clients throughout Australia.
Our business tax specialists can compare both structures, identify transition costs and explain how our automated accounting workflows support ongoing visibility. Contact Perfect Accounting & Tax Services to arrange a consultation before incorporating or transferring business assets.
We provide this comparison as general information. Our recommendation depends on your circumstances and the law applying when the proposed transactions occur.