Reliable business tax preparation starts before the annual return. We need confidence that GST collected, GST credits claimed and amounts reported through the Business Activity Statement (BAS) reflect the underlying transactions. A balanced bank account alone does not establish that confidence.
At Perfect Accounting & Tax Services, we combine AI-driven automation with professional review to make GST checks more systematic. Our objective is not to approve every transaction automatically. We aim to identify exceptions earlier, preserve supporting evidence and give directors a clearer view of liabilities before lodgement.
We establish the GST rules before automating checks
We begin with the entity’s GST registration, reporting cycle and accounting basis. These settings determine which transactions belong in each reporting period and prevent automation from applying the wrong assumptions consistently.
For standard transactions, cash-basis reporting generally attributes GST and credits to payments received or made, to the extent paid. Under non-cash accounting, attribution generally follows the earlier of invoicing or payment, subject to the relevant rules and documentation requirements. We treat deposits, special arrangements and unusual transactions separately.
We also map the business’s revenue streams. Taxable, GST-free and input-taxed supplies require different treatment. GST-free and input-taxed sales are not interchangeable: their treatment can affect entitlement to credits on related purchases.
We use the ATO’s GST guidance as the starting point for these settings. We then document the entity-specific decisions, including mixed-use expenses and activities requiring apportionment. Automation becomes useful only after those rules are established.
How we structure business tax preparation around GST controls
We design the workflow around three layers: reliable transaction data, repeatable validation rules and a review queue for unresolved items. AI assists with extracting invoice information and identifying unusual patterns; deterministic checks handle calculations and comparisons.
The distinction matters. An invoice-reading model can recognise an amount labelled “GST”, but that label does not establish a legal entitlement to claim it. We retain professional judgement over tax treatment rather than allowing a model’s prediction to become the final decision.
We bring together authorised accounting records, bank transactions, sales reports and supporting documents where the agreed workflow permits. We check completeness before reviewing individual tax codes. Missing settlement reports or duplicate imports can distort the entire GST calculation.
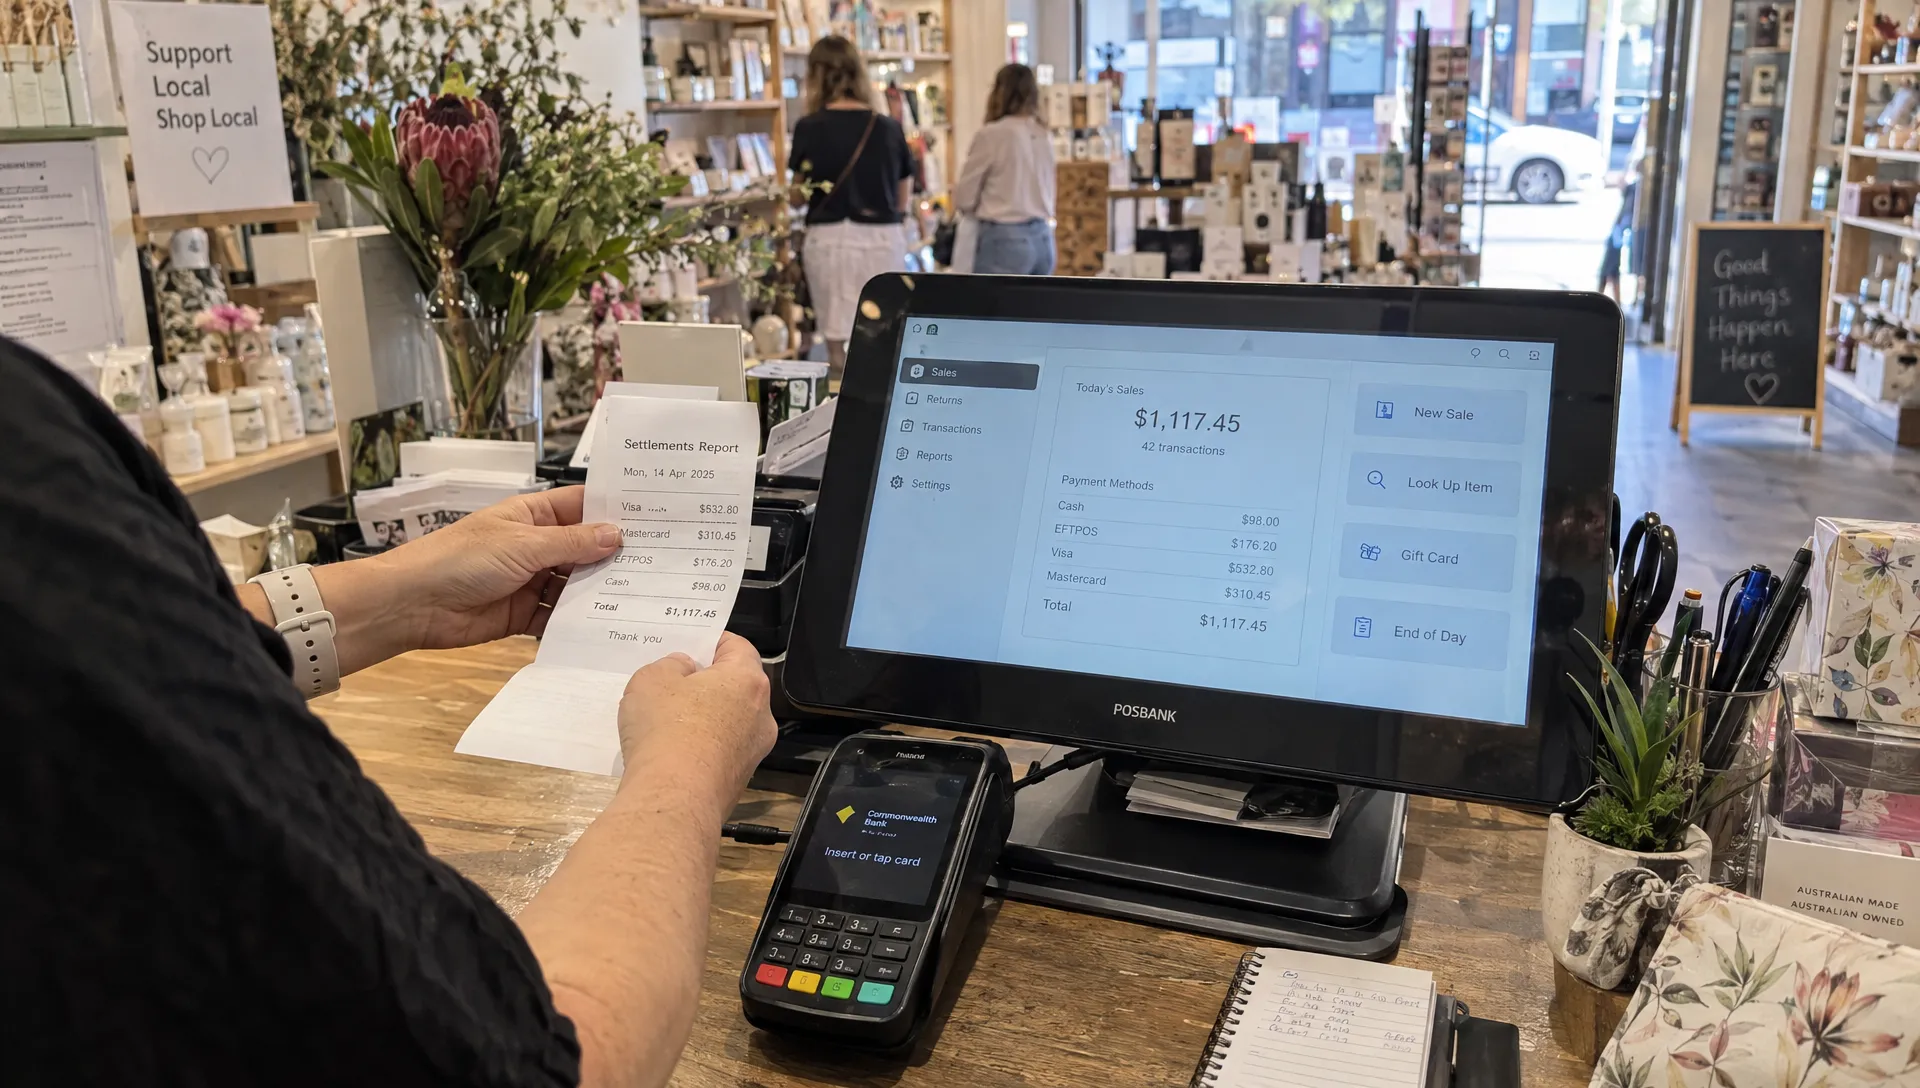
For payment platforms, we reconcile gross sales, refunds, fees and net deposits separately. A bank receipt after processing fees is not necessarily the correct sales amount for GST reporting. We also distinguish genuine duplicates from instalments or recurring invoices.
Our approach gives reviewers a traceable path from the source document to the ledger entry. This supports faster investigation without assuming that a bank feed provides all the evidence needed for a GST claim.
We validate suppliers, invoices and credit eligibility
For business tax preparation, we separate document extraction from the decision to claim a GST credit. A correctly captured invoice can still contain the wrong supplier details, an unsupported GST amount or expenditure that is partly private.
We check the supplier’s ABN and relevant GST registration details against ABN Lookup. Registration checks need to consider the transaction date, not simply the supplier’s current status. We escalate inconsistent details rather than treating an ABN match as proof that the purchase qualifies.
For purchases costing more than $82.50 including GST, a valid tax invoice is generally required before claiming a credit, subject to applicable exceptions. Smaller purchases still require adequate supporting records. We use the ATO’s tax invoice requirements to guide document checks.
We then assess business use, credit eligibility and any restrictions. Private expenditure and purchases relating to input-taxed activities may require exclusion or apportionment. Imported goods can require customs documentation rather than a conventional Australian supplier tax invoice.
We flag overseas software subscriptions and other offshore services for the appropriate GST assessment. Foreign currency, an Australian customer address or a document labelled “tax invoice” does not, by itself, establish an Australian GST credit.
We use exception rules instead of blanket approval
We apply arithmetic checks alongside contextual rules. For a wholly taxable amount that includes GST at the standard 10% rate, the GST component is one-eleventh of the total. We do not apply that calculation indiscriminately to mixed invoices or GST-free purchases.
| Control | What we test | Review outcome |
|---|---|---|
| Invoice arithmetic | Whether line totals, GST and the invoice total agree | Resolve discrepancies before posting or claiming |
| Duplicate detection | Repeated supplier, invoice number, amount and date combinations | Confirm whether records represent one purchase or separate transactions |
| Tax-code consistency | Unexpected changes from an established, reviewed treatment | Check the transaction rather than copying historical coding |
| Mixed-use expenditure | Whether an approved business-use allocation applies | Review or update the supported allocation |
| Period attribution | Whether the transaction belongs in the reporting period under the entity’s accounting basis | Correct timing before lodgement |
We prioritise exceptions by potential impact, recurrence and uncertainty. A small recurring coding error can deserve more attention than an isolated low-risk difference because its annual effect may be substantial.
In business tax preparation, we use these checks to focus professional attention, not to remove it. We hold unresolved credit claims for review rather than allowing missing evidence or uncertain treatment to pass through simply because the invoice was captured successfully.
We collect evidence as part of the workflow
We aim to attach evidence when the transaction is processed, not reconstruct it when the BAS is due. The supporting record should connect the invoice, payment or settlement information, tax treatment and any reviewer decision.
When a document is missing, we favour a targeted request identifying the supplier, transaction date and exact evidence required. Where the workflow supports it, reminders and status updates can reduce repeated manual chasing. A vague request for “all outstanding receipts” creates unnecessary work for both the business and the reviewer.
For control design, Naltilia’s guide to automating evidence collection for compliance controls explains useful patterns such as event-triggered requests and prefilled attestations. We apply the underlying principle of collecting evidence at the point of activity, while assessing Australian GST requirements separately.
An internal approval cannot replace a tax invoice where one is required. We preserve both the underlying document and the explanation for any judgement, including apportionment or an unusual tax treatment.
We also establish access permissions and retention settings. GST and other business records generally need to be retained for at least five years, with longer periods applying in some circumstances. We avoid placing TFNs, bank details or confidential commercial documents into unapproved AI tools.
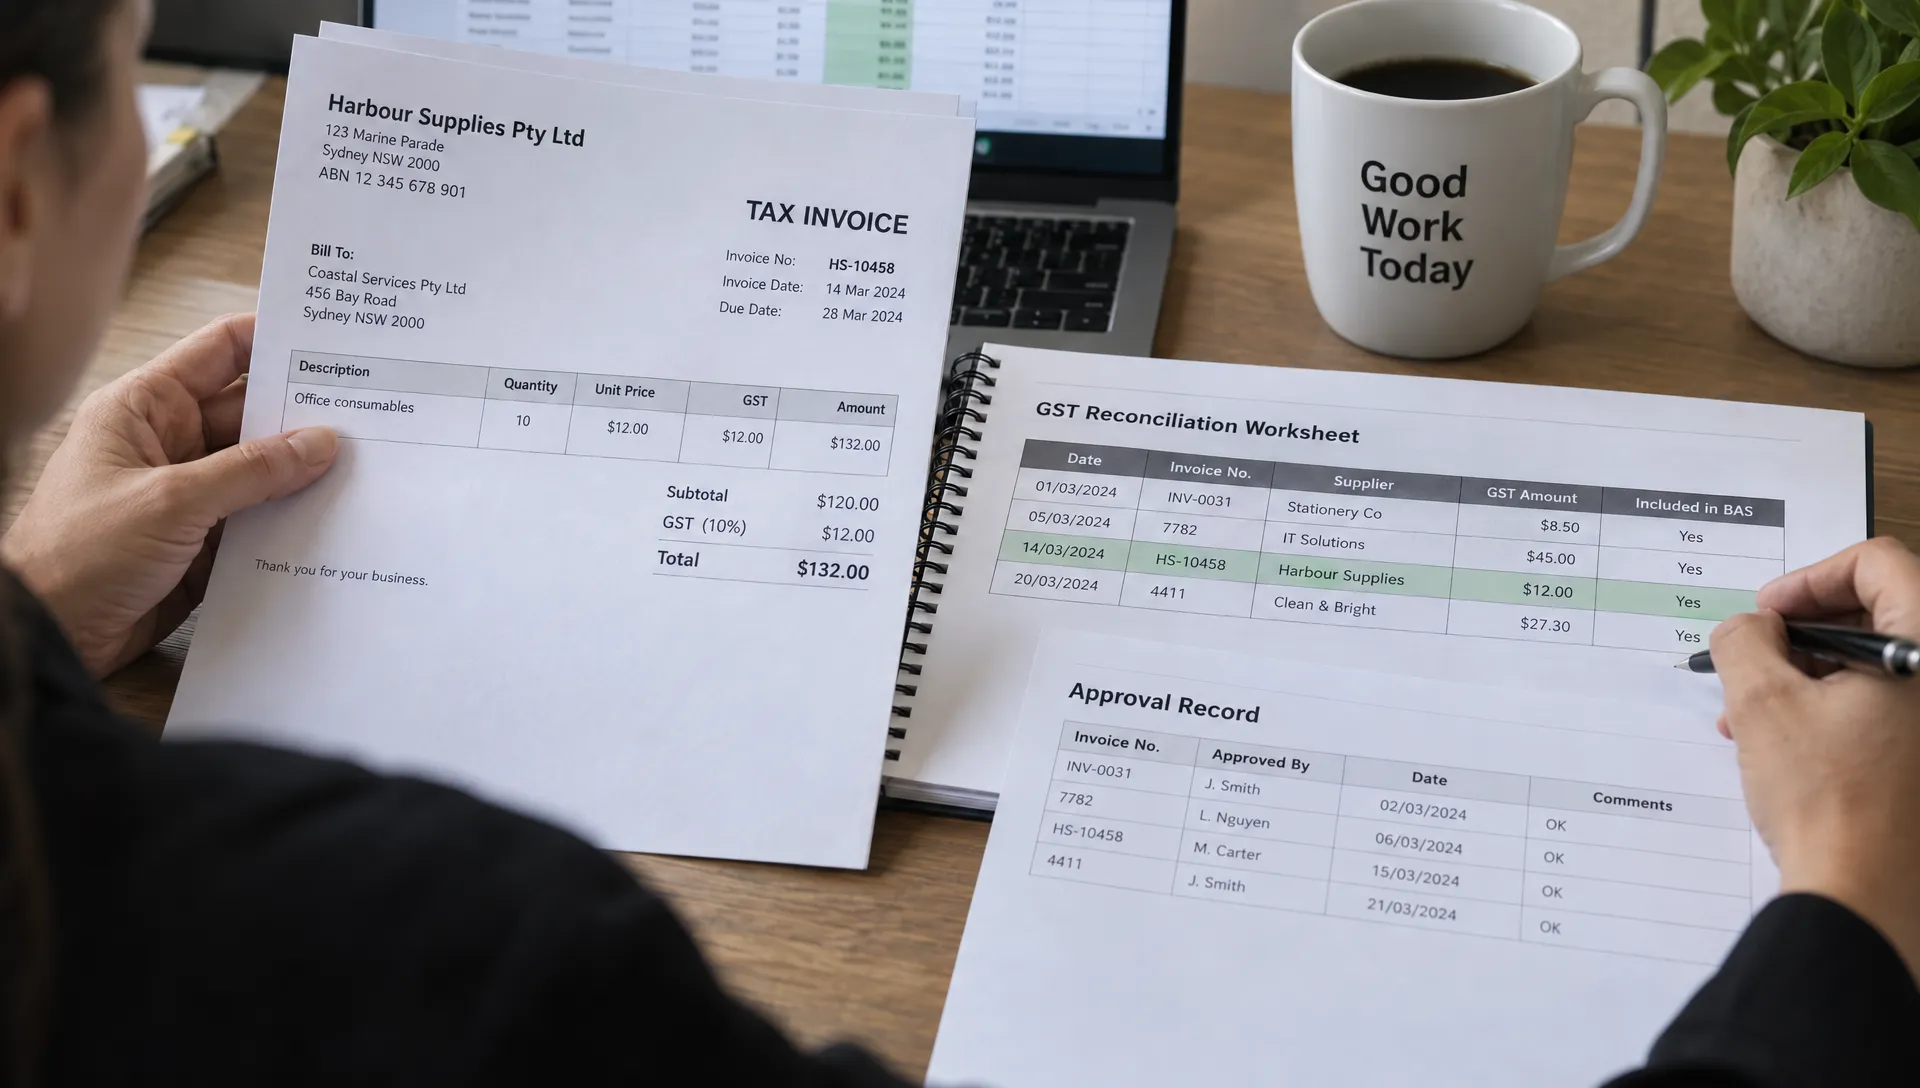
We reconcile the BAS to the ledger and source records
Transaction checks are only one part of the process. Before lodgement, we reconcile GST collected and creditable GST to the relevant BAS amounts, including labels 1A and 1B. We also review sales reporting and other applicable labels for the entity’s reporting arrangement.
We reconcile the GST control accounts to lodged statements, payments, refunds and outstanding balances. Differences require an explanation. They should not be cleared through an unexplained journal merely to make the accounts appear balanced.
At year end, we bridge BAS-reported sales to accounting revenue and the income tax return. These amounts need not be identical. Cash versus non-cash timing, GST-inclusive reporting, asset disposals and other differences can require reconciliation.
We make business tax preparation more dependable by documenting that bridge rather than assuming every mismatch is an error. Our discussion of company tax return errors that can attract ATO attention provides further context for reviewing unexplained inconsistencies.
We also keep GST distinct from PAYG withholding, Superannuation and FBT obligations. These can affect the same cash-flow forecast, but they follow different rules and reporting processes. A GST reconciliation cannot substitute for the broader compliance review.
We control corrections and changes to automation
When we identify an error in a lodged BAS, we assess the permitted correction pathway. Some errors can be corrected in a later BAS within the ATO’s applicable conditions and limits; others require revising the original statement.
We distinguish these errors from genuine GST adjustments arising from subsequent events, such as changes in consideration or use. We do not silently alter a closed reporting period and assume the next lodgement will resolve it.
The same discipline applies to automation changes. We test new coding rules against a sample of previously reviewed transactions before expanding their use. We pay particular attention to supplier changes, new revenue streams and businesses entering unfamiliar markets.
Our business tax preparation controls should remain explainable after a software update or staff change. We therefore document significant rule changes, approval responsibilities and the reasons for overrides. We retain a clear distinction between an automated suggestion and an authorised accounting decision.
This governance reduces the risk of a mistaken rule being repeated across hundreds of transactions. We also review rejected suggestions, since repeated corrections may indicate a weakness in the underlying rule rather than isolated user error.
We turn GST visibility into strategic advisory
A reliable GST position helps us distinguish available cash from money required for tax obligations. That distinction supports decisions about stock purchases, hiring, distributions and capital expenditure.
We use current, reconciled records to improve financial visibility between reporting dates. The usefulness of that visibility depends on timely data feeds, complete documents and resolved exceptions. An attractive dashboard cannot compensate for stale or incorrectly coded transactions.
We assess automation through measurable controls: the proportion of transactions with complete evidence, the number of unresolved exceptions, recurring coding issues and the time required to complete a reconciliation. We establish a baseline before attributing improvements to the workflow.
Our business tax preparation process then becomes a foundation for strategic advisory and corporate growth. Earlier identification of liabilities and errors gives us a stronger basis for cash-flow forecasting, financing discussions and investment planning.
We support businesses across Australia through integrated service capabilities in Adelaide, Sydney and Melbourne. For multi-city operations, we align GST controls across locations while preserving visibility over each entity’s records, reporting obligations and approval responsibilities. GST is a national tax, but inconsistent local processes can still create avoidable reporting risk.
Frequently asked questions
Can AI determine whether every purchase qualifies for a GST credit? We use AI to assist with extraction and exception detection, not to make unrestricted tax decisions. Credit eligibility can depend on business purpose, documentation, input-taxed activities and transaction-specific rules. We retain professional review for uncertain treatment.
Can we claim GST because a bank feed shows the payment? We do not treat a bank entry as sufficient evidence in every case. It establishes payment activity, but may not establish the supplier’s GST status, the GST amount or the required tax invoice details.
Does GST automation replace BAS review? We retain reconciliation and approval before lodgement. Automation improves the consistency of checks and reduces repetitive work, but incomplete data or incorrect rules can still produce an incorrect statement.
How does this support the annual business tax preparation process? We carry forward reconciled GST balances, documented exceptions and an explained bridge between BAS sales and annual revenue. This reduces the need to reconstruct transactions at year end and supports a more informed tax review.
Next steps: review our automated accounting approach
We recommend starting with one entity and one reporting cycle. We can review the accounting basis, sample invoices, recent BAS reconciliations and recurring exceptions to identify where automation would provide the most value.
With 25 years of professional experience, our team connects compliance discipline with financial strategy. A pre-lodgement tax consultation can help establish the scope of that review.
Contact Perfect Accounting & Tax Services for a consultation about GST controls and our automated accounting workflows. We can discuss an approach suited to the business’s systems, transaction complexity and growth plans.