We manage trust tax submission Australia-wide by connecting trustee decisions, beneficiary reporting and ATO lodgement. For business owners, company directors and high-net-worth families, a reliable return starts with the trust deed and distribution decisions, not the lodgement software.
Our approach combines technical review with AI-supported accounting workflows. We use compliance as the foundation for strategic advisory: understanding where income is taxed, whether cash is available to meet liabilities and how the structure supports future investment or corporate growth.
Here, we explain our approach to ordinary discretionary and unit trusts. Deceased estates, managed investment trusts and other specialised structures can require different treatment.
We establish the trust’s legal and reporting position first
Before preparing figures, we confirm which entity earned the income, who controls the trust and which beneficiaries can receive distributions. A corporate trustee and the trust it administers are not the same taxpayer.
Our initial review covers:
- Governing documents: The executed trust deed, amendments, trustee appointments and relevant beneficiary definitions.
- Registrations: The trust’s TFN, ABN and GST registration where applicable, together with authorised access arrangements.
- Historical positions: Prior returns, distribution resolutions, carried-forward losses, elections and outstanding ATO obligations.
- Financial records: Bank accounts, investment statements, property records, business accounts and beneficiary balances.
- Structural changes: Changes in control, residency, ownership or business activities that may affect the tax analysis.
The ATO’s guidance on trusts provides the starting framework, but the deed and actual transactions determine how that framework applies.
We also distinguish the income tax return from BAS, payroll, Superannuation and FBT obligations. Where these apply, we reconcile them without treating one lodgement as a substitute for another. This establishes a defensible starting point for trust tax submission in Australia.
We resolve distribution decisions before preparing the return
A discretionary trust’s distribution strategy cannot safely be reconstructed after year-end simply because the accounts are finished later.
We review the deed’s requirements and arrange for valid trustee decisions by 30 June, or an earlier deadline where the deed requires it. We document those decisions accurately and do not backdate resolutions. Specific rules can apply to capital gains and franked distributions, so we assess those components separately rather than assuming one resolution covers everything.
Our review considers beneficiary eligibility, tax residency, age, other income and the commercial purpose of the distribution. We also examine who will receive or benefit from the money.
An unpaid distribution does not necessarily postpone the beneficiary’s tax liability. An adult resident beneficiary can generally be assessed on their share of trust net income even when the cash remains in the trust. Trustee assessments can arise in other circumstances, including where income has not been effectively appointed.
We therefore consider tax and liquidity together. Allocating income to a beneficiary without planning how their tax will be funded can create an avoidable cash-flow problem.
We distinguish trust income from taxable net income
The amount available for distribution under a deed is not automatically the same as taxable net income.
Differences can arise from depreciation adjustments, capital gains, non-deductible expenses, franking credits and timing differences. We reconcile accounting profit, income of the trust estate and taxable net income before finalising beneficiary disclosures.
For example, a trust may record an accounting expense that is not immediately deductible. That adjustment can increase taxable net income without increasing the cash available for distribution. We explain the resulting beneficiary tax position rather than assuming the accounting distribution equals the taxable amount.
For trust tax submission in Australia, this reconciliation is essential to matching the trustee’s decisions with the return. It also helps us identify whether apparent profitability is translating into usable cash.
How we manage trust tax submission Australia-wide
Once we understand the deed and distribution position, we build the return from reconciled evidence. We do not rely solely on bank transactions, pre-filled information or the previous year’s treatment.
| Review area | What we reconcile | Why it matters |
|---|---|---|
| Business income | Sales records, bank receipts, debtor movements and relevant BAS figures | Identifies omissions, duplication and timing differences |
| Investment income | Interest, dividends, franking credits and investment tax statements | Supports accurate income classification and beneficiary reporting |
| Property | Rental statements, interest, repairs, capital expenditure and disposal records | Separates deductible expenses from capital costs |
| Capital gains | Acquisition costs, disposal proceeds, ownership periods and relevant adjustments | Supports the calculation and treatment of gains |
| Beneficiary accounts | Resolutions, entitlements, payments and amounts retained | Connects legal entitlements with accounting records |
| Deductions and losses | Supporting evidence, tax adjustments and applicable loss tests | Prevents unsupported deductions or unavailable losses being claimed |
We investigate differences rather than forcing the accounts to match an expected result. For example, BAS sales and income tax revenue may differ legitimately, but we should be able to explain why.
Our trust accounting services bring these financial records and trust-specific reviews together. The objective is a return supported by a clear audit trail, with figures that also support management decisions.
We review arrangements that need more than routine processing
Beneficiary distributions and section 100A
We examine arrangements where one beneficiary is made entitled to income but another person receives the economic benefit.
Section 100A of the Income Tax Assessment Act 1936 can apply to certain reimbursement agreements. Its operation depends on the facts, including the arrangement, tax-reduction purpose and relevant exceptions.
An adult child receiving a distribution while funds are redirected to parents warrants careful review. A family relationship alone does not establish that an arrangement falls within the ordinary family or commercial dealing exception.
We assess the underlying conduct, not just the resolution’s wording. For trust tax submission in Australia, documenting the actual use of funds is an important part of supporting the reported treatment.
Company beneficiaries, loans and trust losses
Where a company is a beneficiary, we separately review unpaid entitlements, loans, subsequent payments and potential Division 7A implications. We apply the law and relevant ATO guidance to the particular arrangement rather than assuming every unpaid balance has identical treatment.
We also check whether trust losses are available for use. A trust cannot simply distribute its tax losses to beneficiaries. Carry-forward deductions depend on the applicable trust loss rules.
A family trust election may be relevant, but it is not a routine administrative choice. We consider its restrictions and potential family trust distribution tax consequences before recommending one.
These reviews help us avoid a narrow focus on the current year’s tax saving at the expense of future flexibility.
We confirm the trust’s actual lodgement deadline
For a standard 30 June year-end, the usual self-lodgement deadline is 31 October following the income year, subject to applicable ATO rules. Where that date falls on a weekend or public holiday, the next business day generally applies.
For the year ended 30 June 2026, 31 October 2026 falls on a Saturday. The ordinary self-lodgement deadline therefore moves to Monday 2 November 2026. We still verify the trust’s recorded due date and circumstances rather than relying on a general calendar.
Registered tax agent lodgement programs can provide later dates for eligible clients. Those dates are not automatic and can be affected by lodgement history or specific ATO requirements. We recommend engaging us promptly and confirming eligibility, rather than assuming a last-minute appointment creates an extension.
We also distinguish the return’s lodgement deadline from payment deadlines for the trustee and beneficiaries.
If an earlier return remains outstanding, we establish the missing years, obtain records and assess penalties or interest. We then consider whether an extension, payment arrangement or remission request is appropriate. Delaying further rarely improves the position.
Timely trust tax submission in Australia depends on managing these obligations separately, with clear responsibility for each action.
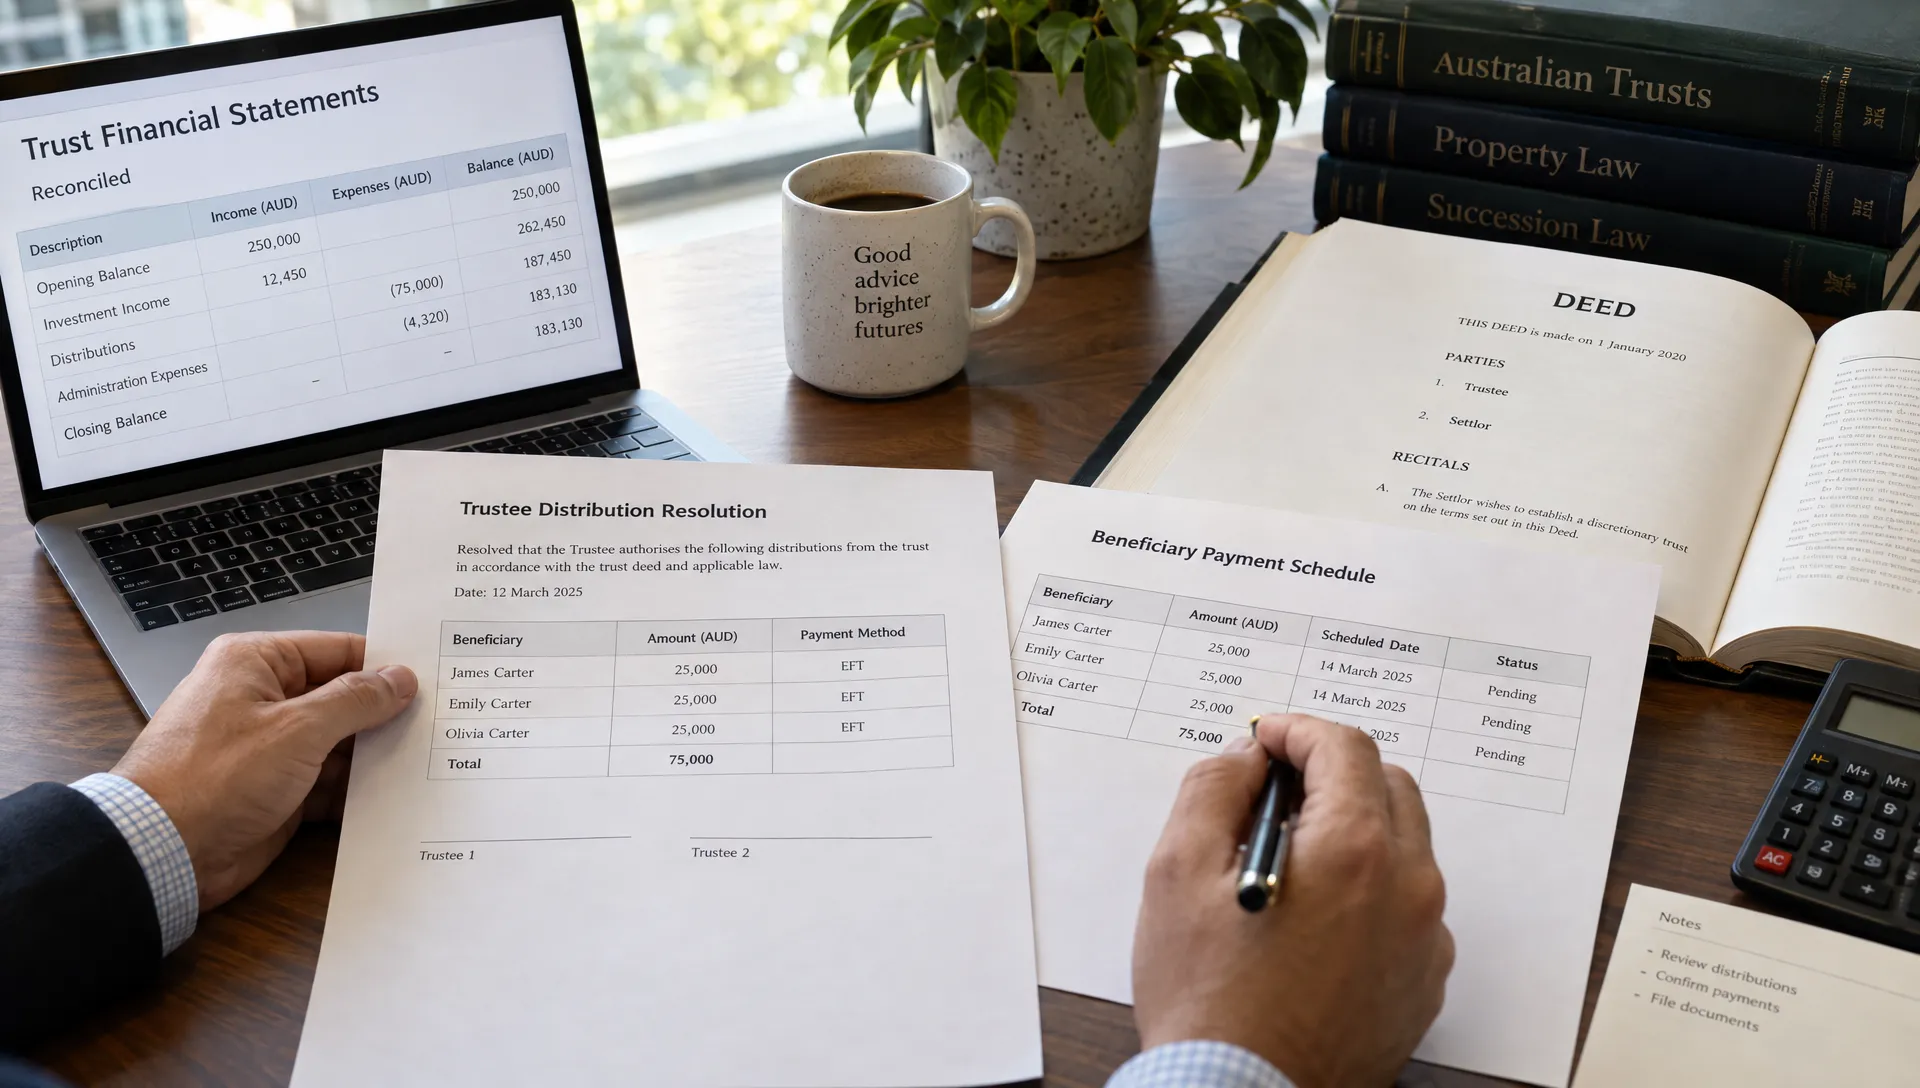
We use automation to improve control, not replace judgement
Digital transformation is valuable when it makes the evidence more consistent and exceptions easier to identify.
Our AI-driven approach supports faster processing, reduced manual rekeying and greater financial visibility. We design workflows around the client’s records and identify where transaction matching, document capture and reconciliation rules can improve accuracy.
We retain professional review over matters that require legal and tax judgement. Software cannot establish whether a trustee validly exercised a power under the deed simply because a journal entry exists. Nor does an automatically categorised payment prove deductibility.
We also apply access controls and secure document-sharing practices because trust records contain sensitive TFNs, beneficiary details and financial information.
For trust tax submission in Australia, the strongest use of automation is to surface discrepancies earlier. A beneficiary account that changes unexpectedly or an unreconciled investment statement should prompt review before lodgement, not after an ATO enquiry.
We turn the completed return into strategic advice
The return provides a structured view of profitability, distributions and tax exposure. We use that information to inform decisions for the next financial year.
For a trading trust, we may examine working capital, debt servicing and the cash needed to fund beneficiary tax liabilities. For an investment trust, we consider income concentration, disposal timing and the consequences of future acquisitions.
We also assess whether the current structure continues to suit the business. A trust may remain appropriate, but changing ownership plans, external investment or succession objectives can justify a broader review. We do not recommend restructuring solely because it appears to reduce one year’s tax.
Our virtual CFO and strategic advisory work connects these decisions with forecasts and management reporting. Reconciled accounts become a foundation for corporate growth rather than an annual compliance exercise.
Frequently asked questions
When can we lodge a trust tax return for the year ended 30 June 2026? We can prepare and lodge after the income year ends once the necessary records and applicable lodgement software are available. We wait for complete investment statements, reconciliations and distribution evidence rather than submitting incomplete figures to lodge earlier.
Can a trustee lodge a trust return through myTax? We distinguish the individual myTax service from trust return lodgement. Trust returns are not lodged through an individual’s myTax account. We use professional tax lodgement software and confirm the relevant authority to act.
Does distributing all income mean the trust has no tax obligations? No. We still assess the trust’s return obligations, beneficiary disclosures and any trustee liability. The effectiveness of the distribution and the beneficiary’s circumstances matter. Distributing cash alone does not establish the correct tax treatment.
What happens if a trust misses its lodgement deadline? We check outstanding obligations and arrange lodgement as soon as practicable. Failure-to-lodge penalties may apply, and unpaid tax can attract interest. We assess any grounds for relief separately; engaging an adviser does not automatically remove penalties.
Will a trust distribution produce a tax refund? We cannot determine that from the distribution alone. The outcome depends on taxable income, available credits, instalments, residency and other circumstances. Our trust tax submission in Australia includes coordinating beneficiary information so the final assessments are consistent.
Next steps: arrange a trust tax review
We recommend bringing the current deed and amendments, prior returns, distribution resolutions and year-to-date accounts to an initial consultation. We can then identify the immediate lodgement requirements and any decisions that need attention before the next 30 June.
At Perfect Accounting & Tax Services, we bring 25 years of professional experience to accounting, tax and strategic advisory. Our integrated team supports clients across Australia, including Adelaide, Sydney and Melbourne.
Contact our team for a consultation to review the trust’s tax position and discuss automated accounting workflows that strengthen accuracy, financial visibility and planning.