We price business tax filing services by assessing the entity, the condition of its records, the technical issues involved and the work included in the engagement. A return prepared from reconciled accounts requires different work from one involving overdue BAS, shareholder loans or incomplete property records.
Our starting point is to separate the professional fee from the tax payable. We then distinguish annual lodgement from bookkeeping corrections, specialist advice and ongoing financial oversight. That separation makes an estimate easier to evaluate and helps prevent a seemingly inexpensive return from becoming an open-ended assignment.
What a useful fee estimate should cover
We would not treat “business tax return” as a complete description of an engagement. We first clarify whether the proposed work includes financial statements, tax calculations, preparation, review and lodgement. We also identify the records and explanations needed from the business.
Where bookkeeping, BAS corrections or tax planning are necessary, we assess those separately rather than leave their treatment ambiguous. The estimate should state whether GST is included, which entities it covers and what happens if additional issues emerge.
We do not provide an unsupported national price range in this guide. Instead, we explain the factors behind a meaningful quote and identify the published bookkeeping rate that may be relevant when records need attention.
How we scope business tax filing services
Entity structure and reporting obligations
We begin with the legal structure because it determines the return and associated reporting work. Turnover alone does not establish complexity: a relatively small company with director loans can require more technical attention than a larger sole trader with clean records.
| Structure | Annual income tax work we assess | Issues that can expand the scope |
|---|---|---|
| Sole trader | Business income and deductions within the individual return | Personal services income, mixed-use expenses and other personal income |
| Company | Separate company return and supporting financial information | Shareholder loans, losses, ownership changes and related-party transactions |
| Partnership | Partnership return and allocation of net income or loss | Partner changes, allocations and reconciliation with partners’ returns |
| Trust | Trust return and supporting distribution information | Trustee resolutions, beneficiary entitlements and related-party arrangements |
We also establish whether the assignment involves one entity or a group. A company, family trust and investment property portfolio may require coordinated work, even when each return is lodged separately.
Record quality and reconciliation work
When scoping business tax filing services, we assess whether the accounting records support the proposed return. A bank feed is useful, but it does not establish that every transaction has been classified correctly or that all liabilities are recorded.
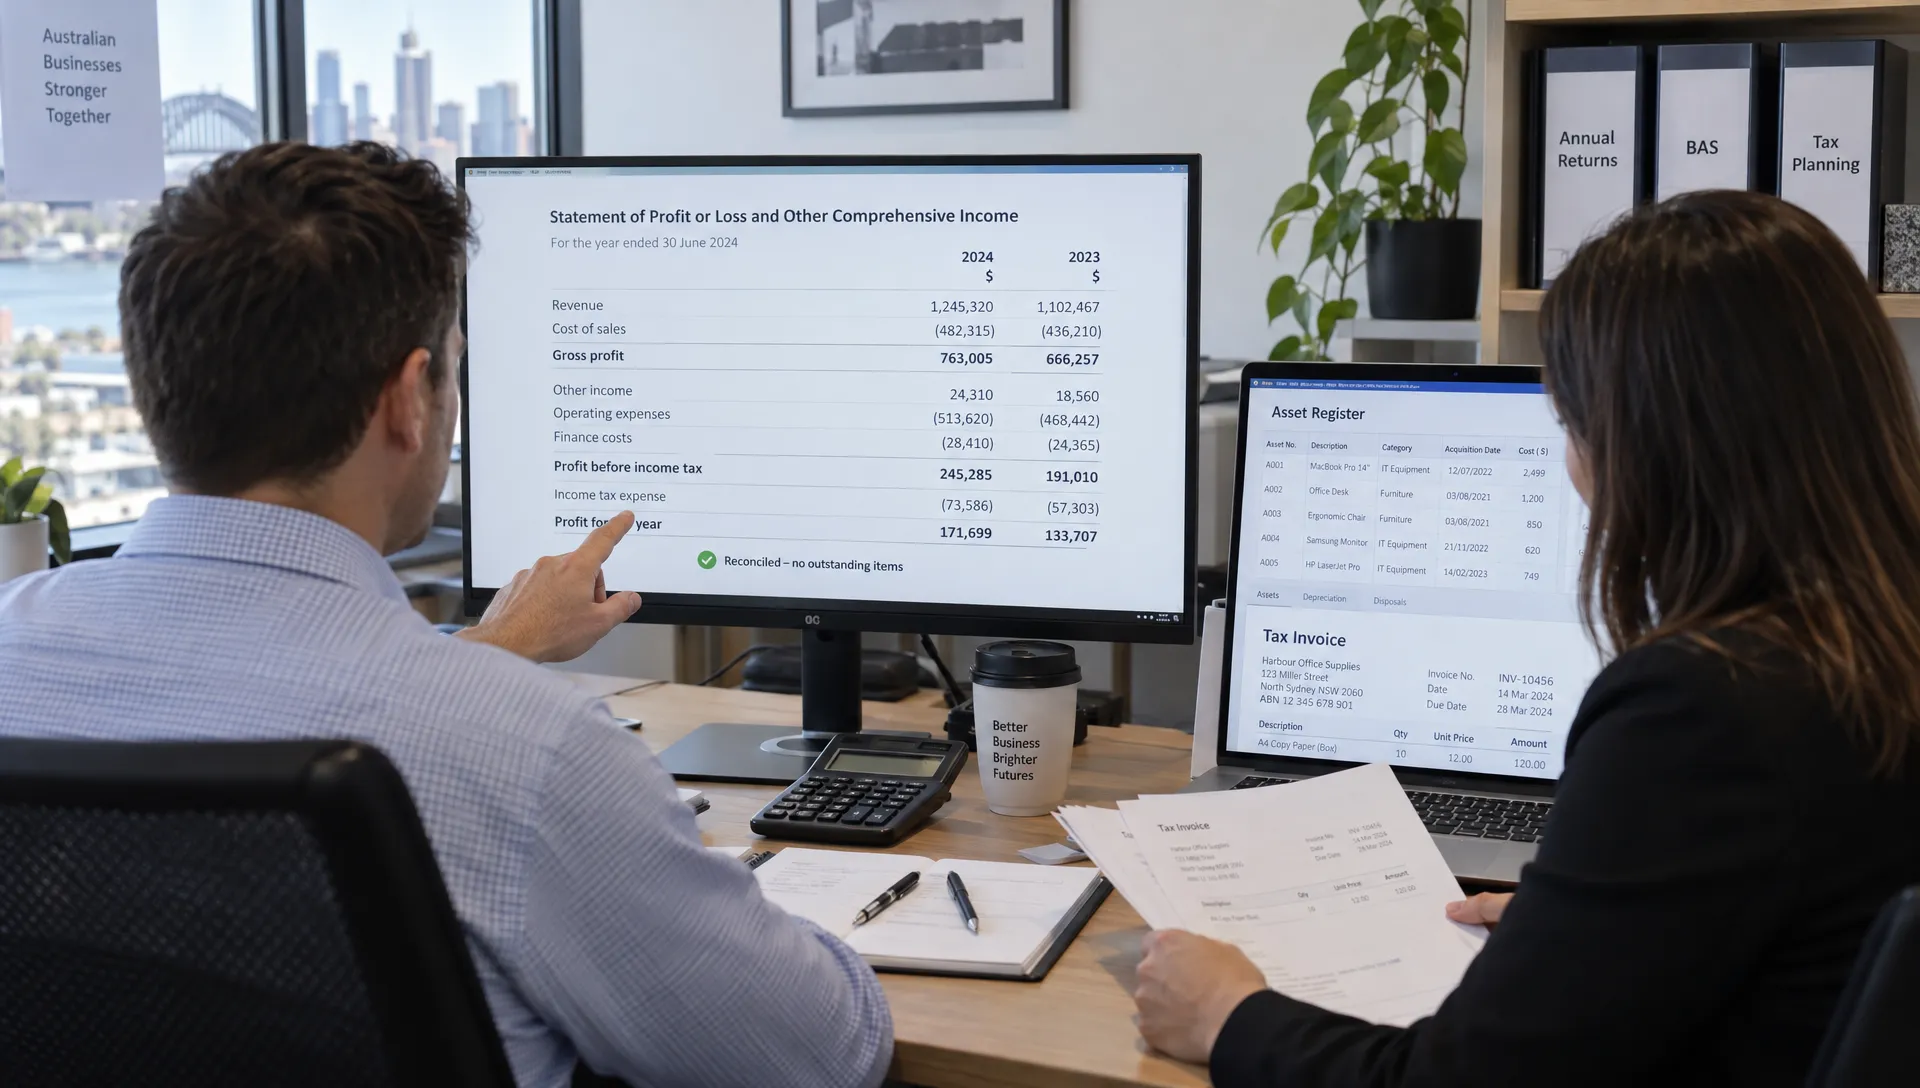
We look for reconciled bank and credit card accounts, reliable debtor and creditor balances, an asset register and consistency between payroll records, Superannuation obligations and the general ledger. We also check whether BAS figures reconcile with annual revenue and GST accounts.
If those foundations are incomplete, we need to identify the correction work before estimating the return preparation effort. We can assess a representative sample of records to distinguish routine processing from a broader clean-up assignment.
Technical issues and supporting evidence
We allow for professional judgement where transactions cannot safely be processed using standard categories. Common examples include Division 7A shareholder loans, capital gains, foreign income, business restructures and questions about whether expenditure is deductible or capital.
Property-related expenditure illustrates the distinction. The remediation and demolition services described by Banner Environmental Services show how specialist projects can involve several different types of work. That overseas provider is an illustration of service scope, not Australian tax guidance.
For Australian assets, we examine the actual work, the property's history and the relevant rules. We distinguish repairs from improvements and initial repairs, while checking whether specific environmental protection provisions may apply.
We therefore scope business tax filing services around the evidence and analysis required, not simply the number of invoices. A detailed contractor statement can reduce uncertainty more effectively than a broad description such as “property maintenance”.
Where our published bookkeeping rate fits
Our published bookkeeping pricing starts at $55 per hour, with pricing subject to the work involved and transaction volume. We distinguish that starting rate from a quoted fee for preparing and lodging a business tax return.
We would confirm the applicable rate, GST treatment and estimated scope before relying on it for a particular engagement. A bookkeeping rate does not establish how many hours a clean-up will require, nor does it describe the cost of specialist tax advice.
For example, we would assess a year of unreconciled transactions differently from a small number of incorrectly coded asset purchases. The first may require extensive processing; the second may involve fewer entries but more technical review.
When estimating business tax filing services, we separate those tasks so the business can understand what is driving the total. We also assess whether correcting the underlying workflow will prevent the same cost from recurring next year.
How automation changes the workload
Our AI-driven processes support faster routine processing, more consistent classification and earlier identification of exceptions. We use automation to reduce repetitive handling while retaining professional review over tax-sensitive decisions.
What digital processes can improve
We can use automated workflows to bring transaction records together, identify missing information and flag entries requiring attention. Connected accounting records also support more current financial visibility, rather than leaving important discrepancies undiscovered until year-end.
We do not assume that automation makes every engagement cheaper by a fixed percentage. Its value depends on the quality of the source information, the existing systems and the complexity of the transactions. System setup or historical corrections may require initial work before recurring processing becomes more efficient.
What still needs professional judgement
For business tax filing services, automation does not replace decisions about deductibility, related-party transactions, residency or the treatment of a major asset disposal. We still need evidence, context and review.
We also treat TFNs, payroll details and financial records as sensitive information. Any proposed digital workflow needs appropriate access controls and an agreed method for sharing documents. We would not encourage uploading confidential client information into an unapproved public AI tool.
Choosing between fixed fees, hourly work and ongoing support
We assess the pricing approach against the certainty of the workload. No single model is suitable for every engagement.
| Pricing approach | Where we would consider it | What we need to clarify |
|---|---|---|
| Fixed fee | A defined return with sufficiently complete records | Deliverables, assumptions, exclusions and variation triggers |
| Hourly work | Uncertain historical corrections or investigative work | Applicable rates, progress reporting and review points |
| Recurring package | Ongoing bookkeeping, compliance and advisory support | Included services, entity coverage and work outside the package |
We would not assume that monthly payments include the annual income tax return, BAS, payroll, FBT or tax planning. Each obligation needs to be named in the scope.
A fixed fee for business tax filing services is most useful when both parties understand its boundaries. Where the records are incomplete, an initial diagnostic assessment can provide a sounder basis for a subsequent estimate than an artificially precise figure supplied before review.
We would also distinguish the price of an ongoing service from its payment schedule. Spreading a fee across monthly instalments does not, by itself, create a year-round advisory engagement.
Why similar businesses can receive different estimates
We can illustrate the pricing logic without inventing a fee schedule. Consider two Australian consulting companies with similar revenue.
Company A: reconciled records and limited complexity
We receive reconciled accounts, supporting invoices, a maintained asset register and clear records of director transactions. Payroll reporting and BAS balances agree with the ledger. We can concentrate on reviewing the accounts, making tax adjustments and preparing the return.
The work still requires professional review. Clean records reduce avoidable processing, but they do not eliminate tax analysis or the need to verify significant balances.
Company B: unresolved accounts and related-party issues
We receive unreconciled accounts with private expenses mixed into business transactions, missing asset documentation and amounts owed by a shareholder. We first need to establish reliable balances and assess the related-party position.
We would expect business tax filing services for Company B to involve a broader scope, despite the similar turnover. Any necessary BAS corrections or specialist advice also need to be identified rather than silently absorbed into an annual-return description.
Our comparison is about workload and risk, not a claim that one industry or revenue band always attracts a particular fee. The condition and complexity of the evidence remain central.
Comparing quotes without overlooking exclusions
We recommend comparing written scopes before comparing totals. We would check the following points:
- Entities and periods: We need clarity about which companies, trusts, partnerships or individuals are included and which financial years are covered.
- Preparation and corrections: We distinguish financial statements, return preparation and lodgement from bookkeeping repairs or amended BAS.
- Advice and follow-up: We identify whether tax planning, ATO correspondence and post-lodgement questions are included or separately scoped.
- Commercial terms: We confirm GST treatment, payment terms and the process for approving additional work.
We also recommend checking the practitioner's registration through the Tax Practitioners Board public register. A professional-looking proposal does not replace verification of the registration relevant to the work.
When comparing business tax filing services, we focus on the total cost of achieving a reliable outcome. A lower initial fee can be poor value if essential preparation, review or follow-up falls outside the quoted scope.
We would not promise a particular refund or tax reduction to justify a fee. The defensible outcome depends on the law, the facts and the available evidence.
Turning compliance work into financial oversight
We regard accurate bookkeeping and tax compliance as foundations for Strategic Advisory and Corporate Growth. Once the records are reliable, we can use them to assess cash requirements, forecast tax liabilities and examine the financial implications of hiring, investment or expansion.
That does not mean every annual return needs a virtual CFO engagement. We distinguish mandatory compliance from optional advisory work and assess where additional analysis would help a business decision.
Our approach to tax-efficient accounting and cash-flow management connects these activities without treating them as interchangeable. A tax return reports a completed period; a forecast helps management decide what to do next.
We therefore assess business tax filing services as one part of financial health, while keeping the scope and price of forward-looking advice visible.
Frequently asked questions
Can we lodge our own business tax return? We recognise that businesses can self-lodge where an appropriate ATO lodgement method is available. We recommend assessing the records, entity obligations and technical issues first. Engaging an adviser does not remove the business's responsibility for providing complete and accurate information.
Does a loss-making business still need to lodge? We do not treat a trading loss as an automatic exemption from lodgement. We check the entity's circumstances and ATO obligations, including whether a return or another notification is required. A carried-forward loss may also need supporting records and eligibility review.
Does the sole trader 80% rule determine the filing fee? We do not use it as a pricing threshold. Under the ATO's personal services income rules, the 80% rule can affect access to certain personal services business tests. It is not a tax-free threshold or a general requirement to have multiple clients.
Are tax return preparation fees deductible? We assess whether eligible fees qualify as costs of managing tax affairs and confirm the relevant timing. We distinguish that treatment from legal, capital or other advisory expenditure, which may follow different rules.
Next steps: request a scoped consultation
We can provide a more useful estimate when we understand the entity structure, outstanding lodgements, accounting system and condition of the records. Recent financial statements, the prior-year return and details of significant transactions help establish that starting point.
With 25 years of professional experience, our team supports clients across Australia through integrated accounting, tax and advisory capabilities in Adelaide, Sydney and Melbourne. We combine technical review with AI-driven workflows to reduce repetitive work and improve financial visibility.
To discuss business tax filing services, contact Perfect Accounting & Tax Services for a consultation. We can assess the required scope, identify any preliminary correction work and explain where automated accounting workflows could improve the next reporting cycle.