An SMSF can give us greater control over how retirement savings are invested, but control comes with legal responsibility, ongoing costs and investment risk. Professional tax return support addresses only one part of that responsibility. The more important question is whether the structure improves retirement outcomes after allowing for administration, diversification and the time required to govern it properly.
We assess SMSFs as part of a broader financial strategy, not as an automatic upgrade from an existing superannuation fund. For business owners, directors and high-net-worth individuals, suitability depends on what the fund needs to achieve and whether its members can sustain the obligations.
What is an SMSF?
A self-managed superannuation fund is a super fund established to provide retirement benefits to its members. Unlike an industry or retail fund, its members generally also act as individual trustees or directors of a corporate trustee. An SMSF can have up to six members, subject to eligibility and structural requirements.
The ATO regulates SMSFs. Trustees remain legally responsible for the fund even when accountants, administrators, financial advisers and investment managers assist them. We treat this distinction as central to any suitability assessment: outsourcing work does not outsource accountability.
Our SMSF structure and setup overview explains the establishment process. Here, we focus on whether taking on that structure is worthwhile.
An SMSF is also a separate financial entity. Its assets are not available to fund business expansion, meet personal expenses or provide informal loans to members. Good tax return support must therefore sit within a wider framework of trustee governance, investment oversight and clear financial separation.
Assess the economics before comparing investment options
We start with total annual costs rather than a headline establishment fee. Relevant expenses can include accounting, administration, independent audit, the ATO supervisory levy, investment fees and advice. Corporate trustees also have company-related obligations and costs. Property, borrowing arrangements and pension accounts can add complexity.
There is no universal balance at which an SMSF becomes suitable. A larger balance may spread fixed costs more efficiently, but it does not resolve weak diversification, unsuitable investments or poor governance.
For illustration only, assume annual administration, accounting and audit costs total $4,000. Against a $400,000 balance, that represents 1% before investment fees, insurance and other expenses. Against $1 million, the same assumed costs represent 0.4%. These figures are arithmetic examples, not our fees, market averages or recommended minimum balances.
We compare that full cost with the existing fund's fees, investment options and insurance. We also include establishment and eventual wind-up costs, particularly where retirement, relocation or changing family circumstances could shorten the fund's life.
When comparing tax return support proposals, we look beyond lodgement. The engagement should make clear whether financial statements, reconciliations, audit coordination and technical queries are included or charged separately.
When an SMSF may fit, and when it may not
Control has value only when it supports a credible investment and retirement strategy. We would expect the proposed structure to solve an identifiable problem that the existing fund cannot address as effectively.
| Assessment area | Stronger basis for further investigation | Reason to pause |
|---|---|---|
| Investment purpose | A documented strategy requiring appropriate direct ownership or greater control | Establishing a fund because an investment promoter recommends it |
| Financial capacity | Costs remain proportionate and liquidity is adequate | Fees or loan repayments place pressure on available cash |
| Trustee capability | Members understand their duties and will review decisions | Members expect an accountant to assume legal responsibility |
| Diversification | Investments address concentration across the household's wealth | Retirement savings would largely duplicate existing business or property exposure |
| Member alignment | Members agree on risk, contributions and retirement timing | Different objectives could create disputes or forced asset sales |
Reliable tax return support helps implement the structure, but it cannot make an unsuitable investment strategy appropriate.
We also examine the protections being given up. SMSFs do not have the same statutory compensation arrangements for fraud or theft as eligible APRA-regulated funds. Existing life, total and permanent disability or income protection cover may also be affected when benefits are rolled over.
We recommend obtaining appropriately licensed financial advice before deciding to establish an SMSF or replace an existing superannuation product. ASIC's Moneysmart SMSF guidance provides a useful independent starting point.
Where tax return support fits into trustee responsibility
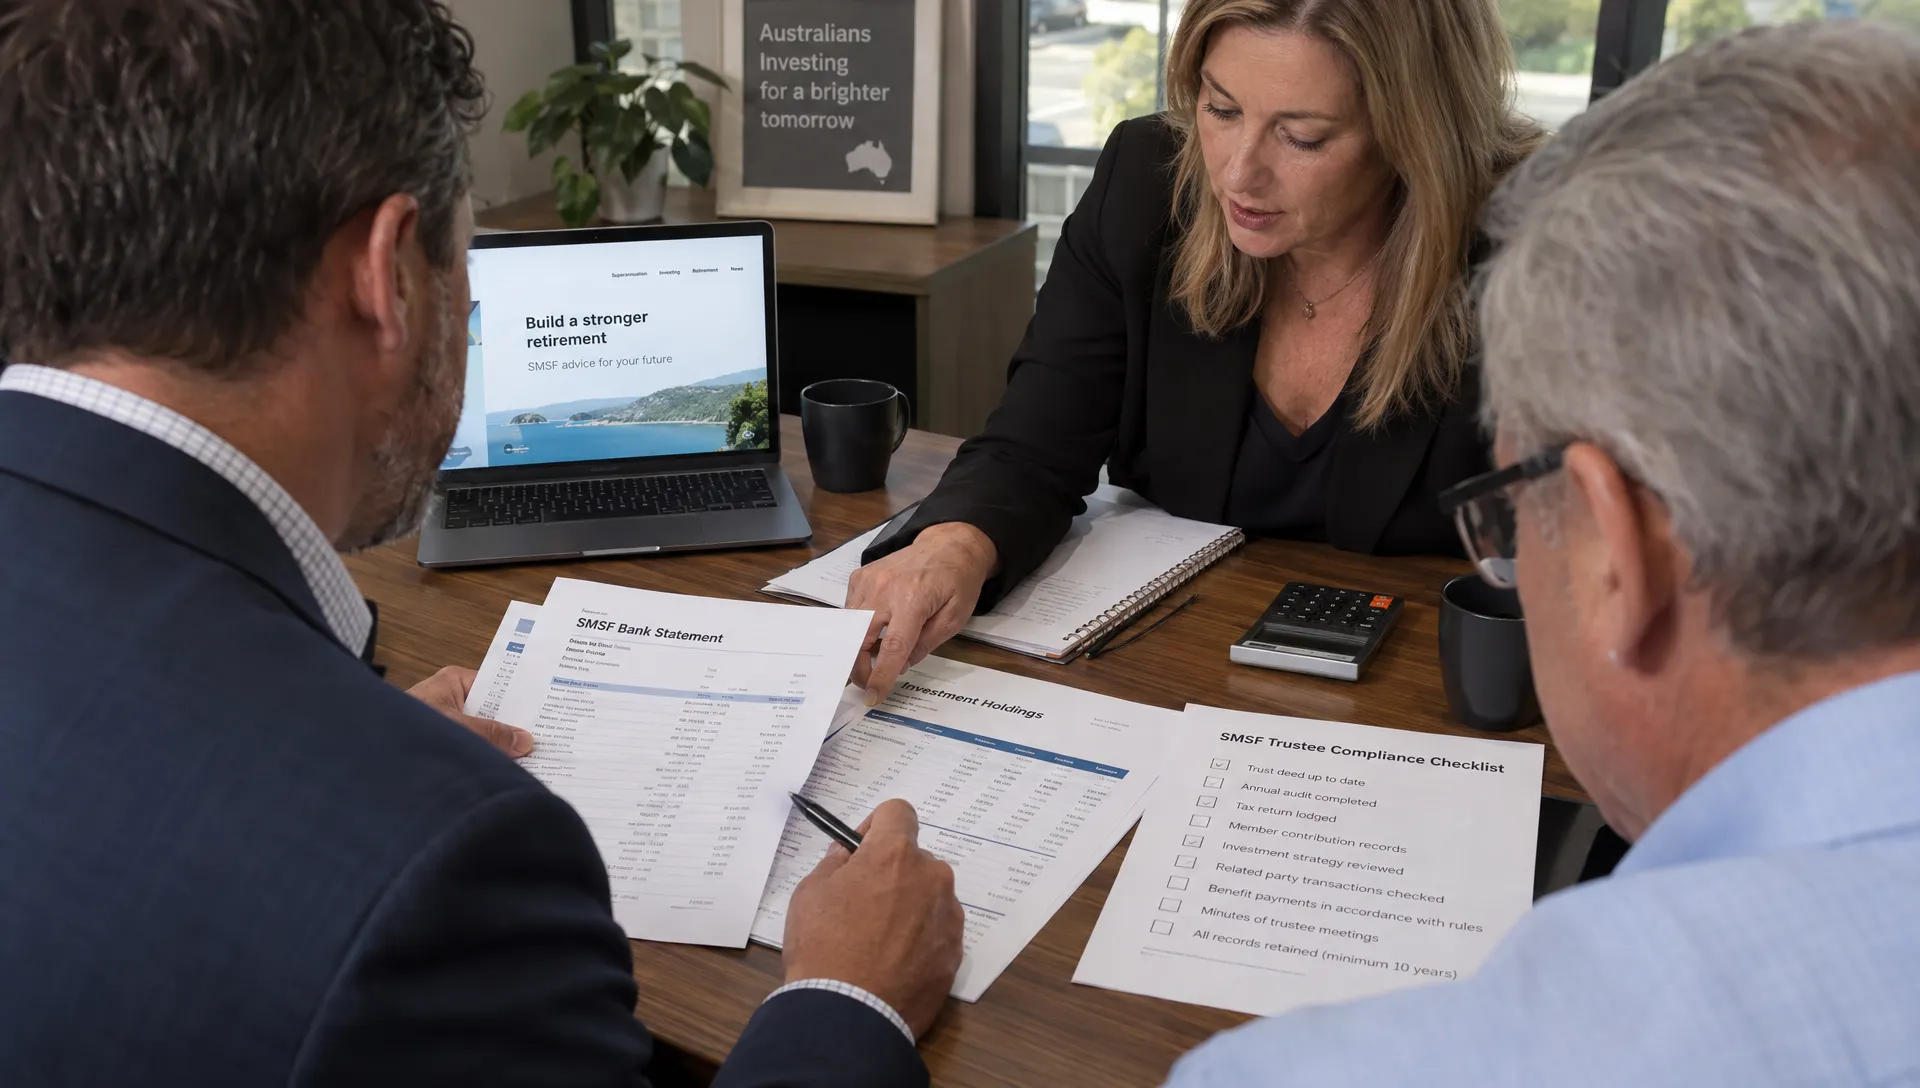
An operating SMSF generally needs annual financial statements, an independent audit and an SMSF annual return. That return is separate from members' individual tax returns and combines income tax reporting with regulatory information and member contribution reporting.
We build the accounting process around evidence: bank transactions, investment statements, contribution records, valuations and documentation supporting payments to members. An approved SMSF auditor must independently examine the fund each year, and the audit must be completed before the annual return is lodged.
Tax concessions depend on compliance
A complying SMSF generally pays 15% tax on taxable income in accumulation phase. Some eligible retirement-phase investment income may be exempt, subject to the applicable rules and limits. These concessions are not exclusive to SMSFs.
Contribution caps, pension payment requirements, related-party dealings and non-arm's-length income rules can materially change the outcome. We do not assume that moving assets into an SMSF automatically reduces tax.
We use the ATO's SMSF guidance alongside the fund's circumstances to identify the relevant obligations. Effective tax return support should reveal issues early enough to address them, rather than simply record problems after year-end.
Keep business strategy separate from retirement assets
For business owners, SMSF property investment can appear attractive, particularly where commercial premises are involved. However, the fund must satisfy the sole purpose test and applicable investment restrictions. It cannot operate as a reserve account for the trading business.
Business real property may, in specific circumstances, be acquired from or leased to a related party. The arrangement must satisfy the relevant rules, with market-value dealings and properly documented commercial terms. We assess the transaction before contracts are signed, alongside specialist legal and licensed financial advice where required.
Residential property generally cannot be acquired from a related party or used by members or related parties. A holiday stay is not made acceptable by paying rent to the fund.
Borrowing is also restricted. A limited recourse borrowing arrangement can be permitted, but its structure, documentation and cash-flow consequences require careful review before committing to a purchase.
We stress-test vacancies, repairs, interest costs and pension payments. A property may look sound on paper yet leave insufficient cash to pay benefits without selling at an unfavourable time. For a business owner whose personal wealth already depends on property and one trading business, adding similar exposure inside super can increase concentration risk.
Use automation to improve oversight, not replace judgement
We use AI-driven automation to streamline accounting workflows, with professional review remaining central to the process. Where suitable integrations and reliable source data are available, automation can reduce manual re-entry, improve processing speed and highlight inconsistencies for investigation.
For trustees, the strategic benefit is earlier visibility. More current records can support better decisions about cash reserves, upcoming expenses and the timing of transactions. However, a live bank balance is not a complete measure of fund performance. Property and other unlisted assets still require appropriate valuation evidence.
For the operating business, tools such as Dr. CRM's invoicing and task management platform can help centralise administration. We maintain the distinction between business workflow software and the separate accounting, evidence and reporting requirements of an Australian SMSF. Software suitability and data handling need their own assessment.
Our approach connects tax return support with year-round financial oversight rather than treating compliance as an isolated annual task. We still require supporting documents, controlled access and an audit trail for significant decisions.
For business clients, disciplined bookkeeping creates the foundation for strategic advisory and corporate growth. Within the SMSF, the same discipline serves a different objective: protecting retirement savings and supporting lawful benefit payments. Keeping those purposes distinct is essential.
Plan for retirement, incapacity and an eventual exit
We assess an SMSF over its expected life, not just its establishment year. A structure that works while all members are employed may become harder to manage when pensions commence, one member dies or another loses capacity.
The investment strategy must consider diversification, liquidity, liabilities and members' insurance needs. Trustees must also review it regularly and when circumstances change. Holding a single asset is not automatically prohibited, but the reasoning and risks require genuine consideration.
Succession planning should address trustee control, the trust deed and death benefit arrangements. We coordinate with legal advisers where required because superannuation does not automatically pass under a person's will.
We also review overseas relocation plans. An extended absence or changes to how the fund is controlled can affect its Australian residency status, with potentially serious tax consequences.
Continuity in tax return support matters during these transitions, but it is only one workstream. We also consider access to records, decision-making authority, asset liquidity and the practical cost of winding up. Establishing an SMSF without an exit plan can leave a surviving spouse or family member managing obligations they never intended to accept.
Frequently asked questions
Do we need a minimum balance to establish an SMSF? There is no legislated minimum opening balance. We assess whether expected costs, diversification and the proposed strategy justify the structure, rather than treating any balance as an automatic approval threshold.
Can an accountant decide whether an SMSF is right for us? We can explain accounting, tax and compliance implications within our scope. A personal recommendation to establish an SMSF or switch superannuation products generally requires appropriately licensed financial advice.
Can we manage an SMSF while running a business? It is possible, but we assess available time, financial capability and continuity arrangements. Engaging professionals reduces administration; it does not remove trustee responsibility.
Can an SMSF lend money to our business? Lending to or investing in a related business can breach strict superannuation rules. We recommend obtaining advice before any transfer, loan, guarantee or related-party arrangement is contemplated.
Next steps: assess suitability before establishing the fund
We recommend beginning with a documented comparison of the existing super fund and the proposed SMSF. The assessment should cover total costs, insurance, investment objectives, liquidity, trustee capability and exit arrangements.
Our team brings 25 years of professional experience to accounting, compliance and strategic advisory. We support clients across Australia through integrated service capabilities in Adelaide, Sydney and Melbourne, combining financial expertise with AI-driven workflow improvements.
Through our SMSF accounting and compliance services, we can help clarify the administration involved and scope appropriate tax return support. We distinguish that work from personal financial product advice and identify where specialist input is needed.
Contact our team for a consultation about SMSF compliance, suitability assessment inputs or our automated accounting workflows. We can help establish the financial evidence needed for an informed decision before commitments are made.
This article provides general information, not personal financial, investment or legal advice. Outcomes depend on individual circumstances and the law applying when a transaction occurs.