We use this guide to address the practical questions behind “filing tax return australia” after moving overseas: whether a return is required, which income remains taxable and how departure affects business interests and investment assets. The starting point is tax residency, not citizenship or the date of an international flight.
For business owners, company directors and investors, relocation can create several overlapping obligations. We separate personal tax reporting from company compliance, property taxation and overseas requirements so that annual lodgement supports a broader financial strategy.
Establish tax residency before preparing the return
We do not assume that moving overseas automatically ends Australian tax residency. Under the ATO’s residency framework, the relevant tests include the resides test, domicile test, 183-day test and Commonwealth superannuation test.
An overseas employment contract or foreign visa is evidence, but neither determines the outcome alone. We consider the nature and duration of the relocation, accommodation arrangements, family connections and continuing Australian ties.
For someone retaining an Australian domicile, establishing a permanent place of abode outside Australia can be particularly important. We also distinguish Australian domestic residency from any position arising under an applicable double tax agreement.
Spending fewer than 183 days in Australia does not, by itself, establish foreign residency.
Build a defensible departure timeline
Before filing a tax return in Australia, we assemble a timeline supported by travel records, employment agreements, accommodation documents and family relocation dates. We also review whether an Australian home remains available for personal use.
These records help establish whether residency continued throughout the financial year or ceased on a particular date. We retain the reasoning with the return preparation file rather than relying on an address change in ATO records.
Where both countries regard an individual as resident, we examine the relevant treaty. Its residency provisions and allocation of taxing rights can affect the analysis, but a treaty does not automatically eliminate Australian reporting obligations.
Identify which income remains reportable
Australia’s income year runs from 1 July to 30 June. We divide income according to the residency position and the applicable taxing rules, rather than simply separating Australian and overseas bank deposits.
| Income or receipt | Treatment we examine after relocation |
|---|---|
| Salary earned while an Australian tax resident | Generally included in worldwide assessable income, subject to applicable exemptions and treaty rules |
| Overseas employment income after becoming a foreign resident | Generally outside Australian income tax where it is foreign-sourced, subject to the circumstances |
| Rent from Australian property | Generally remains assessable in Australia, with eligible deductions considered |
| Australian interest and unfranked dividends | Often subject to non-resident withholding arrangements rather than ordinary assessment |
| Gains involving Australian real property | Generally remain within Australia’s CGT rules |
| Sole-trader or consulting income | Requires a source analysis that considers where activities occur and how the income is earned |
When filing a tax return in Australia from overseas, we do not treat an Australian customer or Australian bank account as conclusive evidence of income source. This is particularly important for consultants and digital businesses performing work offshore.
Separate resident and foreign-resident periods
For a part-year resident, we generally assess worldwide income during the resident period and relevant Australian-sourced income during the foreign-resident period. Temporary-resident concessions and other exceptions may alter that treatment.
For example, assume residency genuinely ceased on 1 December. We would examine worldwide income up to that point, then identify income Australia can tax for the remainder of the financial year. Australian rental income would ordinarily continue to require attention.
We calculate the part-year tax-free threshold rather than automatically dividing the full threshold by the months spent in Australia. Full-year foreign residents generally receive no tax-free threshold and are not liable for the Medicare levy; part-year calculations require separate review.
Where the same income is taxed in both countries, we consider treaty relief and any available foreign income tax offset. Different tax years and payment dates can complicate the calculation.
Review departure CGT before assets are sold
Filing a tax return in Australia after ceasing residency can involve capital gains tax even where no asset has been sold.
For individuals, CGT event I1 can trigger a deemed disposal of assets that are not taxable Australian property. Subject to exceptions, affected assets may include shares and overseas investments. We establish the market value at the residency cessation date and reconcile the relevant cost bases.
An individual may choose to disregard the relevant departure gains and losses. That choice generally brings the affected assets into Australia’s CGT net until a later relevant CGT event or the resumption of Australian residency.
We model both approaches before recommending a position. Deferring a departure gain is not necessarily a permanent tax saving, particularly if the destination country uses different cost-base rules or does not provide matching relief.
Australian property needs a separate assessment
Australian real property generally remains taxable Australian property after departure. We therefore review rental arrangements, ownership records and any planned sale independently of the departure CGT calculation.
The ordinary six-year absence rule does not guarantee a main residence exemption for a foreign resident. A disposal while foreign resident can prevent access to the exemption unless a specific exception applies. CGT discount entitlement can also be restricted for periods of foreign residency.
For Australian real property contracts entered into from 1 January 2025, foreign resident capital gains withholding generally applies at 15%, with no property-value threshold. We distinguish this withholding from the final CGT liability: it is a tax collection mechanism, not the final calculation.
The ATO’s foreign resident capital gains withholding guidance explains clearance certificates and variations. We assess these requirements before settlement, when there is still time to address cash-flow consequences.
Keep personal relocation separate from business compliance
We approach filing a tax return in Australia as one part of the relocation project, not as a substitute for reviewing the business structure.
An Australian-incorporated company remains Australian resident under domestic law even if its owner moves overseas. Offshore management or operations can nevertheless create foreign tax exposure, dual-residency questions or a permanent establishment issue. We coordinate the Australian analysis with an adviser in the destination country where required.
For sole traders, we examine where services are performed, how contracts operate and whether an Australian business continues. For trusts, we review trustee residency, management arrangements and distributions to non-resident beneficiaries.
Personal departure does not automatically cancel an ABN, end GST registration or remove BAS, payroll, superannuation and FBT obligations. We assess each obligation against the continuing activities and arrangements.
Accurate bookkeeping provides the foundation for strategic advisory and corporate growth. It allows us to distinguish a genuine cessation of Australian operations from a business that continues to trade across borders.
Check SMSFs, superannuation and study loans
For SMSF trustees, we review the fund’s Australian residency requirements before changing management arrangements. Central management and control and active-member rules can be affected by members or trustees living overseas. A temporary absence concession is not a blanket solution.
Moving overseas also does not ordinarily allow Australian citizens or permanent residents to withdraw preserved superannuation. Departing Australia superannuation payments are a separate regime for eligible temporary residents.
When filing a tax return in Australia, we also check HELP and other relevant study or training loan obligations. Overseas borrowers may need to notify the ATO and report worldwide income even when no Australian income tax return is otherwise required.
Our checklist for “filing tax return australia” from overseas
Assemble one complete digital evidence file
We recommend establishing a secure records file before preparing the departure-year return. The objective is to reconcile the residency position with income, asset movements and continuing Australian obligations.
Our core evidence checklist includes:
- Travel dates, visa details and overseas employment or business agreements.
- Australian and overseas accommodation records supporting the residency assessment.
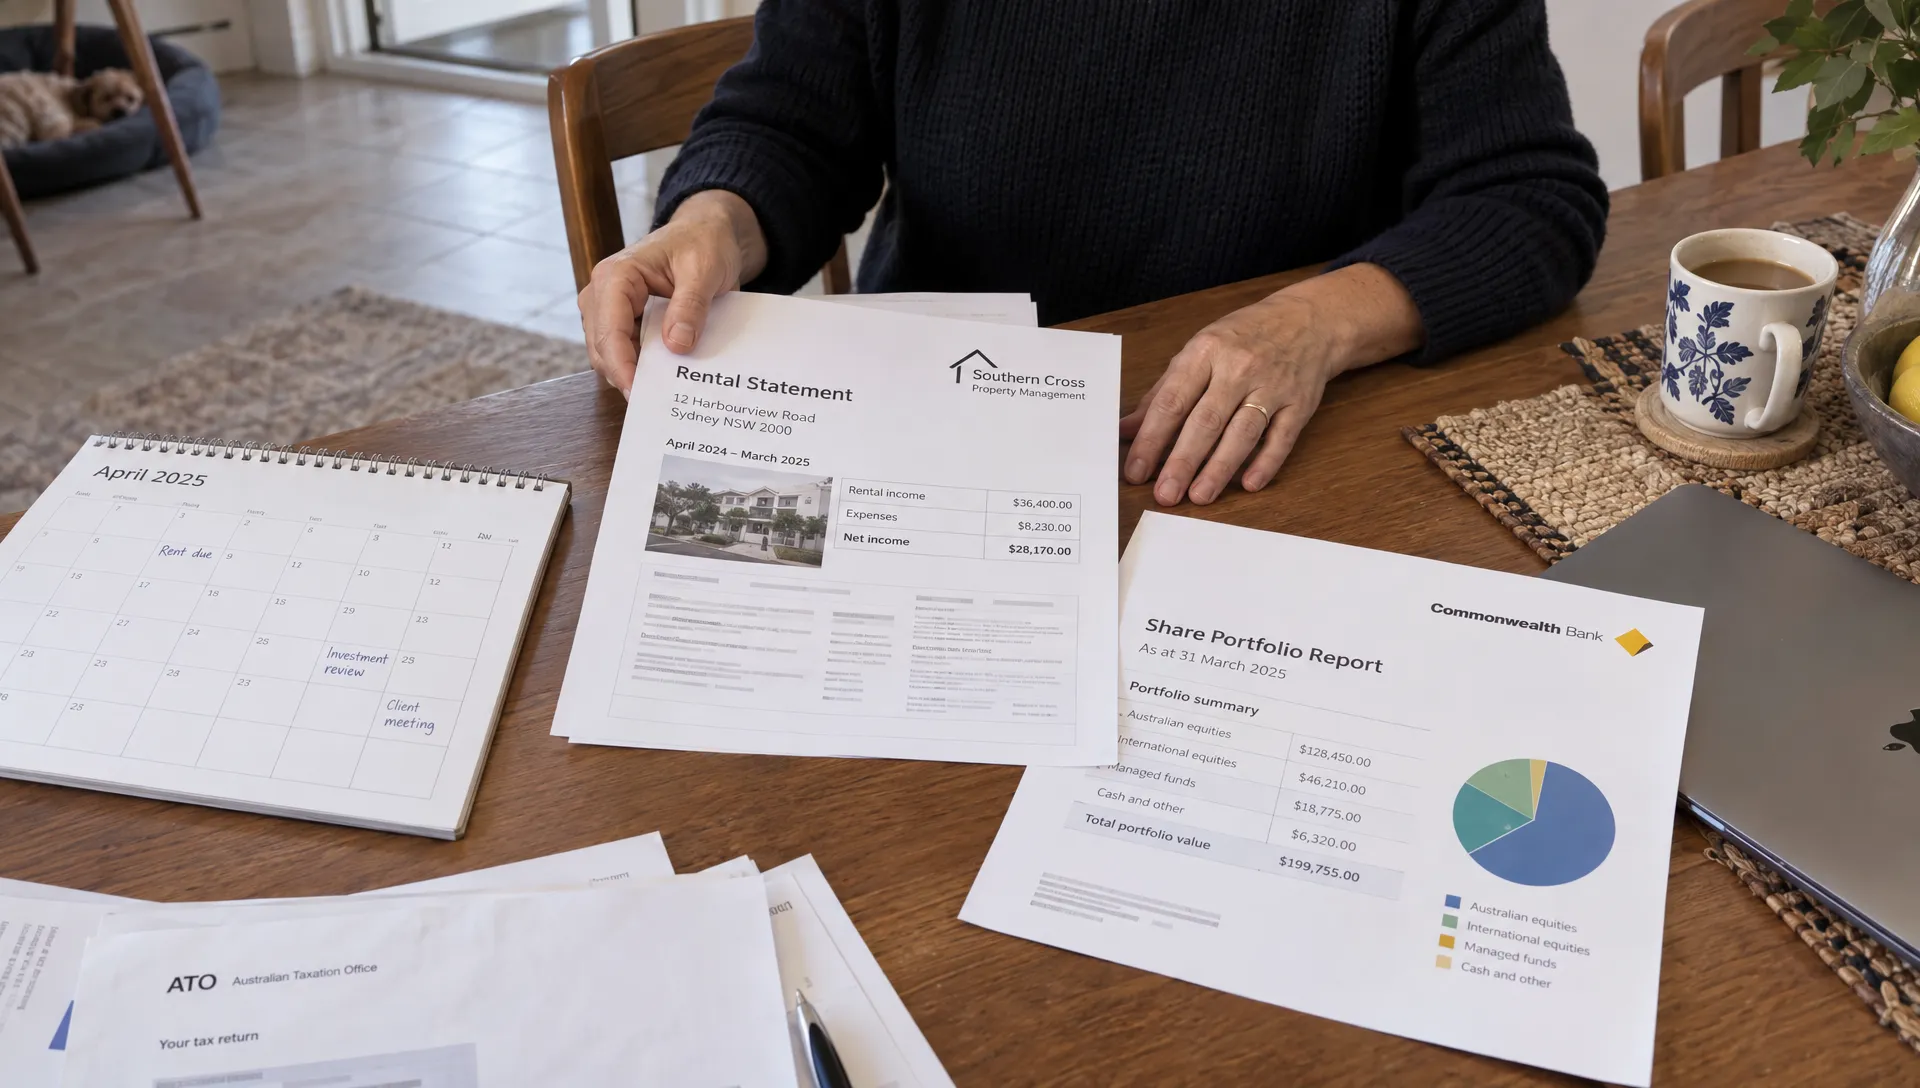
- Income statements, investment reports and relevant foreign tax assessments.
- Rental statements, property expenses and borrowing records.
- Asset acquisition documents and departure-date valuations where required.
- Company, trust and SMSF records relevant to continuing compliance.
We record foreign-currency conversion methods consistently and distinguish transaction dates from payment dates. We also retain records for the applicable statutory periods, recognising that CGT documentation may need to be kept considerably longer than ordinary annual expense records.
Our Australian tax return process explains the wider reconciliation and review stages. For an overseas departure, we add a specific residency and cross-border asset review.
Confirm the correct return and lodgement deadline
For individuals filing a tax return in Australia themselves, the usual deadline is 31 October following the end of the income year. Weekend and public holiday rules can affect the applicable date.
A registered tax agent may have a later lodgement date under the agent programme. Eligibility depends on the circumstances, including prior lodgement history. We recommend confirming eligibility before 31 October rather than assuming an extension applies.
We also distinguish the individual return from any separate company, trust or SMSF return. One person’s relocation does not merge these reporting obligations.
If no return is required, a non-lodgment advice may be appropriate. We confirm that position rather than treating permanent departure as permission to stop reporting. Early lodgement is available only in limited departure circumstances and is not the default approach.
Maintain access and plan for payment
We check overseas contact details, ATO online access and authorised representation before lodgement. We recommend secure document exchange and never require clients to share their myGov password.
The payment deadline is separate from the lodgement deadline. We review the assessment and any applicable payment arrangements, then consider whether ongoing Australian income will produce PAYG instalments.
If an earlier return used the wrong residency status or omitted income, we assess amendment options and applicable time limits. Where multiple years are outstanding, our approach to overdue Australian tax obligations provides a framework for restoring compliance before addressing longer-term planning.
Use automation to improve control, not replace judgement
Filing a tax return in Australia becomes more reliable when the underlying records are maintained throughout the year. A year-end collection of bank statements rarely provides enough context to resolve residency, income source or asset valuations efficiently.
Our AI-driven processes support faster information processing and reconciliation, with professional review retained for tax judgements. Automation can help identify missing records, duplicated transactions and inconsistencies for investigation. We do not treat an automated classification as evidence that a deduction or residency position is correct.
Connected digital workflows also support more current visibility over Australian rental cash flow, business profitability and expected tax liabilities. This is valuable when an owner is managing Australian operations from another time zone.
We use that visibility for strategic advisory: reviewing cash reserves, planning distributions and assessing whether the existing structure remains suitable. Compliance then becomes a foundation for financial health and corporate growth rather than an isolated annual task.
Frequently asked questions
Is departure from Australia the same as becoming a foreign resident? No. We assess the statutory residency tests and supporting facts. Citizenship, visa status and physical absence are relevant considerations, but none automatically determines the outcome.
Is an Australian return still required if the only remaining income is rent? Generally, Australian rental income remains assessable. We review the rental result and lodgement requirements rather than assuming that moving overseas ends the obligation.
Are Australian bank interest and dividends included in the return? Not always. We check whether non-resident withholding rules apply and whether the financial institution has the correct residency details. Fully franked dividends have different treatment from unfranked dividends.
Can an Australian return be lodged while living overseas? Yes. We can assist with filing a tax return in Australia remotely, supported by secure records and appropriate authorisations. Overseas residence does not remove the need to establish the correct Australian tax position.
Can an incorrect departure-year return be amended? We assess the original treatment, available evidence and amendment period. A residency change can affect income, CGT and Medicare calculations, so correcting only the address may not resolve the error.
Next steps: coordinate the departure position and ongoing obligations
We recommend starting with a documented residency assessment, followed by an income map, asset review and entity-by-entity compliance plan. For an imminent property sale or business relocation, we prioritise decisions that cannot easily be reversed after settlement or departure.
Our team combines 25 years of professional experience with AI-driven accounting processes and integrated support across Adelaide, Sydney and Melbourne. We assist clients throughout Australia and those managing Australian interests from overseas.
To discuss a departure-year return or our automated accounting workflows, contact our team for an individual tax consultation. We can assess the Australian obligations and identify where coordinated overseas advice is needed.