When clients ask us how tax back australia works, we explain that a refund is not a bonus from the ATO. It is the final reconciliation between the tax you were required to pay for the income year and the tax credits already sitting against your account. For business owners, company directors and high-net-worth individuals, that reconciliation can involve PAYG withholding, PAYG instalments, franking credits, rental income, capital gains, trust distributions, deductions, offsets and levies.
The core formula behind an Australian tax refund
At its simplest, an Australian tax refund is calculated like this:
Refund or amount payable = total tax credits minus total tax payable
If your credits are higher than your tax payable, the ATO issues a refund. If your tax payable is higher than your credits, you have an amount owing. The ATO sets this out through your notice of assessment after your return is lodged and processed. You can also review the ATO’s general guidance on individual tax returns for the official framework.
For professionals and business owners, the calculation usually has more layers than salary income alone. A director may receive wages, dividends, trust distributions and capital gains in the same year. A sole trader may have ABN income, deductible motor vehicle costs, superannuation contributions and PAYG instalments. A property investor may have rental income, interest deductions, depreciation and capital works deductions.
| Calculation stage | What happens | Why it matters |
|---|---|---|
| Assessable income | Salary, business income, rent, dividends, capital gains and other taxable income are added | This sets the starting point for your taxable position |
| Allowable deductions | Legitimate work, business, investment and tax-related deductions are subtracted | This reduces taxable income, not tax dollar for dollar |
| Tax and levies | Tax rates, Medicare levy, HELP repayments and other obligations are applied | This determines total tax payable |
| Credits and offsets | PAYG withholding, PAYG instalments, franking credits and tax offsets are applied | This determines whether you receive a refund or owe tax |
Why tax back australia is a reconciliation, not a windfall
The phrase tax back australia often creates the impression that every taxpayer is entitled to money back at year-end. In practice, the ATO is reconciling what has already been paid or withheld against the actual tax liability for the year.
PAYG withholding is a common reason employees receive refunds. Your employer withholds tax from wages based on payroll tables. Those tables estimate your annual tax position but cannot fully predict deductions, investment losses, salary packaging, private health cover, HELP debt, family circumstances or additional income.
PAYG instalments work differently. Sole traders, investors and business owners with investment or business income may prepay tax during the year based on the ATO’s instalment system. If instalments exceed the final liability, a refund may arise. If business income grows and instalments are too low, the final return may create a payable amount.
For current bracket settings, our team recommends reviewing the relevant income year carefully. We have outlined key rate considerations in our guide to tax rates in Australia for 2026, but the correct outcome always depends on your residency, income mix and assessment year.
Step 1: Calculate assessable income accurately
The refund calculation begins with assessable income. For individuals, that can include employment income, director fees, bonuses, allowances, sole trader income, interest, dividends, rental income, trust distributions, foreign income and capital gains.
For business owners, this is where errors often begin. Bank deposits do not always equal taxable income, and accounting profit does not always equal taxable income. Timing rules, GST treatment, trading stock, depreciation, private use adjustments and accruals can all affect the final figure.
Residency is also critical. Australian tax residents are generally assessed on worldwide income, while foreign residents are usually assessed on Australian-sourced income. Temporary residents, expatriates, foreign investors and globally mobile directors should treat residency as a strategic tax issue, not an administrative checkbox.
In our digital workflows, we use AI-supported data matching and structured reconciliations to compare payroll records, bank feeds, accounting ledgers, investment statements and ATO pre-fill data. That process helps reduce omissions and improves the quality of refund forecasting before lodgement.
Step 2: Subtract allowable deductions with evidence
Deductions reduce taxable income. They do not usually reduce tax payable dollar for dollar. If a taxpayer on a 30 percent marginal rate claims a valid $1,000 deduction, the tax saving is broadly $300, before considering Medicare levy and other interactions. The refund impact depends on the taxpayer’s marginal rate and total position.
Common deductions for professionals and business owners may include accounting fees, professional subscriptions, work-related travel, home office expenses, income protection premiums, investment loan interest, business software, depreciation and tax-related advice. For property investors, deductible expenses may include interest, repairs, agent fees, council rates, insurance and depreciation where the law allows.
The ATO expects substantiation. Receipts, logbooks, invoices, loan statements, bank records and diary evidence need to support the claim. For company directors, deductions must also be separated from company expenses, director loans and reimbursements. Mixing these categories can create Division 7A, FBT or payroll tax complications.
A disciplined deduction review is one reason tax back australia outcomes vary so widely between taxpayers with similar income. The strongest outcomes usually come from clean records maintained throughout the year, not a rushed reconstruction in June or October.
Step 3: Apply tax rates, offsets and levies
Once taxable income is calculated, the relevant tax rates are applied. For Australian resident individuals, the tax-free threshold can reduce or eliminate tax on the first portion of taxable income, subject to eligibility. We explain the practical mechanics in our article on the tax-free threshold in Australia.
After basic income tax is calculated, other items may apply. The Medicare levy is generally calculated at 2 percent of taxable income, with reductions or exemptions for eligible taxpayers. The Medicare levy surcharge may apply where income exceeds the relevant threshold and the taxpayer does not hold appropriate private hospital cover.
HELP, VSL or other study and training support loan repayments can also reduce a refund. These compulsory repayments are based on repayment income, not simply taxable income. That means investment losses, reportable fringe benefits, reportable super contributions and exempt foreign employment income may affect the calculation.
Offsets are then considered. Unlike deductions, offsets directly reduce tax payable. Examples include the seniors and pensioners tax offset, low income tax offset, franking credit tax offset and foreign income tax offset. Some offsets are refundable and others are not, so the technical classification matters.
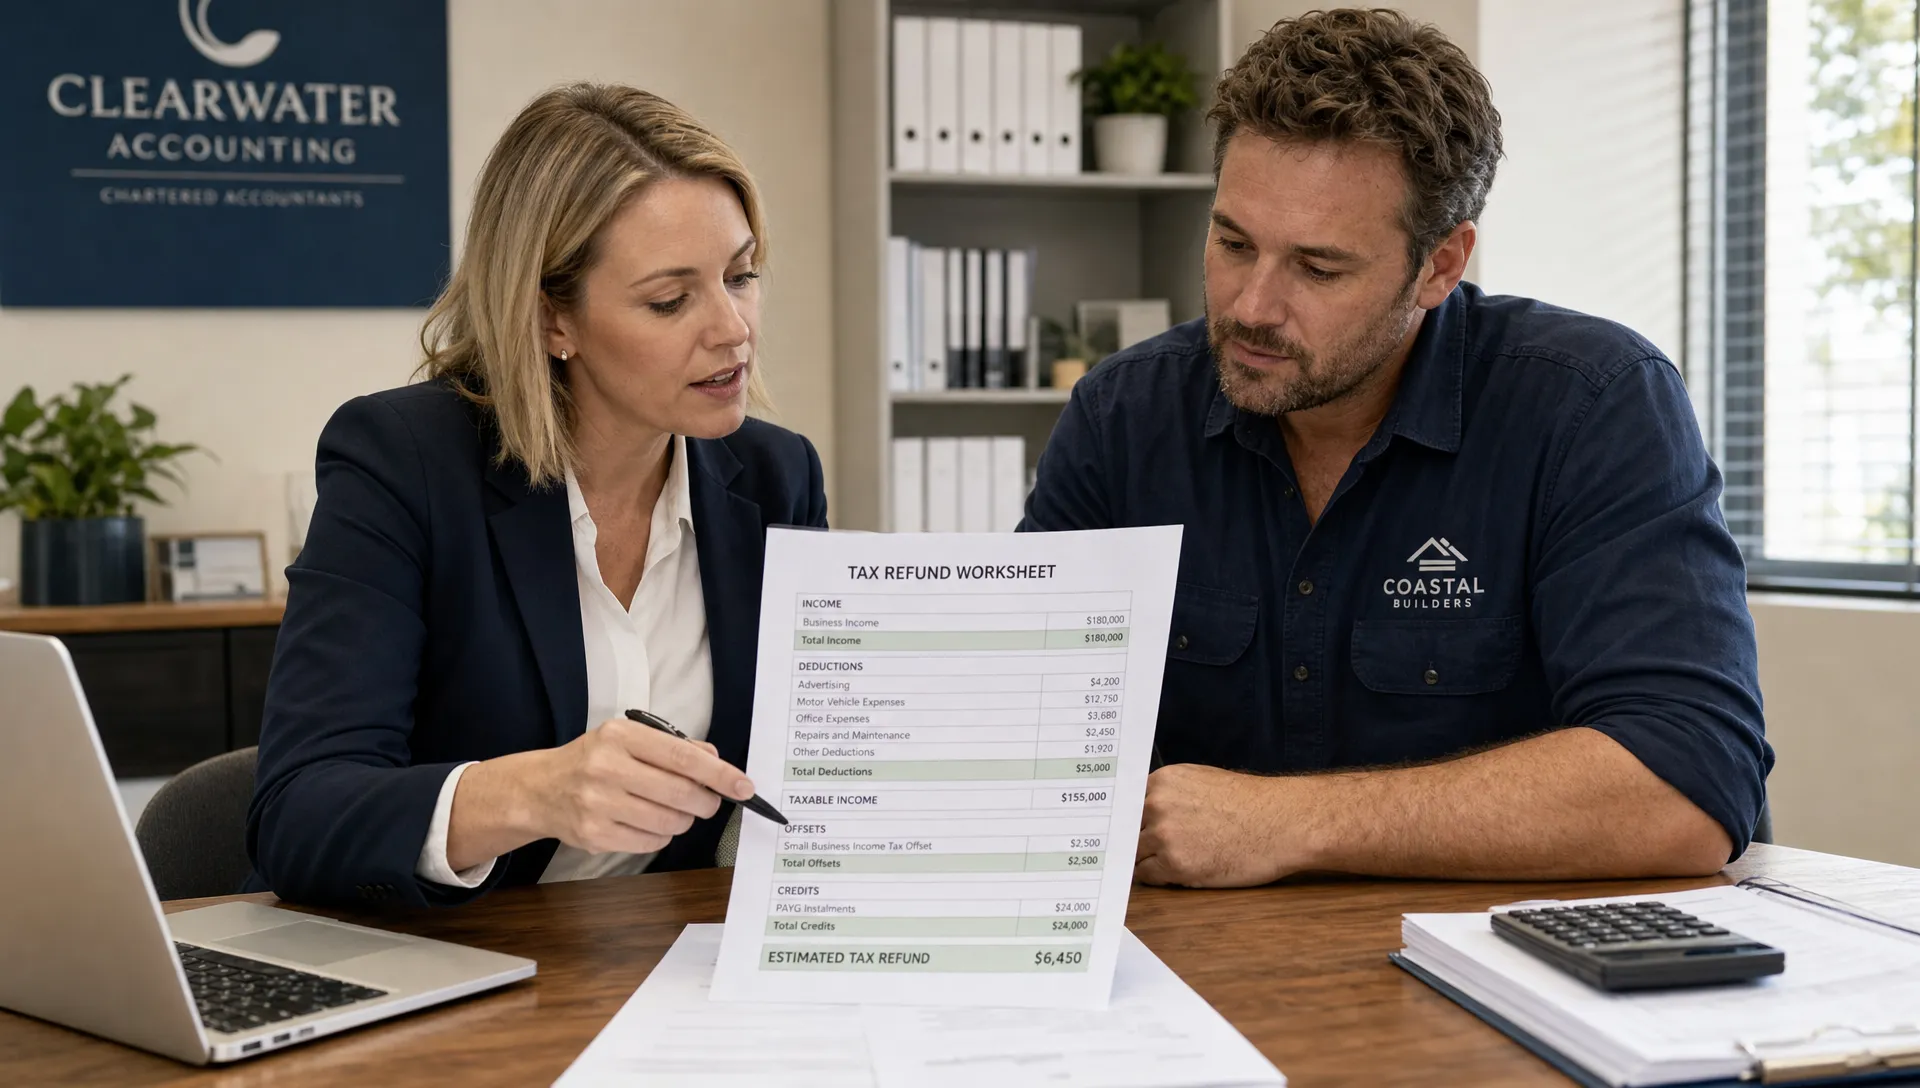
Step 4: Compare tax payable with tax credits
The final stage is comparing the tax payable with credits already recorded. These credits can include PAYG withholding from wages, PAYG instalments paid during the year, refundable franking credits, tax withheld from interest where a TFN was not provided and some foreign tax credits subject to Australian rules.
Here is a simplified example for an Australian resident individual for illustration only. It excludes many possible variables, including HELP debt, private health insurance, offsets, capital gains discounts and residency complications.
| Item | Amount |
|---|---|
| Salary and business income | $130,000 |
| Allowable deductions | $20,000 |
| Taxable income | $110,000 |
| Estimated income tax using resident rates | $23,788 |
| Medicare levy at 2 percent | $2,200 |
| Total tax payable | $25,988 |
| PAYG withholding and instalments | $31,000 |
| Estimated refund | $5,012 |
This example demonstrates why tax back australia cannot be assessed from income alone. Two taxpayers earning $130,000 may have completely different outcomes if one has PAYG withholding only, another has business income with low instalments and a third has franked dividends, property deductions and a HELP debt.
Common factors that increase or reduce a refund
Refund outcomes are sensitive to timing, documentation and the structure of your affairs. We often see refund estimates change after proper reconciliations reveal income that was missed, deductions that were unsupported or credits that were not pre-filled.
The following factors commonly affect the final result:
- Multiple employers or not claiming the tax-free threshold correctly
- Bonuses, commissions, termination payments or director fees
- ABN income without sufficient PAYG instalments
- Rental property income, negative gearing and capital works claims
- Capital gains from shares, property, crypto assets or business disposals
- Franked dividends and attached franking credits
- Private health insurance status and Medicare levy surcharge exposure
- HELP debt, reportable fringe benefits and salary sacrifice arrangements
- Late lodgements, ATO interest and prior year debts offset against refunds
For high-income earners, a refund may also be reduced by Division 293 tax, superannuation cap issues or amended assessments. For investors, capital gains timing can materially alter the result, especially where contracts exchange before 30 June but settlement occurs later.
Business owners and directors need a wider view
For business owners and directors, a personal refund is only one part of the tax position. The company, trust or partnership may have separate obligations, including company income tax, BAS, GST, PAYG withholding, superannuation guarantee, FBT and payroll tax.
GST refunds are not the same as income tax refunds. A GST refund may arise through BAS lodgement where GST credits exceed GST collected, but this is calculated under the GST system. It does not automatically mean the business is profitable, tax efficient or financially healthy.
Company directors should also distinguish between personal tax, company tax and shareholder drawings. If funds are taken from a company without correct salary, dividend or loan treatment, the tax outcome can shift quickly. We cover these issues in more detail in our guide to Australian tax return rules every director should know.
A strong tax back australia strategy therefore needs more than receipt collection. It needs integrated accounting, payroll, BAS and advisory review across the full group structure.
How automation improves refund accuracy and cash flow planning
Our team uses automation to move tax work from historical reporting to real-time financial management. For clients across Adelaide, Sydney, Melbourne and wider Australia, that means fewer surprises and better decision-making before the year closes.
AI-driven accounting workflows can help identify missing income, duplicate expenses, unreconciled bank transactions, inconsistent GST coding, unusual payroll entries and mismatches between ledger data and ATO records. Automation does not replace professional judgement, but it gives our advisers cleaner data and more time to focus on structuring, cash flow, risk and growth.
For business owners, this is where compliance becomes strategic advisory. If we can forecast taxable income, instalments and potential refunds earlier, we can also help plan super contributions, dividend timing, asset purchases, debt reduction, director remuneration and working capital reserves.
That is the difference between asking about tax back australia after lodgement and managing the full tax position throughout the year.
Frequently asked questions
How does the ATO calculate an Australian tax refund? The ATO calculates your refund by assessing your taxable income, applying tax rates and levies, then subtracting credits such as PAYG withholding, PAYG instalments, offsets and eligible franking credits. If credits exceed tax payable, a refund is issued.
Are deductions refunded in full? No. Deductions reduce taxable income, not tax payable directly. The refund benefit depends on your marginal tax rate, Medicare levy position, offsets and other assessment items.
Why was my refund lower than expected? Common reasons include HELP repayments, Medicare levy surcharge, additional income, unsupported deductions, lower PAYG withholding, ATO debts, amended prior years or business income that was not covered by instalments.
Is GST included in my tax refund? No. GST is managed through BAS and is separate from an individual or company income tax refund. A business may receive a GST refund through BAS while still owing income tax, or the reverse.
Can a tax refund help with cash flow or lending? Yes, but it should be treated as a one-off cash inflow rather than recurring income. If you plan to use a refund in a finance context, lenders usually focus on the broader income and debt profile, not the refund alone.
Next steps: calculate your refund strategically
If you want a more accurate refund estimate, start by reconciling income, deductions, PAYG credits, instalments, BAS activity, payroll, superannuation and investment records before lodging. For directors and business owners, review the personal and entity-level position together.
Our team at Perfect Accounting & Tax Services helps clients across Australia calculate refunds, manage ATO compliance and build automated accounting workflows that support better financial visibility. We bring 25 years of Australian tax and advisory experience to complex personal, business and investment structures.
To move beyond a once-a-year refund discussion, contact our team for a consultation. We can review your current tax position, identify risks before lodgement and show how automated accounting workflows can support stronger cash flow, cleaner compliance and long-term corporate growth.