Division 7A can turn informal director drawings into an unexpected personal tax liability. We focus on the solutions tax and accounting teams use to control that risk: correctly classified transactions, documented loans and properly funded repayments. For business owners and directors, our objective is to protect financial flexibility without treating company funds as personal cash.
We draw on 25 years of professional experience to connect compliance with strategic advisory. Our approach combines tax analysis, reliable accounting records and AI-driven workflow automation, giving decisions about company money a stronger foundation.
Where we identify Division 7A exposure
We review Division 7A whenever an Australian private company provides money or benefits to a shareholder or an associate. Associates can include family members and related entities, depending on the statutory relationship tests.
Under the rules, certain payments, loans and forgiven debts can become deemed unfranked dividends. We assess the exclusions and the company’s distributable surplus before determining the potential tax outcome. Distributable surplus is a statutory calculation, not simply the retained earnings figure in the financial statements.
| Transaction we investigate | Potential concern | Our initial review |
|---|---|---|
| Cash transferred to a shareholder | An outstanding loan or shareholder payment | Purpose, repayment history and account balance |
| Company payment of personal expenses | A private benefit funded by the company | Recipient, classification and supporting documents |
| Forgiveness of a shareholder debt | A potentially deemed dividend | Legal release, exclusions and distributable surplus |
| Funds routed through related entities | Possible interposed-entity exposure | The complete funding pathway |
We prioritise the solutions tax and accounting teams can apply before these movements become year-end tax problems.
How we distinguish private expenses from business expenditure
We trace the underlying purpose of each transaction rather than relying on its ledger description. A payment labelled “director advance” still needs analysis, while a genuine repayment of money previously lent to the company requires supporting evidence.
Family expenses deserve particular attention. For an Australian-resident owner, an invoice from an overseas provider such as Aubrey Early Learning Centre in Stillwater, New Zealand remains a private expense when incurred for personal childcare. We do not assume a business deduction or GST credit merely because a company account paid the invoice.
We also distinguish shareholder benefits from employment-related benefits. FBT and Division 7A have interaction rules, so we examine the capacity in which a benefit was provided. Reclassifying a transaction as an employee benefit without checking the facts does not establish the correct treatment.
The solutions tax and accounting teams need for Division 7A
We manage Division 7A through a sequence of decisions: establish the facts, identify the applicable deadline, select a lawful treatment and monitor the resulting obligations. A journal entry alone does not create a compliant arrangement.
We reconstruct the loan position
We reconcile each shareholder and associate account against bank transactions, expense records and prior-year balances. We identify who owes whom, whether agreements already exist and whether earlier repayments were recognised correctly.
We separate existing complying loans from new advances. Combining everything into one running director account can obscure different loan terms, repayment requirements and historical problems.
Where records are incomplete, we request the agreements, bank statements and evidence of genuine repayments before recommending a treatment. This groundwork also improves the quality of management reporting and future funding decisions.
We control the lodgment-day deadline
For relevant loans made during an income year, we assess whether repayment or a complying written loan agreement can prevent a deemed dividend. The critical deadline is generally the company’s lodgment day, meaning the earlier of its actual income tax return lodgment date and its due date.
We build deadlines into the solutions tax and accounting teams use because lodging early can bring the decision point forward.
For example, assume a company advances funds during 2025-26. Its return is due on 15 May 2027, but it plans to lodge on 15 February 2027. We would arrange the required repayment or complying agreement before the February lodgment, rather than treating May as the available deadline.
We connect this review with our broader corporate tax checks before EOFY, while recognising that the initial loan deadline and subsequent annual repayment deadline are different obligations.
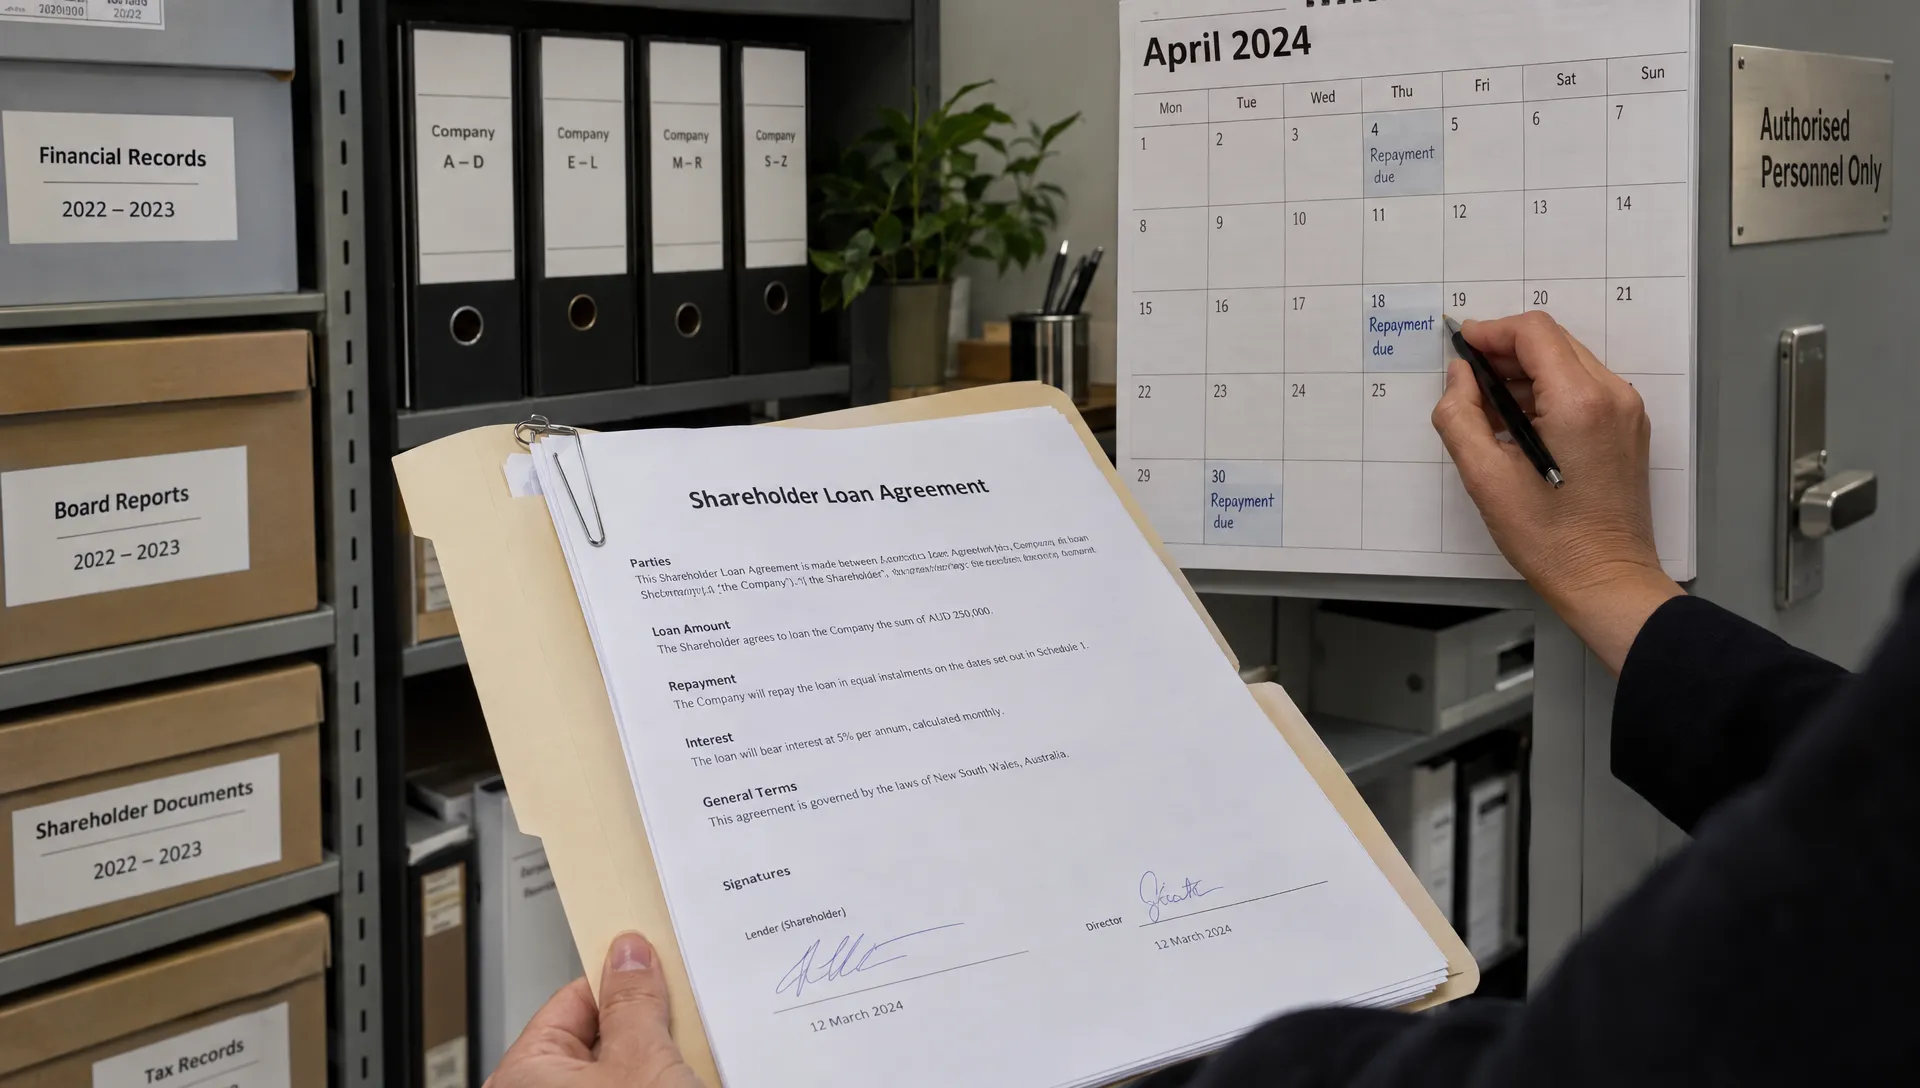
We document an appropriate complying loan
We assess whether a loan satisfying section 109N of the Income Tax Assessment Act 1936 is commercially appropriate. The agreement must meet the statutory conditions, including the applicable interest and maximum term requirements.
| Requirement | Our review focus |
|---|---|
| Written agreement | Completion before the relevant lodgment-day deadline |
| Interest | At least the applicable Division 7A benchmark rate |
| Generally unsecured loan | Maximum term of seven years |
| Qualifying property-secured loan | Maximum term of 25 years, subject to security conditions |
We include enforceable documentation in the solutions tax and accounting teams rely on, not just a repayment spreadsheet.
For the longer term, we check the registered mortgage over real property and the statutory 110% security-value requirement, including relevant prior-ranking liabilities. We do not assume that property ownership alone qualifies a loan for 25 years.
We calculate and fund minimum annual repayments
After establishing a complying loan, we calculate the minimum yearly repayment for each subsequent income year. We use the relevant ATO benchmark interest rate, the loan balance and the remaining term. We do not leave the original rate unchanged throughout the loan.
For illustration only, a $100,000 balance with seven years remaining and an assumed 8% rate produces a minimum annual repayment of approximately $19,207. We substitute the actual benchmark rate for the relevant year; this assumed rate is not a statement of the current ATO rate.
We make repayment funding central to the solutions tax and accounting teams implement. An agreement that satisfies the initial requirements still needs ongoing management.
For a loan made in 2025-26 and placed on complying terms, we would generally assess the first minimum yearly repayment for 2026-27, due by 30 June 2027. An insufficient repayment can create a deemed dividend based on the shortfall, subject to the applicable rules and distributable surplus limit.
How we connect loan repayments with financial strategy
We assess Division 7A alongside personal tax, company liquidity and planned investment. The lowest immediate cash outflow is not necessarily the best overall result.
A genuine cash repayment reduces the shareholder’s debt but requires funds outside the company. A lawfully declared dividend may support repayment through an effective set-off, but we first examine personal tax consequences, available franking credits and the company’s legal capacity to pay it.
We also assess whether remuneration is appropriate for services actually performed. Salary or bonuses bring PAYG withholding, reporting and potentially superannuation obligations. We do not treat remuneration as a convenient label for historical drawings.
We connect the solutions tax and accounting teams recommend with forecasts showing the effect on working capital, tax reserves and investment capacity. This is where compliance becomes strategic advisory: the loan decision needs to work for both the company and the owner.
Our approach to tax-efficient accounting that improves cash flow supports this analysis. We forecast repayment commitments alongside BAS, GST, payroll and other obligations rather than allowing one deadline to compete unexpectedly with another.
Where we apply additional scrutiny
We test repayments followed by redraws
We review the source and timing of repayments, not just the closing bank balance. Division 7A contains rules that can disregard certain repayments associated with reborrowing or arrangements to obtain further company funds.
A temporary transfer into the company shortly before 30 June, followed by a planned withdrawal, may therefore fail to achieve the intended result. We assess the full arrangement before recognising a repayment for tax purposes.
We examine funding substance within the solutions tax and accounting teams apply, particularly where several related entities move money around the same period.
We review trusts and unpaid present entitlements separately
Where a trust owes an unpaid present entitlement to a private company, we review current case law and ATO guidance rather than assuming every entitlement is, or is not, a Division 7A loan.
We separately examine actual lending arrangements, the use of funds and relevant trust provisions, including Subdivision EA where applicable. A conclusion about an unpaid entitlement does not automatically resolve loans or benefits provided to shareholders and associates through the trust.
For broader guidance, we refer to the ATO’s information on private company benefits and Division 7A dividends, then apply the law to the specific arrangement.
How we use automation without outsourcing judgement
We use AI-driven automation to streamline financial workflows and improve the accuracy and speed of accounting processes. For Division 7A, cleaner records make unusual transactions easier to identify and loan balances easier to monitor.
Our recommended control framework includes separate shareholder accounts, consistent transaction classifications and reviewed repayment schedules. Where financial feeds are current, automation supports near-real-time visibility into drawings and available cash.
We combine professional judgement with the solutions tax and accounting teams automate. Technology can assist with reconciliation and exception detection, but it cannot independently establish a transaction’s legal purpose or confirm that a repayment arrangement satisfies the legislation.
We retain professional review over agreements, interest calculations, distributable surplus and the interaction with FBT, dividends and remuneration. We also compare accounting entries with executed documents and actual cash movements.
Reliable bookkeeping is therefore a foundation for corporate growth, not merely an input to a tax return. It helps us assess whether distributions, expansion plans and funding commitments remain affordable.
How we support directors across Australia
We provide integrated accounting, tax and strategic advisory support across Australia, including Adelaide, Sydney and Melbourne. For businesses operating across states, we coordinate the financial picture across company accounts, related entities and owner-level obligations.
Our virtual CFO and advisory services connect Division 7A commitments with broader financing and growth decisions. We aim to give directors a clear view of what the company can distribute, what owners must repay and which commitments need to be funded before further investment proceeds.
Frequently asked questions
Does every director loan create a Division 7A dividend? No. We first determine whether the recipient is a shareholder or associate and whether the arrangement falls within the rules. We then assess exclusions, repayment, complying loan terms and distributable surplus.
Can we fix the issue with a year-end journal? We do not rely on a journal alone. Effective solutions tax and accounting teams use require the legal and commercial substance to support the entry, including valid agreements, genuine repayments or properly executed set-offs.
What happens if the repayment deadline has already passed? We quantify the exposure and review the circumstances. Depending on the facts, amendments, voluntary disclosure or an application for the Commissioner’s discretion may be appropriate. We do not assume relief will be available.
Does a complying loan remove the tax cost entirely? We treat it as a funding arrangement with continuing obligations. Interest and minimum annual repayments remain relevant, and dividends or remuneration used to fund repayment can create separate personal tax consequences.
Next steps: how we can help
We recommend reviewing company-funded personal spending and related-party balances before the next return is lodged or another distribution is made. For an initial assessment, we request:
- Current shareholder and associate loan ledgers, including opening balances.
- Existing loan agreements and evidence of repayments.
- Company return due dates and planned lodgment dates.
- Related trust records and forecasts for company and personal cash flow.
We translate the solutions tax and accounting teams develop into a practical plan: the required treatment, the controlling deadlines and the funding implications.
Contact Perfect Accounting & Tax Services for a consultation on Division 7A or our automated accounting workflows. We can help assess the exposure and align the response with financial health and corporate growth.