When we receive an “overdue tax return Australia” enquiry, we start with the ATO notice, its deadline and the taxpayer named on it. A reminder to lodge requires a different response from a default assessment, payment demand or director penalty notice. Treating them as interchangeable can leave important obligations unresolved.
Our objective is to establish the correct tax position, address enforcement risk and restore financial visibility. We separate missing returns from unpaid liabilities, reconstruct the supporting records and develop a response that the business can sustain.
With 25 years of professional experience, our team supports businesses, directors and individuals with significant assets across Australia. Through our integrated capabilities in Adelaide, Sydney and Melbourne, we combine technical review with AI-assisted accounting workflows to make overdue compliance the starting point for stronger financial management.
Overdue tax return Australia: our first response to an ATO notice
We first verify that the communication is genuine through a trusted ATO channel or the relevant tax account, rather than relying on links or payment instructions in an unexpected message. We then identify the entity, outstanding periods and required action.
The document’s heading matters, but we also examine its legal effect and response deadline.
| Communication | What we establish | Our response priority |
|---|---|---|
| Overdue lodgement reminder | Which returns remain outstanding and whether they are required | Confirm obligations and prepare a lodgement schedule |
| Formal demand to lodge or prosecution warning | The required action and consequences of non-compliance | Escalate the response and address the stated deadline |
| Default assessment | How the ATO estimated the liability and the applicable objection period | Review the assessment and protect dispute rights |
| Payment demand | Whether assessed amounts remain unpaid or disputed | Reconcile the debt and assess payment options |
| Director penalty notice | The liability, statutory timeframe and potential personal exposure | Obtain urgent specialist advice alongside the tax review |
We record each notice separately. A business may have several active issues, and resolving one does not automatically resolve the others.
When we escalate immediately
We prioritise director penalty notices, court documents and formal enforcement correspondence. Director penalties can concern PAYG withholding, net GST and superannuation guarantee charge liabilities, rather than simply an overdue income tax return.
We do not calculate a director penalty notice deadline from the day the letter was opened. Its statutory 21-day period can run from posting, and the available responses depend on the circumstances. Where personal liability or solvency is involved, we recommend urgent legal or insolvency advice alongside our accounting work.
How we confirm which returns are actually outstanding
For an overdue tax return in Australia, we establish the lodgement obligation before calculating the tax. A reminder does not, by itself, establish that the taxpayer owes money.
We review ATO records against the business structure and activity for each year. A director’s personal return is separate from the company’s return. Trusts, partnerships and SMSFs may have their own reporting requirements, while an individual may also have rental income, capital gains or foreign income to disclose.
Where an individual was not required to lodge, we assess whether a non-lodgment advice is appropriate. We do not assume that low income removes every obligation, or that a dormant company or trust has nothing to report.
We also confirm the actual due date. Tax-agent lodgement arrangements do not automatically extend an already overdue deadline, and appointing an agent does not erase a notice.
If several years are outstanding, we map the full backlog. The ATO explains the available lodgement channels in its guidance on lodging prior-year tax returns. We assess the appropriate method for each year rather than assuming current-year software supports every historical return.
How we rebuild missing records without guessing
We reconstruct the evidence before finalising figures. Bank statements are useful, but deposits do not always represent taxable income. They may include transfers, loan proceeds, capital contributions or GST collected.
Our review brings together bank transactions, invoices, payroll records, investment statements and available ATO information. For property owners and high-net-worth individuals, we also examine acquisition costs, disposal records, borrowing expenses and relevant foreign transactions.
When resolving an overdue tax return in Australia, we apply the law relevant to each income year. Current deduction thresholds, depreciation concessions and tax rates cannot simply be applied retrospectively.
How we use automation with professional review
Our AI-assisted workflows help organise documents, identify duplicates and flag transactions requiring investigation. Reconciliation and exception checks improve speed and accuracy while giving us a clearer view of missing evidence.
We retain professional review over tax classifications and judgement-sensitive items. Automation does not substantiate a deduction, determine tax residency or replace evidence of a historical transaction. We also apply access controls when handling TFNs, identity documents and financial records.
We check opening balances, carried-forward losses and depreciation schedules across years. For companies and trusts, we review shareholder loans and contemporaneous distribution records. A late return cannot retrospectively create a valid trust resolution or repair every historical structuring problem.
How we separate lodgement from payment
We generally proceed with accurate lodgement even when immediate payment is not possible. Delaying a required return because cash is unavailable can compound compliance problems without resolving the debt.
Our response to an overdue tax return in Australia therefore has two connected workstreams: establishing the liability and developing a credible payment strategy.
We reconcile assessments, PAYG credits, existing debts and available account balances before discussing payment options. We do not assume that a calculated refund will be paid directly to the taxpayer, because the ATO may offset it against outstanding liabilities.
Where a payment arrangement is needed, we prepare a cash-flow assessment that includes current BAS, payroll, superannuation and operating commitments. Any arrangement remains subject to ATO acceptance, and interest generally continues on unpaid amounts.
If the notice includes a default assessment, we separately check objection rights and deadlines. Simply lodging the missing return may not preserve the taxpayer’s right to challenge that assessment.
How we assess penalties and interest
We distinguish failure-to-lodge penalties from interest on unpaid tax. They arise for different reasons and require separate analysis.
Under the ATO’s failure-to-lodge penalty framework, the base calculation generally uses one penalty unit for each 28-day period, or part of a period, up to five periods. Entity size and other statutory rules can increase the amount. We check the applicable penalty-unit value and circumstances rather than quoting a universal dollar figure.
General interest charge can apply to overdue tax debts. Its rate changes quarterly, so we use the relevant periods when assessing exposure. The ATO’s general interest charge guidance explains its operation.
We also factor in a significant cash-flow consequence: general interest charge and shortfall interest charge incurred on or after 1 July 2025 are not deductible, including where the underlying tax relates to an earlier year.
How we prepare a remission request
We assess whether there are grounds to request remission of a penalty or interest. For an overdue tax return in Australia, that assessment is separate from preparing the return and cannot be reduced to a promise that charges will disappear.
We document what caused the delay, which periods were affected and what action was taken once the problem became manageable. Serious illness, disaster-related disruption or other relevant circumstances need supporting evidence and a clear explanation of their impact.
We address the applicable remission criteria and distinguish penalty remission from interest remission. Corrective action supports a coherent submission, but the ATO decides the outcome.
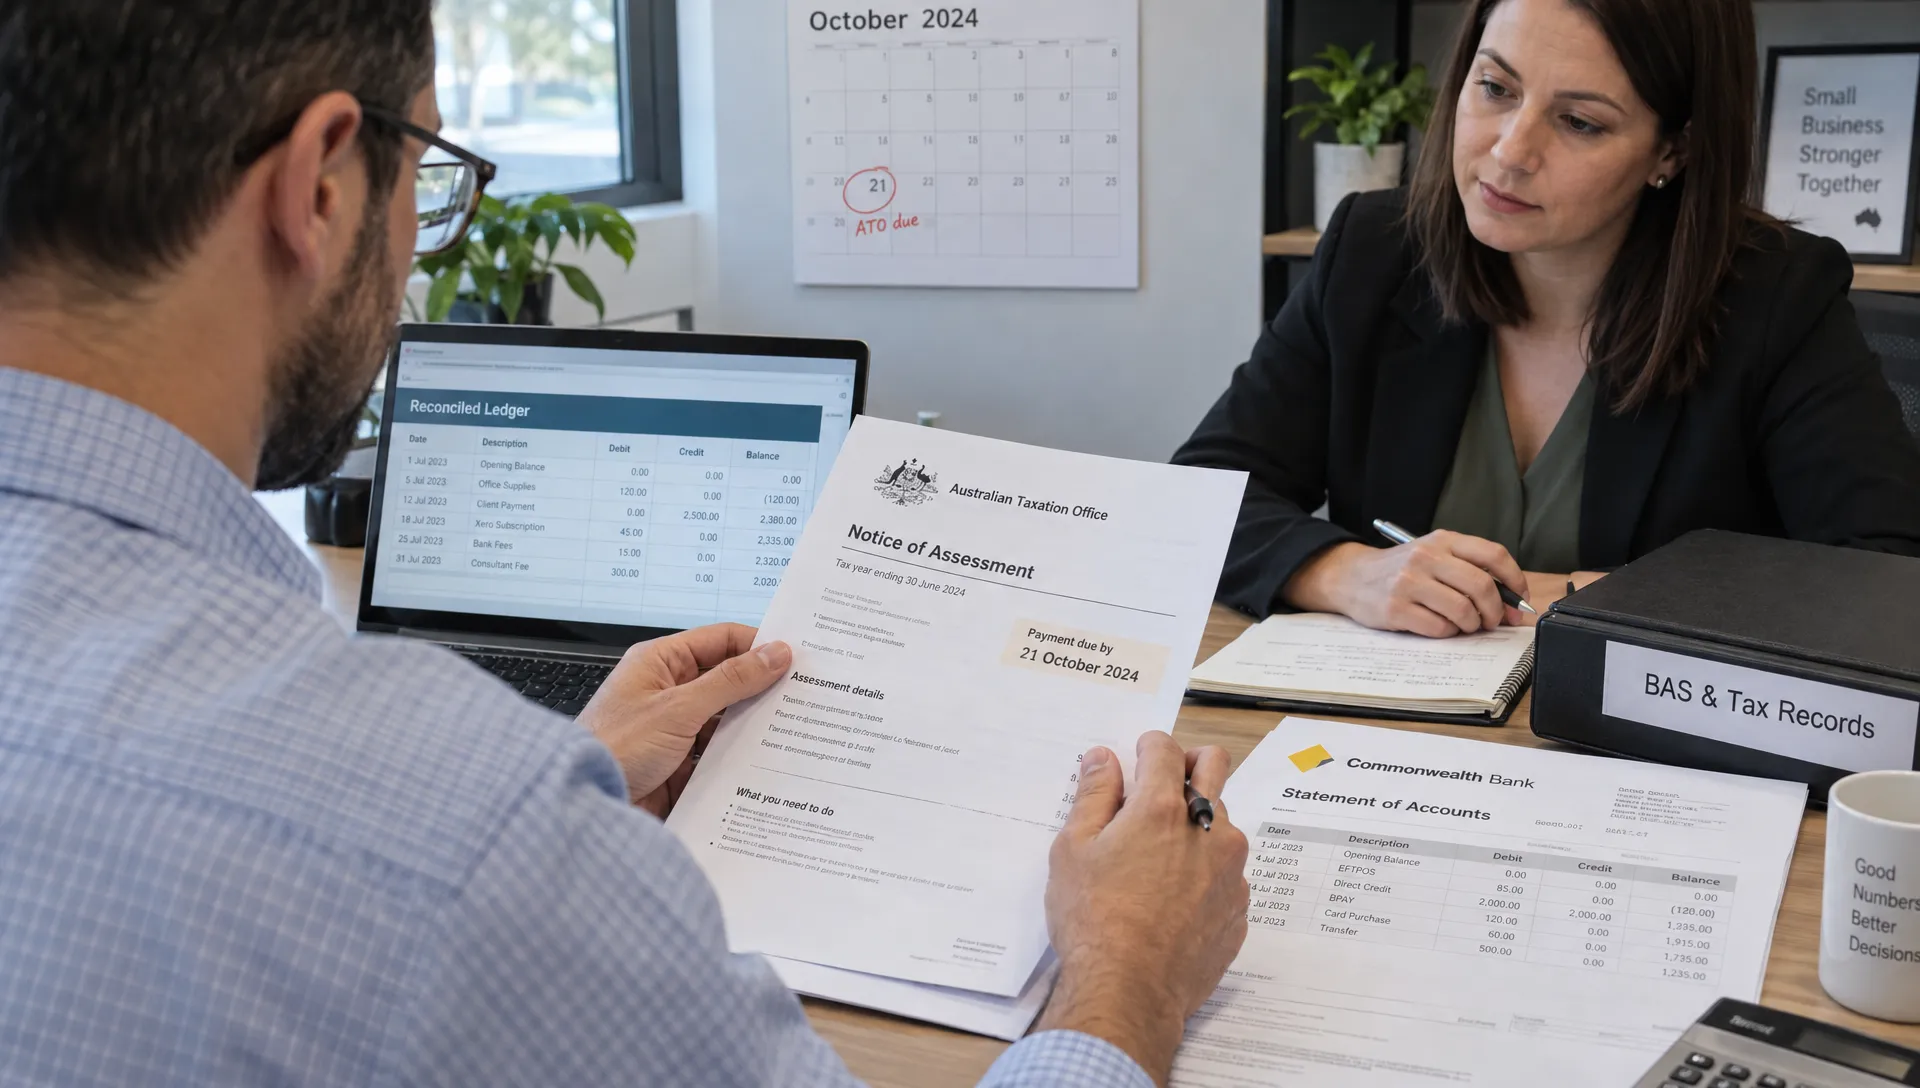
How we close related gaps and restore financial visibility
We check whether the overdue return reflects a wider reporting breakdown. Missing BAS, inconsistent GST treatment, payroll errors and unpaid superannuation can require separate corrective action. Lodging an income tax return does not resolve those obligations.
Where the backlog extends beyond income tax, our guide to when an accountant for back taxes is needed explains the broader compliance issues we assess.
We then move from historical repair to a repeatable reporting cycle. Automated transaction feeds, document capture and regular reconciliations can improve the timeliness of financial information. Exception reviews help identify missing invoices, unusual balances and emerging liabilities before the next deadline.
We use that information as a foundation for strategic advisory and corporate growth. Reliable accounts allow us to assess working capital, debt serviceability and the capacity to fund expansion. Our approach to business tax return planning connects those decisions with ongoing tax obligations rather than leaving them until year-end.
Frequently asked questions
What happens if we have not lodged Australian tax returns for several years? We establish which returns were required, identify notices and assessments, then rebuild the records for each outstanding year. Failure-to-lodge penalties and interest may apply, while prolonged non-compliance can lead to enforcement. We prioritise urgent deadlines without overlooking the full backlog.
Can we lodge a tax return that is 10 years overdue? We can generally work through historical lodgements, subject to confirming the relevant obligations and lodgement method. There is no general rule that an unlodged return disappears after 10 years. We also review any default assessments and recognise that recovering old records may require substantial reconstruction.
How late can we lodge an overdue tax return in Australia? We do not treat a missed deadline as a reason to abandon lodgement. Required returns remain outstanding until appropriately resolved. We check the correct due date, any formal notice and the available lodgement channel, then act promptly. Any objection or court deadline requires separate attention.
Can we lodge if the tax bill cannot be paid immediately? We generally separate accurate lodgement from payment negotiations. We assess the debt and prepare an affordable proposal where appropriate, but ATO acceptance is not automatic. We also allow for ongoing interest and current tax obligations when assessing repayment capacity.
Will engaging our team remove penalties? We cannot guarantee remission or prevent every enforcement action. We can identify the relevant issues, prepare outstanding returns and present an evidence-based request where grounds exist. Early engagement gives us more opportunity to assess deadlines and develop a coordinated response.
Next steps: how we can help
We begin with a focused review of the notice and the outstanding periods. For the initial consultation, we ask for the following information through an agreed secure channel:
- The complete ATO notice, including its issue date and stated deadline.
- The entities and income years believed to be outstanding.
- Available accounting records, prior returns and details of any existing payment arrangement.
- Any court documents or director penalty correspondence requiring urgent attention.
We then outline the lodgement sequence, evidence gaps, likely areas of exposure and immediate actions. Our integrated team in Adelaide, Sydney and Melbourne supports clients nationally, connecting overdue compliance work with cash-flow planning and stronger financial controls.
We invite business owners, directors and individuals with complex affairs to contact Perfect Accounting & Tax Services for a consultation. We can also explain how our automated accounting workflows can reduce manual work and improve ongoing financial visibility.