An acquisition can look attractive on reported earnings and still expose a buyer to inherited tax liabilities, overstated cash flow or an unsuitable ownership structure. When we assess a tax company for acquisition support, we focus on whether its advice improves the purchase decision, informs negotiations and supports the business after completion. A clean lodgement history alone does not answer those questions.
At Perfect Accounting & Tax Services, we draw on 25 years of professional experience to connect tax analysis with financial health, strategic advisory and corporate growth. Our assessment starts with the transaction, not a standard compliance package.
Establish the acquisition mandate first
Before comparing advisers, we define what the buyer needs to decide. Buying shares in an existing company creates different exposures from acquiring selected business assets. A property-rich business, a cross-border acquisition or a transaction involving related parties requires further specialist analysis.
We establish the proposed buyer, funding arrangements, transaction timetable and intended operating structure. We also identify whether the acquisition involves employees, property, intellectual property or multiple entities.
The engagement should then distinguish tax due diligence, financial analysis, transaction structuring and implementation. These are connected workstreams, but they are not interchangeable. Reviewing historical tax returns does not establish sustainable earnings, and financial due diligence does not constitute a statutory audit.
We agree responsibility boundaries early, including when legal advisers, valuation specialists or other experts need to contribute. This prevents important work from falling between separate engagement letters as negotiations accelerate towards signing.
What we expect from a tax company before engagement
We begin with professional standing and relevant capability. Through the Tax Practitioners Board public register, we verify the registration of the entity providing tax agent services. We also establish who will lead the work and take responsibility for the advice.
Registration is a baseline, not evidence of acquisition expertise. We look for a clear explanation of how the adviser would investigate the target’s risks, communicate incomplete information and translate findings into decisions.
Evidence that demonstrates transaction capability
Rather than relying on broad claims about experience, we request an anonymised report format or proposed deliverables. We expect to see a method for distinguishing confirmed liabilities, estimated exposures and unresolved questions.
We also examine conflicts of interest. An adviser acting for the seller or target may hold useful historical knowledge, but that does not automatically make the adviser suitable to provide independent buyer-side advice.
Where accountant-reviewed returns form part of the evidence, we assess their underlying reconciliations. Our discussion of how accountant-reviewed tax returns support due diligence explains why lodged figures need supporting records before we rely on them in a transaction.
Challenge the proposed transaction structure
We expect a tax company to compare the consequences of the proposed structure before commercial terms become difficult to change. The analysis should cover both the buyer’s acquisition position and the business’s ongoing tax profile.
| Issue | Asset acquisition | Share acquisition |
|---|---|---|
| Historical liabilities | We assess which liabilities transfer, remain with the seller or create other buyer exposures. | We examine historical exposures within the company being acquired. |
| Tax cost bases | We review purchase-price allocation and the applicable treatment of each asset. | We recognise that acquiring shares generally does not reset the company’s underlying asset tax cost bases. |
| GST | We test the transaction’s GST treatment, including any proposed going-concern treatment. | We assess the GST treatment of the share transaction and associated acquisition costs. |
| Transfer duty | We check relevant state or territory rules for the assets involved. | We investigate landholder duty and other applicable state or territory provisions. |
These differences require modelling rather than a default preference for one structure. For example, GST-free going-concern treatment is not automatic simply because a trading business changes hands. We test the statutory requirements and coordinate the findings with the transaction lawyers.
We also examine acquisition funding, shareholder arrangements and proposed distributions. Company tax does not necessarily represent the final tax cost when profits eventually reach individual owners.
Build a cash-tax model, not just a rate comparison
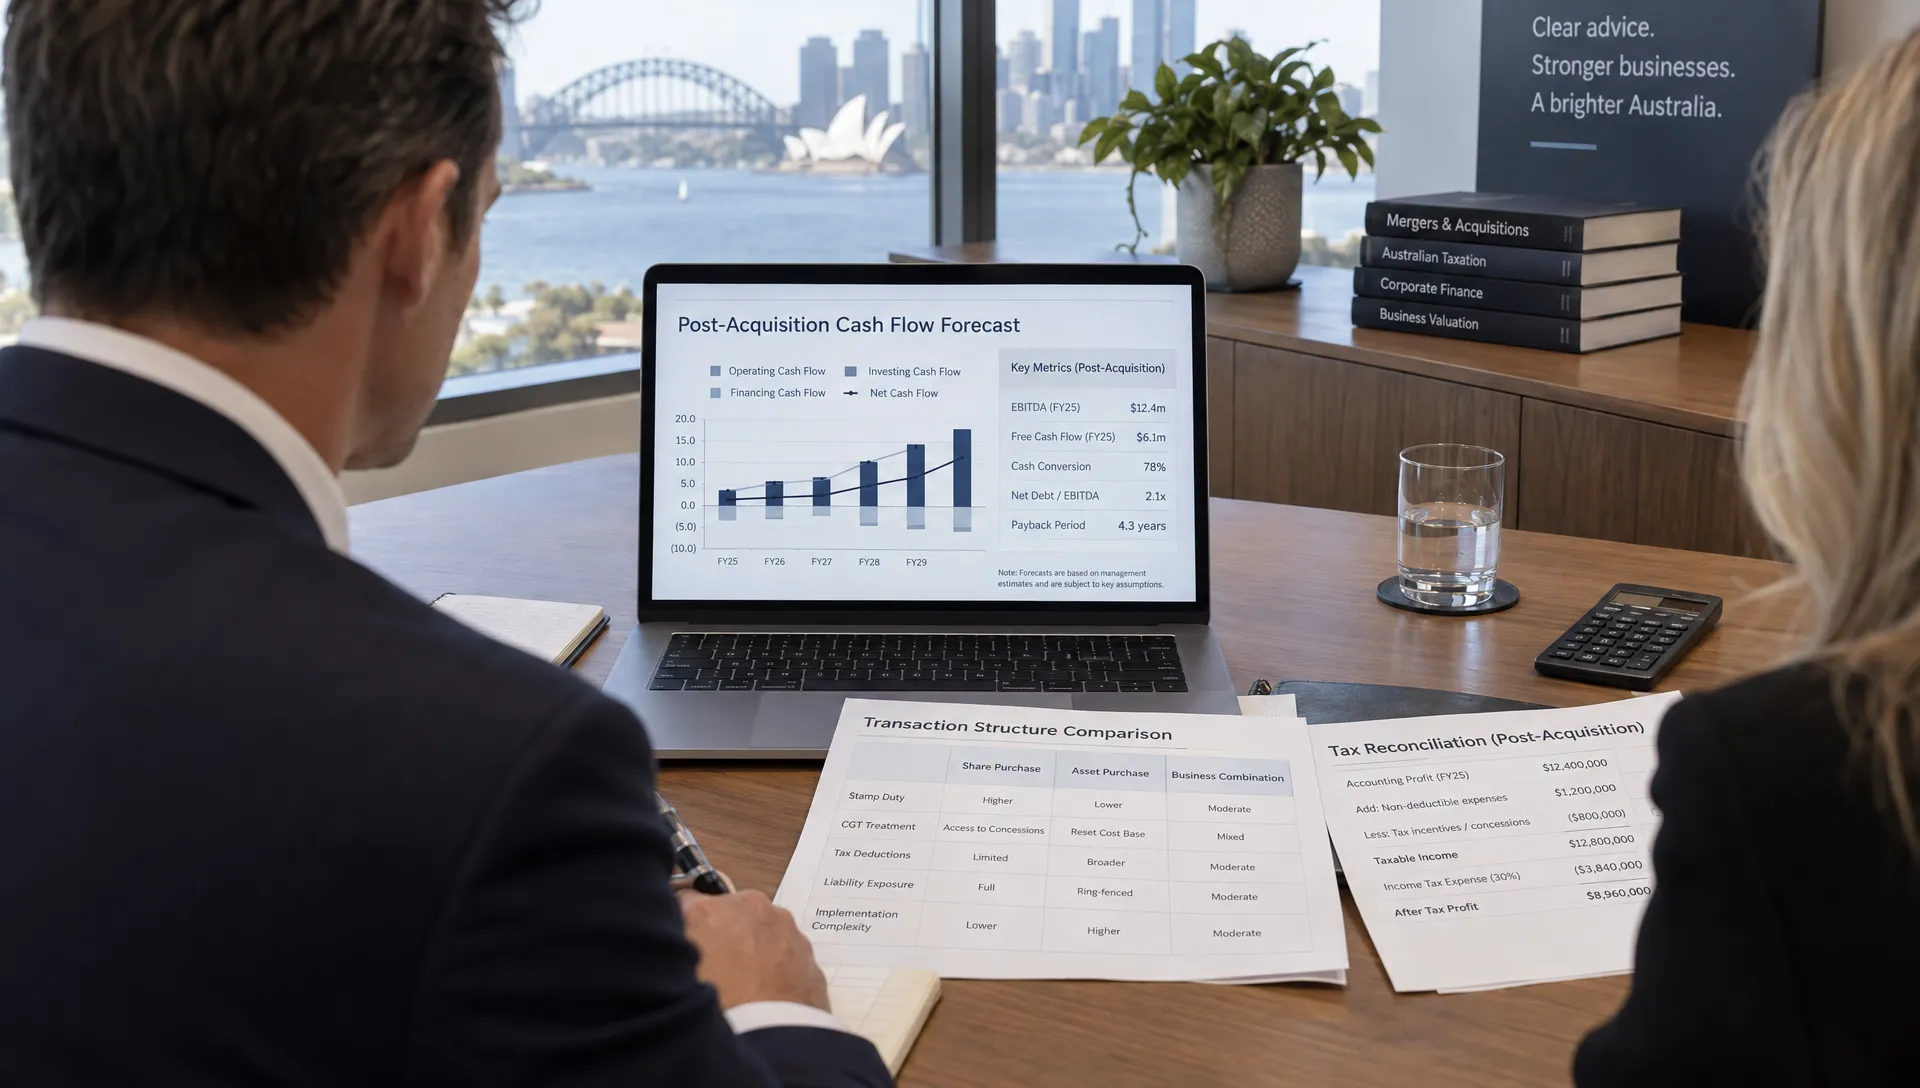
We assess whether a tax company can connect technical conclusions to acquisition funding and working capital. A forecast that applies a single tax percentage to accounting profit is rarely sufficient.
For Australian companies, the general company tax rate is 30%. The 25% rate applies to eligible base rate entities, broadly requiring aggregated turnover below $50 million and no more than 80% base rate entity passive income. We verify eligibility against the ATO’s company tax rate guidance, including relevant connected-entity and affiliate rules.
Our acquisition model should separately address taxable income, cash tax payments, PAYG instalments and the timing of deductions. We also challenge assumptions about transaction costs, because acquisition expenditure is not automatically deductible when paid.
Test the assumptions that affect funding
We examine whether ownership changes could restrict carried-forward tax losses. We do not treat a tax loss balance as a guaranteed future saving. Continuity of ownership and business continuity requirements need specific analysis.
For a private company, we also investigate shareholder loans and potential Division 7A issues. Franking balances require verification rather than an assumption that every recorded credit will be available for planned distributions.
We then model a downside case, including slower collections, additional tax payments or delayed deductions, so the buyer can assess funding headroom before committing.
Require findings that can influence negotiations
A useful tax company report should do more than catalogue issues. We expect each material finding to explain the evidence, likely financial effect, uncertainty and proposed response.
We reconcile income tax returns, BAS, payroll records and relevant ATO account balances to the financial information used in the transaction. GST, PAYG withholding, Superannuation, FBT and state payroll tax can reveal exposures that a headline income tax review misses.
We distinguish a payment timing difference from an unsupported tax position. We also distinguish a quantified liability from a risk that cannot yet be estimated reliably.
Turn each material issue into an action
For an illustrative unpaid payroll-related liability, we would identify the affected periods, principal amount, possible additional charges and outstanding evidence. We would then assess the effect on cash flow and raise the appropriate contractual response with the buyer’s lawyers.
A price adjustment, specific indemnity, retention or pre-completion remediation may be considered. None is an automatic entitlement, and contractual protections do not remove the underlying company’s obligations to the ATO.
Our preferred output is a decision register showing the issue, financial sensitivity, responsible adviser and deadline. That allows directors to decide which matters must be resolved before signing, before completion or during integration.
Validate automation without outsourcing judgement
We assess a tax company’s digital capability by the reliability of its evidence trail, not the number of AI tools it mentions. Faster document handling is valuable only when the resulting analysis remains traceable and reviewable.
Our AI-driven processes help reduce repetitive handling, improve consistency and support more timely financial visibility. We retain professional judgement over tax positions and acquisition conclusions. Automation supports the review; it does not replace responsibility for it.
Specialist accounting-firm automation examples illustrate practical workflows such as invoice capture and debtor follow-ups. We treat overseas examples as operational references, not evidence of compliance with Australian tax law.
Test the controls behind the workflow
For acquisition work, we examine how documents are sourced, matched and checked. An extracted invoice amount should be verifiable against the original document, while exceptions should remain visible until resolved.
We also examine access permissions, handling of TFNs and payroll information, external processing arrangements and retention controls. Seller information should not enter an AI service without appropriate authority and an assessment of confidentiality obligations.
The strategic benefit is a shorter path from evidence to decision. Reliable, regularly refreshed information helps us identify cash-flow pressure, assess integration progress and move beyond retrospective compliance reporting.
Compare proposals by deliverables and decision dates
We compare engagement proposals against the acquisition timetable rather than choosing on headline fees alone. A cheaper review can become expensive if it excludes the work needed to resolve a material issue before signing.
We ask for clear scope boundaries, information dependencies and escalation arrangements. The proposal should explain what happens if the target’s records are incomplete or negotiations change the transaction structure.
| Assessment area | Evidence we request |
|---|---|
| Scope | Entities, taxes, review periods, exclusions and reliance limitations |
| Deliverables | Issues report, quantified exposures, structure analysis and implementation actions |
| Accountability | Named engagement lead, reviewers and escalation contacts |
| Timing | Findings aligned with signing, completion and financing deadlines |
| Fees | Included work, assumptions and approval requirements for additional services |
| Coordination | Responsibilities shared with lawyers, lenders and the buyer’s finance team |
We also clarify whether advice will be delivered progressively. A significant finding should not remain buried in a draft report until the day before signing.
Our assessment of a tax company therefore includes how effectively it communicates uncertainty. We prefer a prompt explanation of missing evidence and its consequences to an apparently definitive answer that rests on untested assumptions.
Secure the post-completion handover
Acquisition support should connect the transaction findings with the operating business. We identify who will reconcile opening balances, track unresolved exposures and incorporate new obligations into the reporting calendar.
We also check whether the finance team can separate pre-completion and post-completion transactions where necessary. BAS, payroll, Superannuation and company tax obligations continue while systems, staff and ownership arrangements change.
Our approach to planning company tax filing after a major business change helps connect those transition tasks with the evidence needed for subsequent reporting.
For businesses operating across jurisdictions, we coordinate national tax analysis with relevant state and territory requirements. At Perfect Accounting & Tax Services, our integrated service capabilities across Adelaide, Sydney and Melbourne support clients throughout Australia.
This handover makes accurate bookkeeping and compliance the foundation for strategic advisory. Reliable opening data supports working-capital management, performance reporting and corporate growth decisions after completion.
Frequently asked questions
Does every acquisition require a specialist tax company? We scale the required expertise to the transaction. Multiple entities, property, historical compliance gaps, complex funding or cross-border elements generally require deeper specialist input than a straightforward transaction with reliable records.
Can we rely on the seller’s accountant? We may use information prepared by the seller’s accountant, subject to authority and appropriate checks. We separately assess conflicts, scope and whether independent buyer-side advice is needed. Historical familiarity is useful, but it does not replace independent analysis.
Does a clean ATO account prove there are no tax risks? We treat an ATO account as one source of evidence. It does not establish that every return is correct, every obligation has been identified or no future adjustment will arise.
When should acquisition tax advice begin? We prefer involvement before heads of agreement or other documents constrain the structure. Early analysis gives us more opportunity to assess funding, GST, duty and historical exposures before commercial commitments narrow the available options.
Next steps: define the decisions before appointing advisers
We begin with a transaction summary, proposed structure, available financial information and the expected signing timetable. From there, we can identify the tax questions requiring investigation and clarify where additional specialist support is needed.
When selecting a tax company, we prioritise evidence, accountable advice and a workable implementation plan over broad promises about savings.
We invite business owners, directors and investors to contact Perfect Accounting & Tax Services for a consultation about acquisition-related tax planning, strategic advisory and our automated accounting workflows.