We approach a tax return with accountant oversight as more than an annual lodgement. For business owners, directors and investors preparing for a sale, acquisition or refinancing, the underlying work can provide evidence about earnings, liabilities and financial controls.
However, a lodged return is not a clean bill of financial health. Its due diligence value depends on the reconciliations, supporting documents and professional judgement behind it. Our objective is to connect those records to commercial decisions, including what a business can distribute, what a buyer may challenge and what funding a transaction will require.
Separate lodgement from independent assurance
We distinguish tax compliance from financial due diligence at the outset. An income tax return reports a taxpayer’s position under Australian tax law. Due diligence investigates the risks and assumptions relevant to a particular decision.
A buyer might question whether reported earnings are sustainable. A lender might examine cash available for repayments. A director might need to understand unpaid obligations before declaring a dividend. Each requires work beyond checking the return’s arithmetic.
ATO processing does not establish that every claim, valuation or transaction has been independently verified. Likewise, preparation by an accountant does not automatically constitute an audit or assurance engagement.
We recommend documenting the engagement’s scope, entities covered, periods reviewed and limitations. This prevents stakeholders from relying on work that was never designed to answer their questions.
A tax return with accountant oversight strengthens the evidence trail
We start with the commercial question, then identify the records needed to answer it. This produces a more useful review than collecting documents without a clear purpose.
For an owner considering a business sale, we would distinguish between evidence supporting taxable income and evidence supporting the proposed valuation. These overlap, but they are not interchangeable.
| Due diligence question | Evidence we would examine | Commercial relevance |
|---|---|---|
| Does reported income reconcile? | Financial statements, tax reconciliation and sales records | Helps explain differences between accounting profit and taxable income |
| Are tax obligations understood? | Lodgements, ATO account transactions and supporting calculations | Helps identify cash commitments and unresolved exposures |
| Are related-party balances recoverable or repayable? | Loan ledgers, agreements and repayment records | May affect settlement adjustments and available cash |
| Is stock properly recorded? | Stocktakes, ownership records and warehouse reports | Supports working capital and inventory assessments |
| Are unusual profits repeatable? | Contracts, invoices and transaction explanations | Helps distinguish recurring earnings from exceptional items |
We also record who supplied each document, the period it covers and whether it agrees with other evidence. Where management explanations remain unsupported, we identify the limitation rather than treating the explanation as a verified fact.
This creates a review trail that another accountant, lender or transaction adviser can follow.
Reconcile the figures before interpreting them
We pair the tax return with accountant-prepared reconciliations so reviewers can understand why different reports show different figures. Accounting profit, taxable income, BAS sales and bank receipts will not necessarily match.
Differences can arise from GST, depreciation, capital transactions, non-deductible expenditure and the timing of income or deductions. A difference is not automatically an error, but it should have a documented explanation.
For example, a payment platform may deposit sales proceeds after deducting fees and refunds. Treating those net deposits as gross revenue can distort turnover and expenses. Depending on the transactions, it may also affect GST reporting.
We would trace the platform’s gross sales, refunds, fees and settlement movements through the ledger rather than assume the bank feed captures the complete transaction.
The same discipline applies to tax liabilities. We reconcile ledger balances against relevant ATO account activity and distinguish amounts already assessed from estimates, pending adjustments and obligations not yet due.
The objective is an explainable financial position, not artificially identical totals. Where records cannot be reconciled, we assess the uncertainty before using those figures in forecasts, lending submissions or a transaction model.
Investigate liabilities that affect the deal
We use a tax return with accountant oversight to identify issues requiring further investigation, rather than assume that lodgement resolves them. Material exposures may sit outside the income tax calculation itself.
Our review priorities depend on the entity and transaction. They can include GST treatment, PAYG withholding, superannuation obligations, FBT and state-based payroll tax. We also examine related-party dealings where they affect tax outcomes or available cash.
For private companies, shareholder loans and payments can require consideration under Division 7A. For trusts, we may need distribution records, beneficiary details and evidence supporting the treatment adopted. Carried-forward tax losses also require scrutiny because their future use can depend on applicable statutory tests.
We do not assume that buying shares and buying business assets create the same exposure. In a share acquisition, historical liabilities generally remain within the acquired company. An asset transaction requires a different assessment of the assets, assumed obligations and transaction taxes.
Where findings affect warranties, indemnities or settlement terms, we coordinate the financial analysis with the transaction lawyer. Our approach to complex Australian tax matters explains why defensible treatment depends on evidence and specialist coordination, not simply a completed return.
Trace overseas inventory and fulfilment
We extend the evidence trail beyond Australian bank accounts when a business holds stock offshore. A tax return with accountant review should be supported by records showing what the business owns, where goods are held and how sales and returns are recorded.
For an Australian e-commerce business using a provider such as Gus Logistics for UK warehousing and order fulfilment, we would request warehouse stock reports, dispatch records, returns data and service invoices. These records help reconcile inventory held by a third party with the Australian entity’s accounts.
We would also investigate goods in transit, damaged stock, sales cut-off and foreign currency movements. Goods physically held in a warehouse are not necessarily all owned by the business, so contractual terms matter alongside stock quantities.
Our focus remains the Australian tax and reporting position. Overseas storage does not, by itself, determine deductibility, GST treatment or the full tax consequences of an international operation. Where foreign obligations arise, we coordinate with appropriately qualified advisers in that jurisdiction.
This operational evidence can be particularly valuable when a buyer is testing working capital or questioning whether reported inventory can actually be sold.
Assemble a proportionate due diligence pack
We support the tax return with accountant-reviewed workpapers that explain material balances and unresolved questions. The pack should be proportionate to the decision, not an indiscriminate upload of every financial document.
For a business transaction, we would usually prioritise:
- Entity and ownership records: Structure charts, relevant agreements and details of related parties.
- Financial and tax reconciliations: Accounts, returns, material adjustments and explanations of differences.
- Obligation records: Relevant BAS, payroll, superannuation and ATO account information.
- Supporting evidence: Contracts, invoices, asset registers and inventory documentation for significant balances.
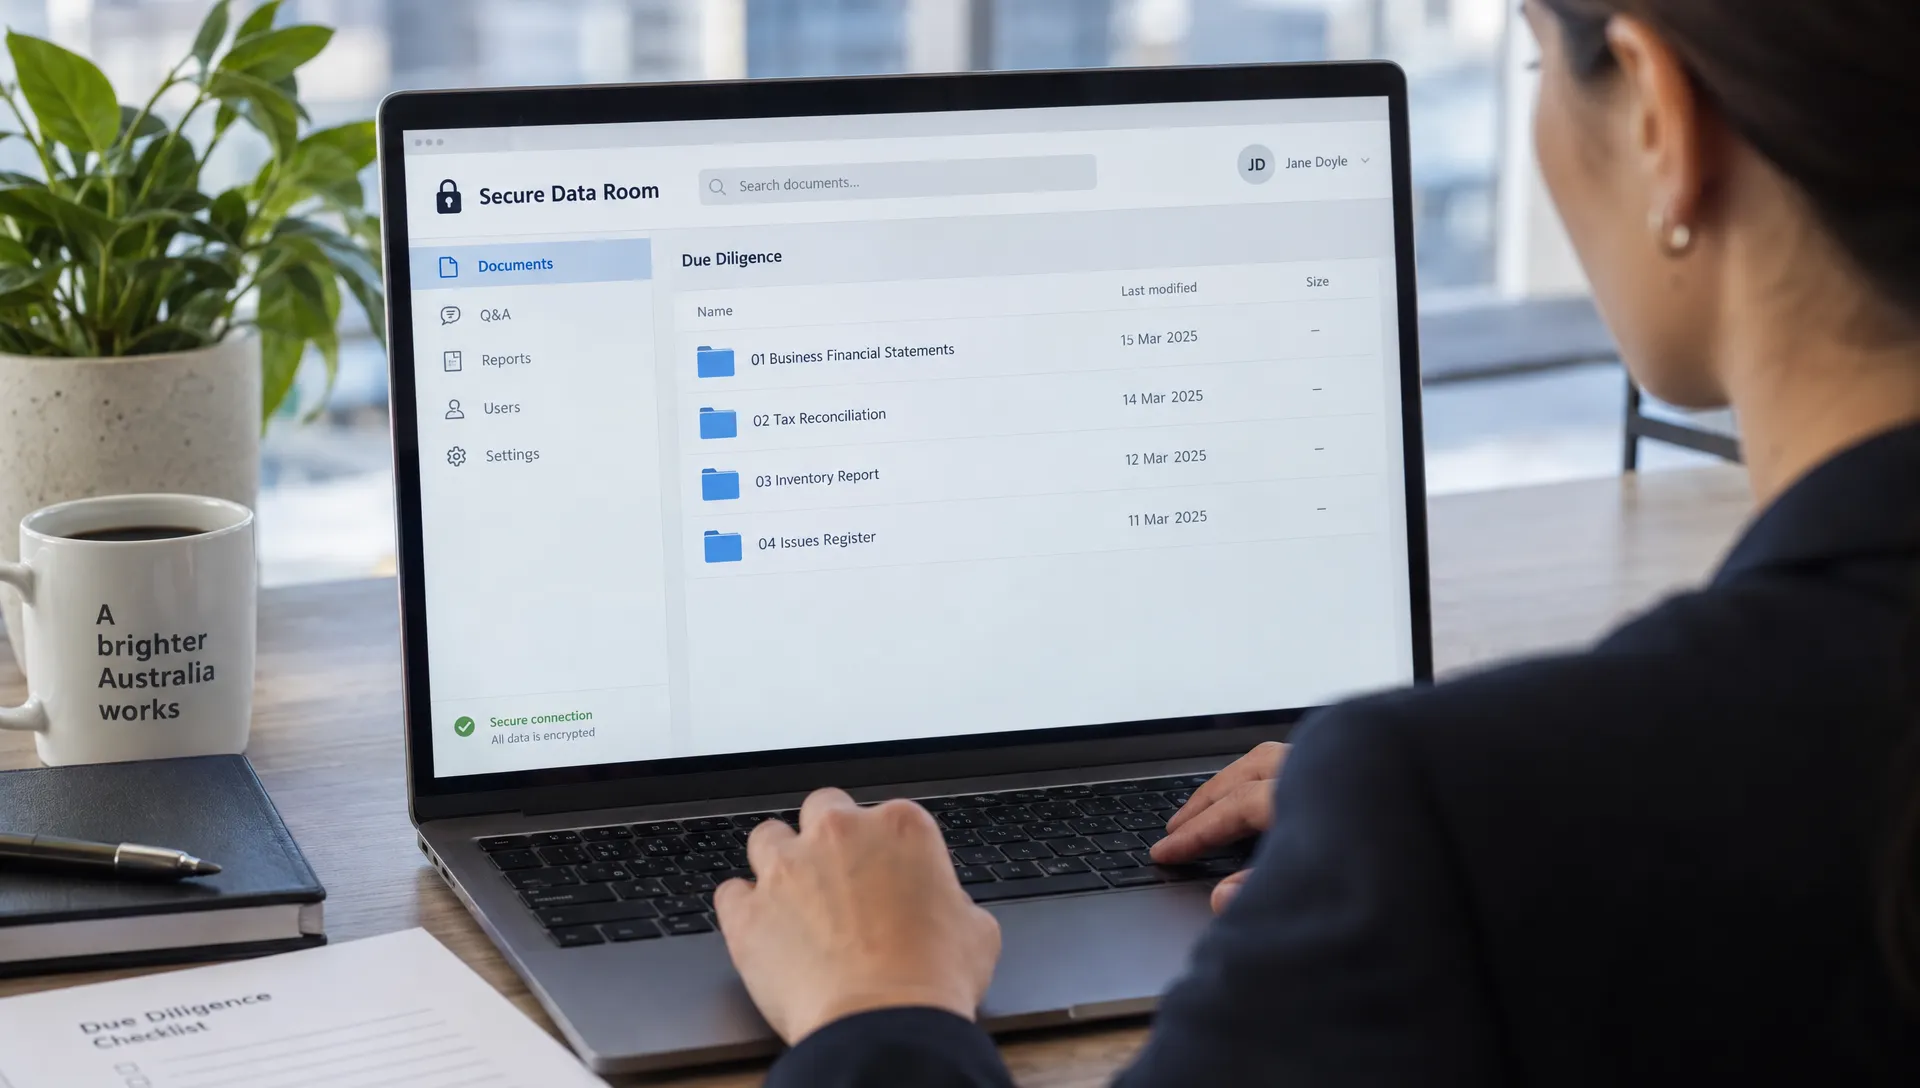
- An issues register: Each finding, its potential financial effect, missing evidence and the person responsible for resolution.
We align retention practices with applicable requirements, including the ATO’s business record-keeping guidance. Some records must be retained longer than a standard business retention period, depending on their purpose and the relevant rules.
We also recommend controlled access to the data room. TFNs, employee information and personal identity documents should not circulate simply because a counterparty has requested financial information. We confirm what is necessary, who is authorised to receive it and how it will be transferred securely.
Use AI to find exceptions, then verify them
We combine professional review with AI-driven automation to improve workflow speed and support greater accuracy. In due diligence, the practical benefit is earlier identification of inconsistencies, not an automatic conclusion that records are correct.
We use the tax return with accountant oversight as part of a broader review framework. Automated matching and exception analysis can help surface duplicate entries, unexplained movements and missing supporting records. The appropriate checks depend on the systems, available data and agreed scope.
Human judgement remains essential. A legitimate transaction can look unusual, while a consistently misclassified transaction may pass a basic matching check. We still need to understand ownership, business purpose and the applicable tax treatment.
Reliable feeds and regular reconciliations also support more timely financial visibility. Real-time dashboards are useful for management, but their figures remain provisional if stock adjustments, accruals or tax provisions have not been completed.
For corporate growth, this distinction matters. We want management to act on current information without confusing a live ledger with verified earnings. Sound digital bookkeeping provides the foundation for strategic advisory, rather than replacing it.
Translate findings into commercial decisions
We connect a tax return with accountant-led analysis to the decisions arising from the review. An identified discrepancy only becomes useful when we understand its potential effect and the action required.
Consider an illustrative acquisition review where unpaid tax obligations of $80,000 have been confirmed but excluded from the buyer’s cash-flow model. We would assess their treatment under the proposed transaction structure and settlement terms. We would not automatically deduct the amount from the purchase price without considering the agreement and any existing adjustments.
Similarly, a one-off gain may be correctly reported for tax purposes but unsuitable as a basis for forecasting recurring earnings. A director’s personal expenditure may require tax correction, a valuation adjustment or both, depending on the facts.
We categorise findings as matters to resolve before commitment, items to reflect in pricing or funding and improvements to implement after completion.
This is where compliance becomes strategic advisory. Through virtual CFO support, we can connect the resulting obligations and controls to cash-flow planning, reporting discipline and sustainable corporate growth.
Frequently asked questions
Can any accountant prepare and lodge a tax return? We recommend checking registration rather than relying on a job title. Providing tax agent services for a fee generally requires Tax Practitioners Board registration unless an exemption applies. We suggest checking the TPB public register and confirming that the engagement covers the required entities and work.
How much does a tax return with accountant support cost in Australia? We scope fees according to complexity, record quality and responsibility. A straightforward individual return is different from a company or trust engagement involving related-party balances and transaction due diligence. We recommend requesting separate pricing for preparation, historical corrections and additional review work so the quote is comparable and its limitations are clear.
How long does the work take? We distinguish preparation time from ATO processing time and any broader due diligence timetable. Missing agreements, unreconciled balances and third-party confirmations can extend the review. We recommend agreeing on document deadlines and key transaction dates before work begins. Agent lodgement arrangements also depend on eligibility and circumstances, so an extension should never be assumed.
Next steps: define the decision before commissioning the work
We recommend starting with the transaction, funding requirement or governance concern that needs an answer. We can then agree on the entities, review periods, material risks and evidence required.
If earlier errors emerge, we assess the appropriate correction process. Our guidance on amending Australian tax returns explains why deadlines and supporting records matter.
At Perfect Accounting & Tax Services, our team draws on 25 years of professional experience and integrated capabilities across Adelaide, Sydney and Melbourne to support clients throughout Australia. We connect tax compliance, automated workflows and strategic financial advice.
Contact our team for a consultation to discuss a tax return with accountant oversight, a transaction-specific review or improvements to your automated accounting workflows.