A tax refund can support a loan application in Australia, but it usually does so indirectly. It can strengthen your cash position, demonstrate recent ATO lodgement compliance and help clear debts before a lender assesses serviceability. It is not, however, a substitute for reliable income, clean financial records or a strong balance sheet.
For business owners, company directors and high-net-worth individuals, the strategic question is not simply whether a refund helps. It is how that refund fits into your broader finance story. A lender will want to understand why the refund arose, whether it is repeatable, whether any ATO debt remains and whether your business or investment structure produces sustainable cash flow.
We see this regularly across Adelaide, Sydney, Melbourne and interstate clients. A well-timed refund can improve an application, but only when the surrounding tax position is accurate, reconciled and defensible.
The short answer: yes, but not as regular income
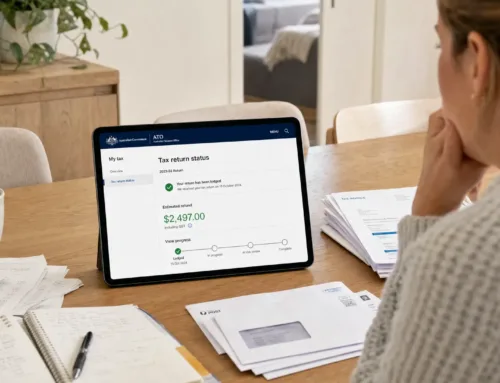
A tax refund is generally a return of tax you have overpaid. For most loan assessments, it is treated as a lump-sum cash inflow rather than recurring income. That distinction matters.
If you receive a $12,000 refund and leave it in your offset account or savings account, a lender may view it as part of your available funds. If you use it to reduce credit card debt or pay down an ATO payment plan, it may improve your liabilities position. If it confirms that your tax returns are up to date, it may reduce compliance risk in the lender's eyes.
What it usually will not do is materially increase your ongoing borrowing capacity unless it reflects a reliable tax outcome supported by income, deductions and business performance. Lenders assess whether you can repay the loan over time. A once-off refund helps liquidity, but income supports serviceability.
The phrase loans on your taxes is often used overseas, but in Australia the practical issue is different. Lenders do not normally lend simply because a refund is expected. They assess tax returns, Notices of Assessment, BAS lodgements, bank statements, business financials and existing commitments.
What lenders actually look for in your tax position
A tax refund sits inside a larger evidence pack. The stronger the evidence, the more useful the refund becomes.
For employees and investors, lenders commonly review recent payslips, PAYG summaries or income statements, tax returns and ATO Notices of Assessment. For sole traders, company directors and trust beneficiaries, the assessment is more layered. Lenders may request two years of tax returns, financial statements, BAS records, profit and loss reports, balance sheets, rental schedules, trust distribution minutes and company tax returns.
A clean refund can help show that your lodgements are complete. A refund combined with unresolved ATO debt, late BAS lodgements or inconsistent financial statements can create questions.
We treat tax compliance as the foundation for strategic finance. When books, BAS, GST, payroll, Superannuation and income tax are reconciled, a loan application is not built on assumptions. It is built on verifiable data.
Ways a tax refund can strengthen a loan application
A refund is most valuable when it is used deliberately before finance is assessed.
| Strategic use of refund | How it may support the application | Key caution |
|---|---|---|
| Increase deposit or equity contribution | Improves available funds and may reduce loan-to-value ratio | Some lenders may require funds to be held for a period |
| Reduce credit card or personal loan balances | Lowers monthly commitments and can improve serviceability | Closing or reducing limits may matter more than just paying the balance |
| Clear ATO or supplier arrears | Reduces perceived repayment risk | Ensure payment is visible in updated statements |
| Build a cash buffer | Demonstrates liquidity after settlement or loan drawdown | A buffer does not replace stable income |
| Fund deductible business expenditure | Can support growth or operational capacity | Spending the refund may reduce cash available for settlement |
For a property investor, applying the refund to an offset account can demonstrate liquidity and reduce interest cost. For a company director, applying it against personal debt may improve the household serviceability calculation. For a business owner seeking equipment finance, retaining the refund in the business or director's cash reserves can support working capital.
Professional practices face similar issues. A clinic, law firm or allied health operator may look stable externally, much like an established local healthcare provider such as Dentalspa Geelong, but lenders will still rely on verified financials rather than reputation alone. The refund is only useful if the numbers behind it are coherent.
When a tax refund may not help much
Some refunds are helpful. Others create follow-up questions.
A large refund caused by excessive PAYG withholding may show conservative cash management, but it does not necessarily show higher income. A refund arising from one-off deductions, major depreciation, a carried-forward loss or a temporary investment structure may not be viewed as repeatable.
Refunds linked to negative gearing can also be misunderstood. A property investor may receive a refund because deductible rental losses reduce taxable income. That can be legitimate, but the lender may still assess the underlying rental cash flow, interest commitments and living expenses. Tax relief does not always offset the effect of a cash loss in a serviceability model.
For company directors, a personal refund does not automatically prove that the company is profitable. Lenders may separate personal tax outcomes from company trading results, especially where income comes through dividends, trust distributions, director fees or related-party loans.
The biggest risk is relying on a refund that the ATO offsets. If you have outstanding income tax, BAS, GST, PAYG withholding, Superannuation guarantee charge or other Commonwealth debts, the ATO may apply part or all of a refund against those liabilities. Before you include an expected refund in a loan strategy, verify the ATO account position.
If prior-year lodgements are overdue, our guidance on back taxes in Australia explains why professional support becomes especially important before approaching lenders.
Business owners and directors need a broader strategy
For business borrowers and directors, the refund is rarely the central issue. The central issue is whether your financial records show sustainable earnings and disciplined governance.
A lender reviewing a business owner may consider taxable income, add-backs, depreciation, interest, director remuneration, retained earnings, distributions and cash flow trends. They may also compare BAS turnover against annual financial statements. If GST reported through BAS does not reconcile with revenue in the accounts, the discrepancy can delay approval or trigger a decline.
We recommend planning early, not after a finance application is already under review. Our article on small business tax return planning explains how reconciled BAS, payroll and deductions can improve the quality of year-end reporting. The same discipline supports finance applications.
Private company directors should also be careful when moving funds between entities and personal accounts. Using company cash to support a personal home loan deposit can raise Division 7A, loan agreement and tax planning issues if not structured correctly. A refund received personally is usually simpler, but where cash is extracted from a company or trust, documentation matters.
Documents that make a refund more useful to lenders
A refund carries more weight when it is supported by complete documentation. We usually prepare clients to provide a concise pack rather than a scattered set of PDFs.
Commonly useful documents include:
- ATO Notice of Assessment for the relevant year
- Lodged individual, company, trust or partnership tax returns
- Current ATO income tax account and activity statement account balances
- BAS lodgement history and GST reconciliations
- Year-to-date management accounts
- Bank statements showing receipt and retention or use of the refund
- Evidence of reduced liabilities, such as updated credit card limits or loan payout letters
- PAYG withholding, payroll, Superannuation and FBT records where relevant
For small business owners, the habit of tracking the right information all year matters more than assembling documents at the last minute. We have outlined the key records in our guide to what business owners should track throughout the year.
A practical point: protect your TFN and sensitive ATO documents. Provide tax records only through secure channels requested by your lender, broker or accountant.
How a refund affects different loan types
Home loans and investment property loans
For home loans, a refund can assist with deposit funds, offset balances, transaction costs or debt reduction. For investors, it can form part of a liquidity buffer, especially where interest rates, land tax, repairs and vacancy risk need to be considered.
Lenders will still focus on income, existing debts, rental income, living expenses and credit history. If the refund arose from negative gearing or one-off deductions, expect the lender to assess the underlying cash flow rather than the refund in isolation.
Business loans and working capital facilities
For business loans, the refund can support working capital, but lenders will usually place greater weight on trading performance, debt service coverage, BAS consistency and management accounts. A company with strong taxable income and clean lodgements may use a refund as supporting evidence of disciplined tax management.
A company with fluctuating income, late BAS or unpaid Superannuation will need a more careful strategy. In those cases, we often prioritise reconciliation, ATO account review and cash flow forecasting before the application is submitted.
Equipment finance and vehicle finance
For tradies, medical specialists, logistics operators, manufacturing businesses and professional firms, refunds are often used toward deposits or to preserve cash after asset acquisition. Where the asset supports revenue generation, the lending story can be stronger.
The tax treatment of the asset, GST credits, depreciation and financing structure should be modelled before signing. A fast approval is not always a good approval if it creates unnecessary tax leakage or pressure on working capital.
SMSF and high-net-worth lending
For SMSF trustees and high-net-worth investors, a tax refund may form part of broader liquidity planning, but the lender will assess the fund or structure on its own terms. Contributions, pensions, fund tax, related-party transactions, investment income and compliance documents all matter.
We take a coordinated view because tax refunds, franking credits, trust distributions and investment debt can interact across entities.
The AI-driven advantage: faster evidence, fewer surprises
Loan applications are increasingly data-led. The quality of your accounting data can influence how quickly you respond to lender queries and how confidently your broker or banker presents the file.
Our AI-driven accounting workflows help streamline reconciliations, detect anomalies and improve real-time visibility across income, expenses, GST, BAS, payroll and cash flow. That does not replace professional judgement. It gives our team cleaner data and more time to focus on strategy, risk and presentation.
For a business owner, this means fewer surprises when a lender requests updated numbers. For a director, it means clearer separation between personal income, company performance and trust distributions. For a high-net-worth investor, it means a more accurate view of tax liabilities, refunds, debt exposure and available liquidity across entities.
This is where compliance becomes strategic advisory. A correctly lodged return may produce the refund. A well-managed accounting system explains the refund and places it within a stronger finance narrative.
Practical steps before relying on a refund for finance
Before you use a refund to support a loan application, we recommend a disciplined review.
First, confirm the refund has been issued or is highly likely to be issued. A draft tax estimate is not the same as an ATO assessment. Second, check whether any ATO or other government debts may absorb the refund. Third, decide whether the refund is best used as deposit funds, debt reduction or retained liquidity.
Then update your financial records. For business owners, this means reconciling bank accounts, BAS, GST, payroll, Superannuation and director loan accounts. For investors, it means ensuring rental schedules, interest statements and ownership details are accurate. For directors using company or trust structures, it means documenting distributions, dividends and related-party loans correctly.
Finally, coordinate timing. Lodging a return immediately before applying for finance can help if the numbers are strong and complete. It can hurt if the return reveals lower taxable income, unresolved debts or unexplained movements.
Frequently Asked Questions
Can a tax refund be used as a home loan deposit in Australia? Yes, if the refund has been received and is visible in your bank account. Some lenders may consider how long the funds have been held and whether they form part of genuine savings.
Will a tax refund increase my borrowing capacity? Usually not by itself. Borrowing capacity is driven mainly by ongoing income, expenses, liabilities and credit policy. A refund can improve your cash position or reduce debts, which may indirectly help.
Can I apply for finance before my refund is paid? You can, but an expected refund is weaker than a received refund. Lenders may request the ATO Notice of Assessment or evidence of funds before approval or settlement.
Does a large refund look good to lenders? It depends on why the refund occurred. A refund from excess PAYG withholding is different from a refund caused by one-off deductions, negative gearing or temporary losses. The lender will assess the underlying income and cash flow.
Can ATO debt affect my loan application? Yes. Outstanding ATO debt, late BAS lodgements or payment arrangements can affect risk assessment, especially for business owners and directors. Clearing or formalising tax debts before applying can improve the file.
Next steps: turn the refund into a stronger finance position
A tax refund can support a loan application when it is part of a planned, documented and compliant financial strategy. Used poorly, it is just a temporary cash inflow. Used well, it can reduce debt, strengthen liquidity and help present a cleaner lending profile.
Our team supports clients across Australia, with integrated service capabilities in Adelaide, Sydney and Melbourne. We combine 25 years of accounting and tax experience with AI-driven automation to improve accuracy, speed and real-time financial visibility.
If you are preparing for a home loan, business loan, equipment finance or investment facility, contact Perfect Accounting & Tax Services for a consultation. We can review your tax position, reconcile your records, assess ATO risks and help build an automated accounting workflow that supports both compliance and corporate growth.