For Australian business owners, tax centers can be the difference between reactive lodgement and a controlled compliance system. We do not view compliance as a once-a-year tax return exercise. We see it as a structured operating discipline that connects bookkeeping, BAS, GST, payroll, superannuation, FBT and director reporting into one reliable governance framework.
That distinction matters. The ATO increasingly expects accurate digital records, timely lodgements and clear substantiation. For company directors, property investors, SMSF trustees and growing SMEs, fragmented records create unnecessary exposure. A well-designed advisory model gives leadership clearer visibility, earlier warning signs and a stronger base for strategic decisions.
How tax centers create stronger compliance control
A modern tax compliance function should centralise knowledge without removing local context. In practical terms, that means your adviser understands national ATO requirements while also supporting operational realities in Adelaide, Sydney, Melbourne and other Australian markets.
Compliance has moved beyond annual lodgements
The traditional model was simple: collect records after year-end, prepare the return and respond to issues if the ATO queried them. That model is no longer enough for directors managing payroll, GST registration, PAYG instalments, contractor payments, related-party loans or investment structures.
Well-run tax centers reduce this risk by building compliance checks into the financial workflow throughout the year. Bank feeds, payroll systems, expense approvals and document capture should feed into a reconciled accounting environment where exceptions are reviewed before lodgement deadlines arrive.
This is where our AI-driven processes add practical value. Automation can flag unusual GST coding, missing supplier invoices, inconsistent payroll categories or late superannuation obligations. The adviser still applies professional judgement, but the workflow becomes faster, more consistent and less dependent on manual review alone.
Centralised expertise, local execution
Australian businesses often operate across state borders. A construction group may have projects in South Australia and Victoria. A digital agency may invoice clients nationally while hiring remote contractors. A property investor may hold assets through companies, trusts or SMSFs across multiple jurisdictions.
In these cases, the compliance issue is rarely one isolated lodgement. It is the interaction between GST, payroll tax exposure, contractor classification, trust distributions, capital allowances, financing arrangements and director obligations. Our team approaches compliance as an integrated framework, not a stack of disconnected forms.
For directors, tax centers are most valuable when they combine national technical oversight with advisers who understand the commercial realities of each location. That is why integrated support across Adelaide, Sydney and Melbourne can be more effective than a purely local or purely remote model.
The ATO obligations a business compliance model must manage
Compliance failures usually arise from weak systems rather than one dramatic mistake. Missing source documents, unclear account coding, late payroll updates and poor director visibility can all compound over time.
The ATO's guidance on record keeping makes clear that businesses must keep records that explain transactions and support tax positions. The records must generally be retained for five years, and they need to be accessible if requested.
A strong compliance framework should monitor the following areas.
| Compliance area | Common risk | Better control mechanism |
|---|---|---|
| BAS and GST | Incorrect GST treatment or missed invoices | Regular reconciliations and review of tax codes |
| PAYG withholding | Payroll settings not updated for employees | Payroll system review and Single Touch Payroll checks |
| Superannuation guarantee | Late or incomplete contributions | Scheduled payment controls and exception reporting |
| FBT | Benefits not identified during the year | Quarterly review of vehicles, entertainment and employee benefits |
| Income tax | Poor substantiation of deductions | Digital document capture and year-round record review |
| Trusts and companies | Unplanned distributions or Division 7A exposure | Pre-year-end tax planning and director reporting |
For a deeper technical discussion of these areas, we have also explained how advisers help businesses manage complex ATO obligations across BAS, GST, payroll, superannuation, FBT and associated structures.
Why compliance must be tied to governance
A company director cannot outsource responsibility for financial governance entirely. External advisers can design systems, prepare lodgements and provide technical advice, but directors still need visibility over the numbers that inform decisions.
This is especially relevant where a business has multiple entities, related-party transactions or asset protection structures. If the accounting data is unreliable, the board or owner may make decisions based on distorted margins, tax liabilities or cash flow projections.
The strongest tax centers operate as governance partners. They help convert accounting records into management information that directors can use to assess risk, funding requirements and growth capacity.
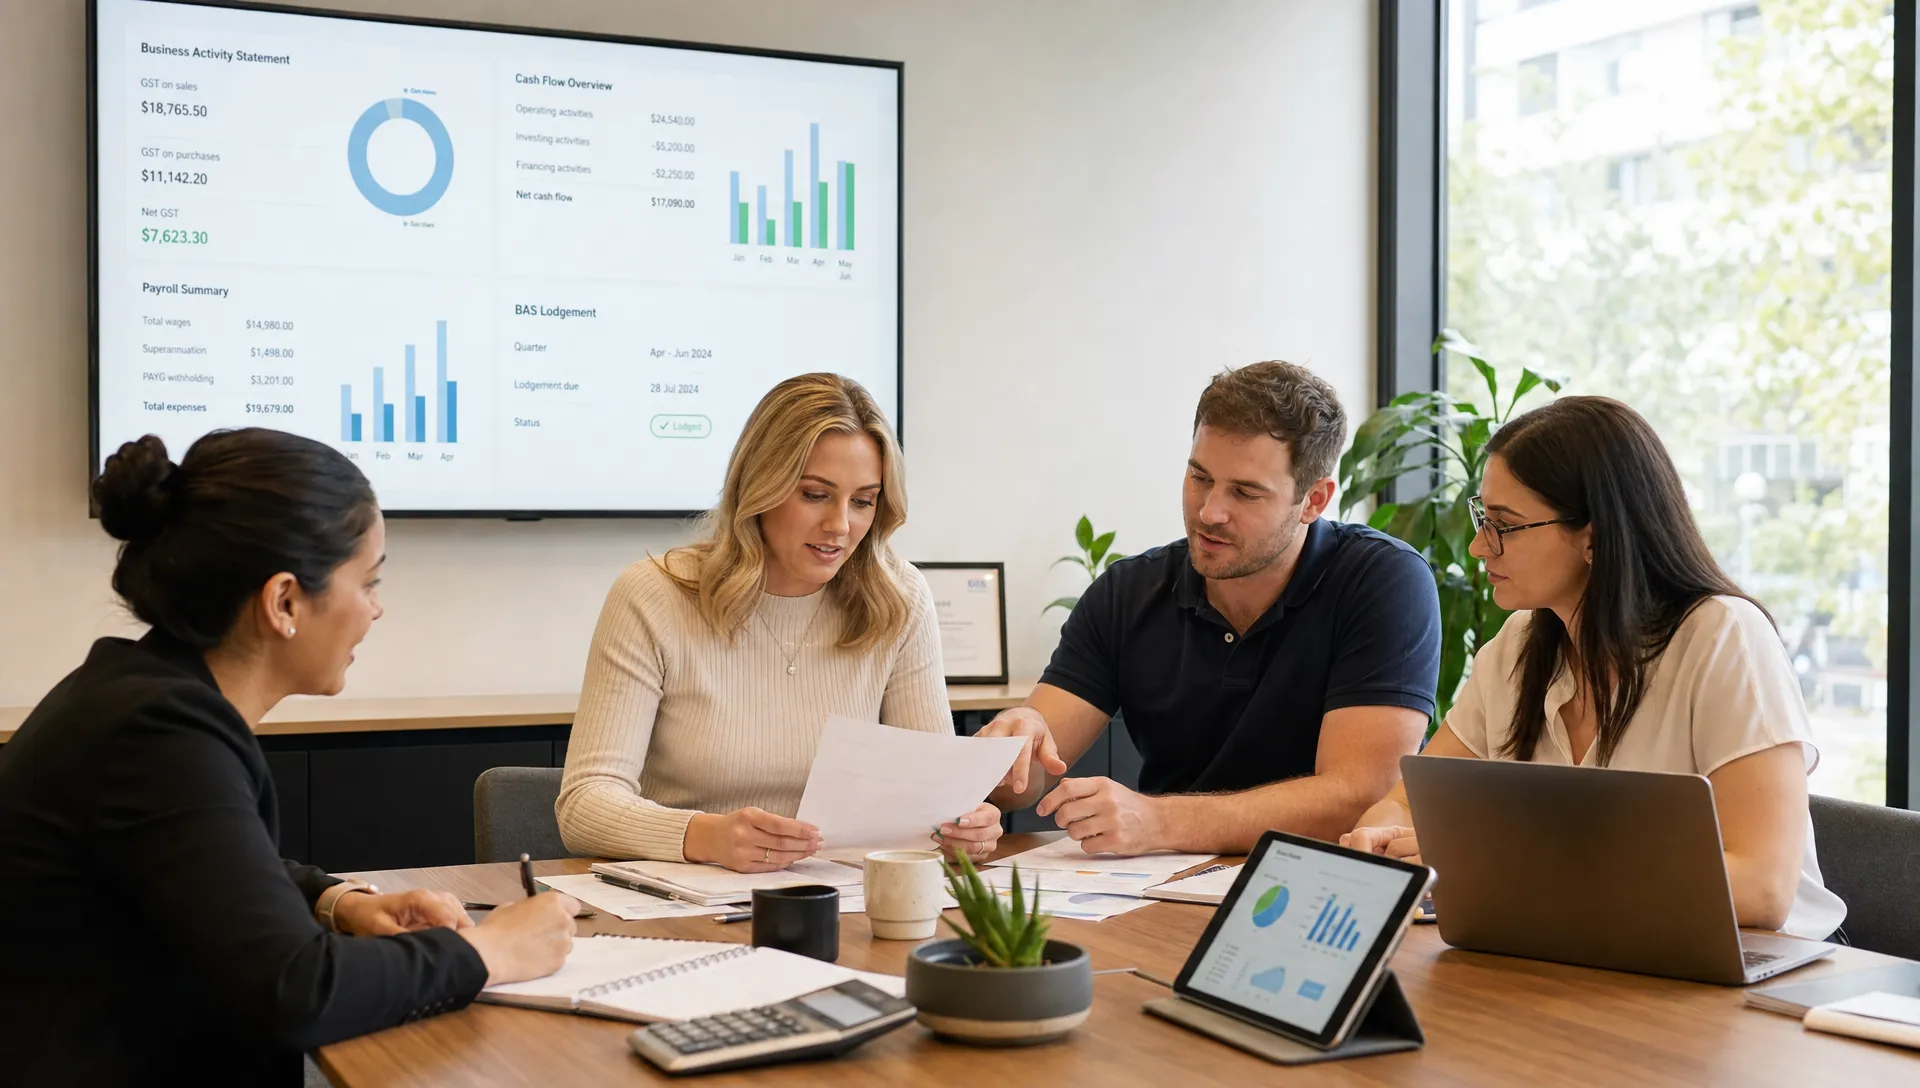
How digital workflows improve compliance accuracy
Digital transformation is not about replacing professional judgement. It is about improving the quality, timing and completeness of the information available to advisers and business owners.
Modern tax centers use automation to standardise recurring tasks, reduce manual data handling and identify exceptions earlier. For example, a supplier invoice can be captured digitally, matched to a bank transaction, coded according to agreed rules and reviewed if it falls outside normal parameters.
That creates three compliance advantages. First, errors are identified closer to the transaction date. Second, business owners are less reliant on memory at year-end. Third, advisers can spend more time on interpretation, planning and risk management.
Real-time visibility supports better decisions
When records are current, compliance becomes a strategic asset. A business can estimate GST payable before the BAS deadline, plan for PAYG instalments, review wage costs and model the tax impact of equipment purchases or financing decisions.
This is where the line between compliance and advisory disappears. Good bookkeeping is not simply data entry. It is the foundation for cash flow planning, tax structuring and corporate growth.
We often see businesses improve their decision-making once they stop treating compliance as an administrative burden. Accurate financial data gives directors the confidence to invest, hire, restructure or delay expenditure when the numbers support that approach.
If cash flow is a recurring challenge, our article on tax-efficient accounting that improves cash flow explains how BAS, GST, PAYG, payroll and planning can be aligned more strategically.
What business owners should expect from a strong tax centre model
The right model should not be judged only by whether a return is lodged. Lodgement is the minimum requirement. The real value sits in the controls, visibility and advice surrounding that lodgement.
For sophisticated business owners and high-net-worth individuals, the engagement should include structured review points during the year. These reviews may cover taxable income projections, director loan accounts, trust distribution planning, asset purchases, depreciation treatment, FBT exposure and superannuation contribution timing.
The best tax centers also maintain disciplined communication around deadlines. BAS, income tax, superannuation and payroll obligations should not surprise management. A director should know what is due, what information is missing and what decisions need to be made before the deadline arrives.
Registration, professional standards and secure systems
In Australia, tax agent services must be provided by a registered tax agent or appropriately supervised team. Business owners can check registrations through the Tax Practitioners Board register. This is a practical governance step, particularly where the adviser is handling complex structures or sensitive financial data.
Security also matters. Modern compliance workflows involve payroll records, TFNs, bank data, company information and investment records. We prefer systems that support controlled access, digital document trails and clear review history, because compliance quality depends on both technical accuracy and evidence.
For business owners evaluating advisers, it is worth considering whether the provider can support growth rather than simply process lodgements. We have outlined that broader selection process in our guide on how to choose tax services that support business growth.
Warning signs your compliance system is under strain
Many businesses do not realise their tax function is weak until cash flow tightens or the ATO starts asking questions. In our experience, the warning signs usually appear earlier.
Common indicators include delayed reconciliations, unexplained balance sheet accounts, repeated BAS adjustments, late superannuation payments, inconsistent payroll categories and directors who cannot see upcoming tax liabilities with confidence. For investors and family groups, warning signs may include unclear trust distribution documentation, poor loan account tracking or incomplete records for capital gains tax events.
These issues are manageable if addressed early. Left unresolved, they can affect borrowing capacity, business valuation, ATO audit readiness and the quality of strategic decisions.
Frequently Asked Questions
How do tax centers help with ATO compliance? They bring accounting, tax, payroll and advisory workflows into one coordinated system. This helps ensure BAS, GST, PAYG, superannuation, FBT and income tax obligations are monitored throughout the year rather than rushed at lodgement time.
Are digital accounting workflows enough without an adviser? No. Automation improves speed and consistency, but it does not replace professional judgement. Australian tax law requires interpretation, especially where companies, trusts, SMSFs, property investments or cross-border arrangements are involved.
When should a business review its compliance systems? We recommend a review before growth events, new entity structures, major asset purchases, funding applications, interstate expansion or ATO scrutiny. A review is also valuable when reconciliations are delayed or directors lack clear tax liability forecasts.
Can one adviser support businesses across multiple Australian cities? Yes, provided the adviser has strong national technical capability and secure digital workflows. Our integrated approach supports clients across Australia, with service capability in Adelaide, Sydney and Melbourne.
Next steps: turn compliance into a strategic advantage
Better compliance is not only about avoiding penalties. It gives directors cleaner data, better cash flow visibility and stronger foundations for growth.
At Perfect Accounting & Tax Services, our team combines 25 years of professional experience with AI-driven automation to support Australian businesses, directors and high-net-worth individuals. We help clients manage tax obligations, strengthen reporting workflows and use compliance data as a platform for strategic advisory.
If your current process still depends on delayed records, manual spreadsheets or last-minute lodgements, now is the right time to review it. Contact Perfect Accounting & Tax Services to book a consultation and learn how our automated accounting workflows can support more accurate, timely and strategic compliance across your business.