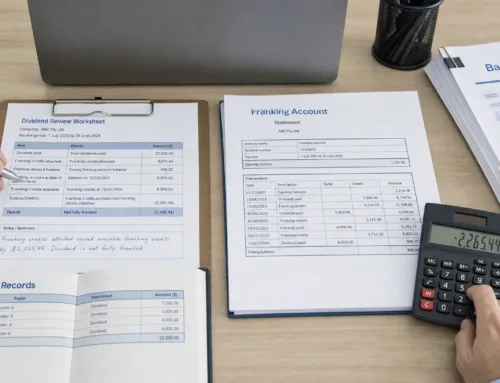
When a company director, investor or lender asks for due diligence, they are really asking whether the numbers can be trusted. For Australian businesses, professional accounting and tax services turn that question into a disciplined review of financial performance, tax risk, compliance exposure and future cash flow. We see due diligence as more than a transaction exercise. Done properly, it becomes a strategic lens for better governance, stronger valuation discussions and more confident corporate growth.
Why professional accounting and tax services matter in due diligence
Due diligence is often associated with acquisitions, capital raising or business sales. In practice, the same discipline applies whenever an owner, board or high-net-worth investor needs to test the quality of financial information before making a significant decision.
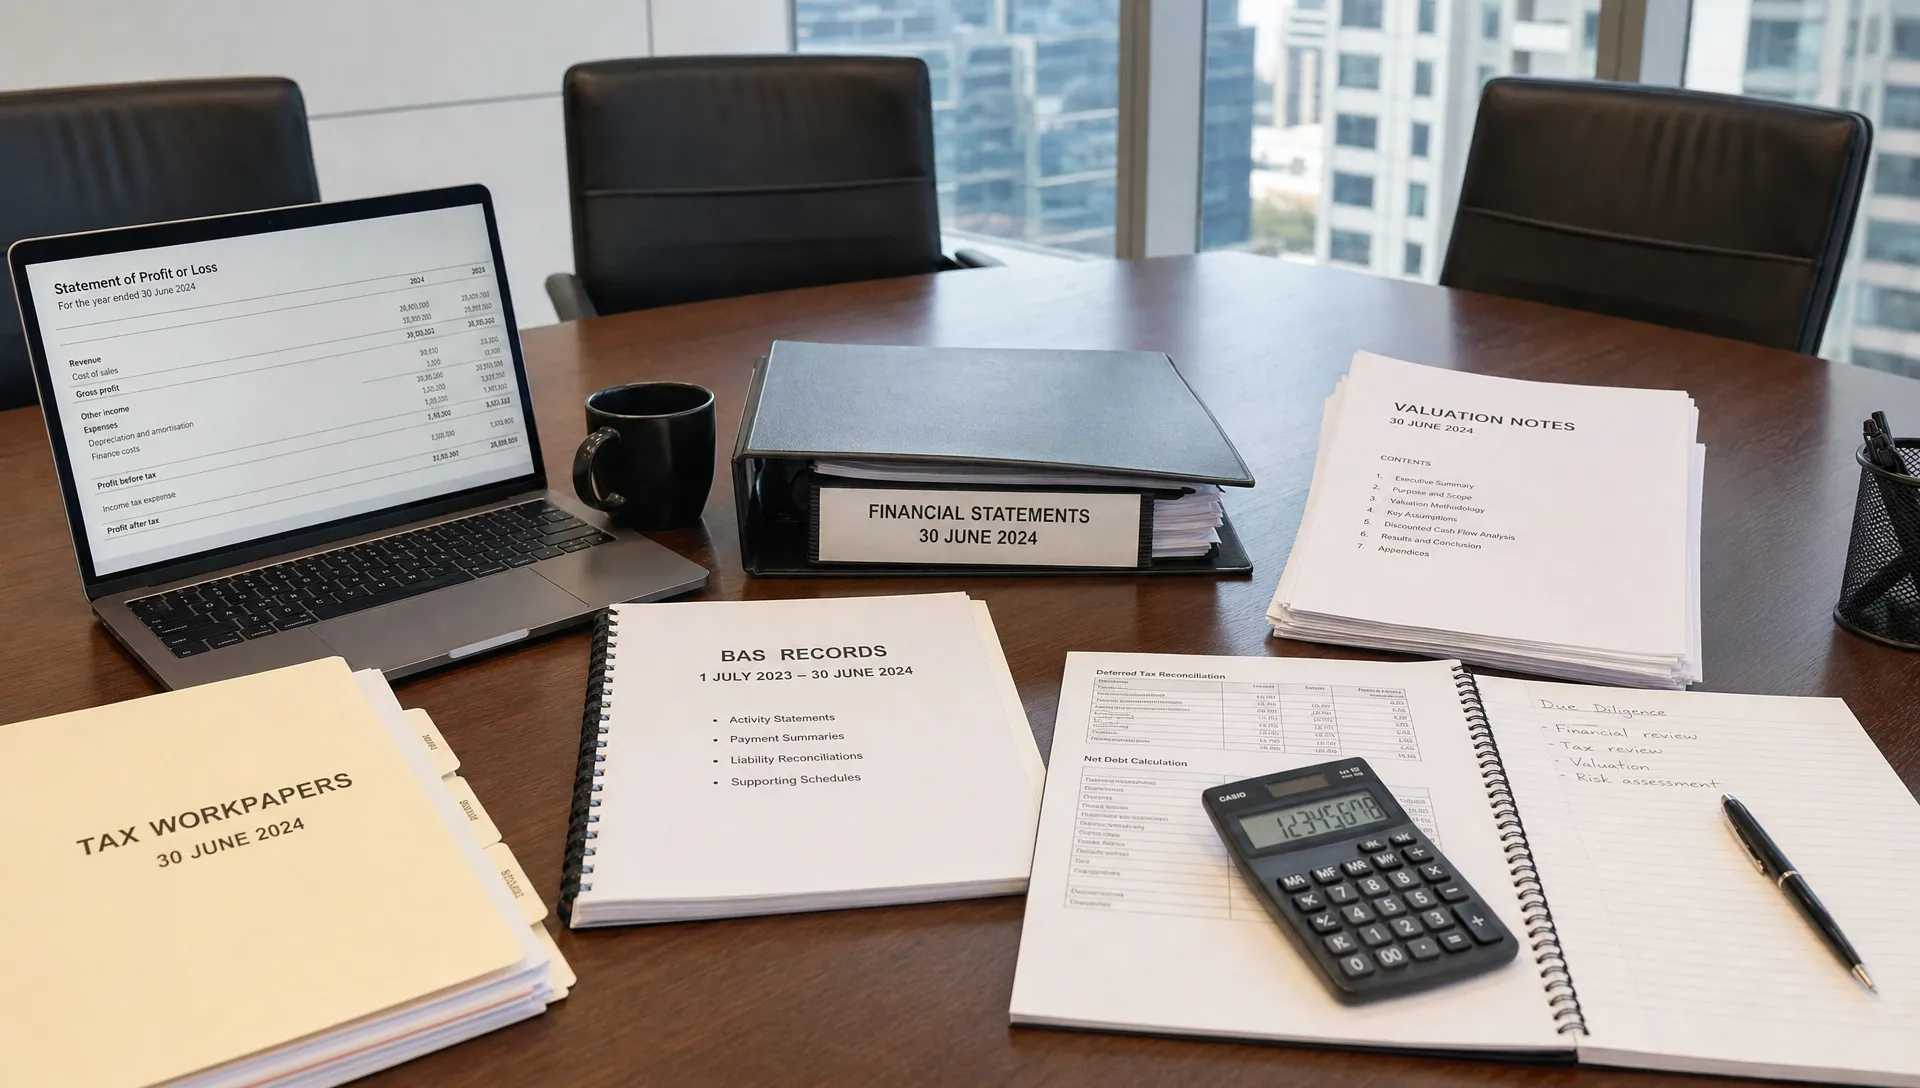
A standard document checklist is not enough. Financial statements, BAS lodgements, payroll records, loan agreements and tax returns must be reconciled against the commercial story the business is presenting. If revenue is growing but working capital is tightening, or profit looks strong but tax liabilities are deferred, decision-makers need to know early.
In our work, professional accounting and tax services strengthen due diligence by connecting compliance detail with commercial interpretation. We are not only asking whether a lodgement was completed. We are asking whether the business has understated risks, overstated earnings, missed ATO obligations or created future cash flow pressure.
Due diligence is a governance exercise, not just a transaction task
Australian directors are expected to understand the financial position of their companies. That expectation becomes sharper during acquisitions, restructures, refinancing, succession planning and disputes between business partners.
Well-structured due diligence gives directors a defensible basis for decisions. It also helps shareholders, lenders and advisers identify whether management reporting aligns with tax outcomes, operational activity and the business model. When the financial records are clean, directors can negotiate from a position of control. When records are fragmented, the buyer or lender usually prices in risk.
This is where our advisory approach matters. We treat bookkeeping, BAS, payroll, tax planning and management reporting as the foundation for future decisions, not as isolated compliance tasks.
The Australian tax risk environment is increasingly data-led
The ATO now receives and analyses significant volumes of business data, including Single Touch Payroll, GST reporting and superannuation information. That means errors in payroll, contractor classification, GST treatment or director obligations can surface quickly during a due diligence review.
For businesses with property, cross-border activity, related-party loans, SMSF interests or group structures, the risk profile becomes even more nuanced. We often see issues that were technically manageable at lodgement time become serious valuation concerns when a lender, acquirer or external investor reviews the business.
Complex matters need diagnostic thinking. Our article on what sets expert tax accountants apart in complex matters explains why deeper analysis is essential when tax, structure and governance overlap.
What a rigorous accounting due diligence review covers
A due diligence review should test both the accuracy of historical records and the sustainability of future performance. We look beyond the profit and loss statement because risk often sits in the balance sheet, tax accounts, payroll files and working capital cycle.
The scope will vary depending on whether the client is buying, selling, raising capital, preparing for finance or reviewing an internal restructure. Still, most Australian due diligence engagements should include the following areas.
| Review area | What we test | Why it matters |
|---|---|---|
| Financial performance | Revenue quality, margins, add-backs, unusual transactions and seasonality | Confirms whether earnings are repeatable |
| Tax compliance | Income tax, GST, BAS, FBT, payroll tax and ATO payment arrangements | Identifies liabilities that may reduce value |
| Payroll and superannuation | STP reporting, Superannuation Guarantee, awards and contractor treatment | Reduces employee and director exposure |
| Balance sheet integrity | Debtors, creditors, stock, provisions, loans and related-party balances | Tests whether assets and liabilities are fairly stated |
| Cash flow and working capital | Debtor days, supplier terms, funding gaps and forecast assumptions | Shows whether growth is financially sustainable |
| Systems and controls | Accounting workflows, approvals, reconciliations and reporting cadence | Reveals whether the business can scale reliably |
A valuable review does not simply collect these documents. It reconciles them, challenges assumptions and converts the findings into actions for the board or owner.
For example, a company may show strong EBITDA but have ageing receivables, GST arrears and inconsistent payroll classifications. In that case, the headline profit number is not the whole story. Professional accounting and tax services help translate those findings into adjusted earnings, risk provisions and a clearer view of enterprise value.
Quality of earnings and cash flow resilience
Quality of earnings is one of the most important parts of financial due diligence. We want to understand which profits are recurring, which are one-off and which depend on aggressive accounting assumptions.
For SMEs and growing corporates, common adjustments include owner salaries, once-off legal fees, abnormal bad debts, director loans, personal expenses in the business and non-recurring government grants. These items can affect valuation, finance capacity and the buyer’s view of management discipline.
Cash flow deserves equal scrutiny. A business can be profitable and still struggle if GST, PAYG withholding, superannuation, stock purchases and debtor collections are not managed properly. That is why management reporting and forecast discipline matter long before a transaction begins.
Tax compliance and hidden liabilities
Tax due diligence must go further than checking whether tax returns were lodged. We review whether positions taken are supportable, whether BAS reporting aligns with accounting records and whether outstanding ATO balances are fully understood.
We also consider FBT exposure, payroll tax thresholds, contractor arrangements, Division 7A issues, trust distributions, GST classification and timing differences. In high-value transactions, these matters can shift the negotiation materially.
When professional accounting and tax services are integrated into the due diligence process early, businesses can correct weak records, quantify tax exposure and avoid surprises during negotiation. This is especially important for groups operating across multiple states, where payroll tax, land tax and state-based reporting can vary.
How AI-driven workflows sharpen due diligence
Modern due diligence depends on timely, accurate data. Traditional manual reviews can still identify issues, but they often take too long and rely heavily on static spreadsheets. Our team uses AI-driven automation to streamline data extraction, reconciliations, anomaly detection and reporting workflows.
This does not replace professional judgement. It strengthens it. Automation can highlight unusual transactions, duplicate payments, margin shifts, late reconciliations, irregular payroll patterns and cash flow movements faster than manual sampling alone.
For clients in Adelaide, Sydney and Melbourne, our integrated workflows also help maintain consistent reporting across entities, locations and teams. That national view is critical when a business is expanding interstate, preparing for acquisition or managing multiple advisory stakeholders.
The strategic benefit is real-time financial visibility. Professional accounting and tax services supported by automation allow directors to move from reactive clean-up to proactive governance, where exceptions are identified early and decisions are based on current information.
Where due diligence often fails without financial control
Due diligence problems rarely appear overnight. They usually build slowly through inconsistent bookkeeping, delayed reconciliations, unclear responsibilities and underdeveloped reporting systems.
A business may have grown quickly but never upgraded its finance function. The owner may still approve invoices manually, payroll may be handled separately from the accounting system and GST coding may depend on inconsistent staff judgement. These gaps can remain hidden until an acquirer, lender or ATO review asks for detailed evidence.
We have written more broadly about how accounting professionals improve financial control, and the same principles apply directly to due diligence. Strong controls reduce rework, improve confidence and support better negotiations.
Common warning signs before a transaction
Some warning signs are immediately visible to a trained adviser. Others require analysis across financial, tax and operational data.
- Management accounts are not reconciled to lodged BAS or income tax returns
- Debtors are ageing but revenue recognition remains aggressive
- Payroll records do not clearly support award, superannuation or contractor treatment
- Director loans or related-party balances are not properly documented
- Inventory, work in progress or project margins are estimated without reliable support
- ATO payment plans exist but are not reflected in cash flow forecasts
These issues do not automatically stop a transaction. They do, however, affect value, timing and trust. If they are addressed before due diligence begins, the business owner has far more control over the narrative.
Data integrity is now a strategic asset
Reliable data improves more than compliance. It gives owners and directors better visibility over pricing, margin, tax timing, funding capacity and growth options.
This is why we encourage clients to treat their accounting system as part of the decision infrastructure of the business. When bank feeds, payroll, BAS reporting, accounts payable, accounts receivable and forecasting are integrated properly, the business becomes easier to manage and easier to defend under review.
For a deeper look at how financial data supports decision-making, our article on how a business services accountant supports better decisions expands on the link between reporting quality and commercial judgement.
Due diligence for acquisitions, funding and growth decisions
Different stakeholders look at due diligence through different lenses. A buyer wants to know whether the purchase price is justified. A lender wants evidence that cash flow can service debt. A seller wants to remove friction before going to market. A board wants to know whether strategic risk is being managed.
The same financial records may need to answer all of those questions. That is why professional accounting and tax services add value across the full business life cycle, not only at year-end.
| Scenario | Due diligence focus | Strategic outcome |
|---|---|---|
| Buying a business | Earnings quality, tax liabilities, working capital and contracts | Better pricing and risk allocation |
| Selling a business | Clean records, adjusted earnings and tax readiness | Stronger buyer confidence |
| Raising finance | Cash flow forecasts, debt capacity and compliance history | More credible lender discussions |
| Expanding interstate | Payroll tax, GST, reporting systems and entity structure | Controlled growth across jurisdictions |
| Succession or exit planning | Valuation drivers, tax planning and governance | Smoother transition and reduced leakage |
For property developers, medical practices, construction firms, e-commerce operators, technology companies and family-owned groups, the specific risks differ. The discipline is consistent: identify the numbers that matter, test whether they are reliable and quantify what they mean for future decisions.
Preparing your business before a buyer, lender or the ATO asks
The best due diligence outcomes occur before an external party starts asking questions. Preparation gives directors time to fix issues, document positions and present financial information professionally.
We usually begin with a readiness review. This includes reconciling core accounts, mapping tax obligations, testing payroll and superannuation records, reviewing GST coding, analysing margins and assessing whether management reporting is fit for purpose.
If a business is planning an acquisition, sale, refinance or restructure within the next 12 to 24 months, waiting until the formal process starts is risky. Professional accounting and tax services can identify issues early, prioritise remediation and convert compliance work into a strategic preparation plan.
A practical preparation program may include:
- Monthly balance sheet reconciliations, not just annual clean-up
- BAS and GST reviews aligned to management accounts
- Payroll, STP and Superannuation Guarantee checks
- Documentation for related-party loans and director transactions
- Cash flow forecasting with tax, debt and working capital assumptions
- Automation of routine accounts payable, receivable and reporting tasks
This approach allows management to shift from defending historical data to explaining the commercial strength of the business.
FAQ
What is accounting and tax due diligence? Accounting and tax due diligence is a structured review of financial records, tax compliance, cash flow, liabilities and controls before a major business decision. It helps directors, buyers, lenders and investors assess whether the reported position is reliable.
When should an Australian business complete due diligence? A business should complete due diligence before buying or selling a company, raising finance, expanding interstate, restructuring, onboarding investors or preparing for an ATO review. We also recommend regular internal readiness reviews for growing businesses.
How do professional accounting and tax services reduce transaction risk? Professional accounting and tax services reduce transaction risk by testing the accuracy of financial records, identifying tax exposures, reviewing BAS and payroll compliance, assessing cash flow and presenting findings in a form that decision-makers can use.
Does automation replace the accountant in due diligence? No. Automation improves speed, consistency and visibility, but professional judgement remains essential. We use AI-driven workflows to identify anomalies and streamline analysis, then our advisers interpret the commercial and tax implications.
Can due diligence help if we are not selling the business? Yes. Due diligence is also valuable for internal governance, succession planning, refinancing, growth strategy and board reporting. It gives owners a clearer view of risk, value and financial resilience.
Next steps: strengthen due diligence before it becomes urgent
Due diligence should not begin when a buyer, lender or regulator requests documents. By then, the business is already under time pressure. The stronger approach is to build clean records, automated workflows and strategic reporting before the review starts.
Our team at Perfect Accounting & Tax Services supports businesses and high-net-worth individuals across Australia, with integrated service capabilities in Adelaide, Sydney and Melbourne. We combine 25 years of professional experience with AI-driven automation to improve accuracy, speed and real-time financial visibility.
If you are preparing for an acquisition, sale, refinance, restructure or governance review, we can help you assess your current position and design a due diligence readiness plan. Contact our team to arrange a consultation and learn how our automated accounting workflows can strengthen compliance, reduce risk and support corporate growth.