When we advise directors on dividends, the corporate tax company rules are never a side issue. They determine how much tax paid by an Australian company can be converted into franking credits, how those credits move through the franking account and whether shareholders can use them efficiently.
For profitable private companies, franking credits are often treated as a simple by-product of company tax. That view is too narrow. The imputation system connects tax governance, cash flow, dividend strategy, shareholder residency, trust distributions, SMSF planning and ATO risk management. A dividend can look attractive commercially but still create poor tax outcomes if the franking position has not been modelled correctly.
Our team works with company directors, family groups, investors and high-net-worth shareholders across Australia, including Adelaide, Sydney and Melbourne. We use automated accounting workflows to track tax paid, BAS movements, PAYG instalments and dividend history in real time, because franking credit decisions should be made from accurate data rather than year-end estimates.
Why corporate tax company rules sit behind every franked dividend
A franking credit represents Australian company tax that has already been paid. When a resident shareholder receives a franked dividend, the shareholder generally includes both the cash dividend and the franking credit in assessable income, then claims a tax offset for the credit.
The aim is to reduce double taxation. Without the imputation system, company profit could be taxed once in the company and again when distributed to shareholders. Franking credits recognise that the company has already paid tax on those profits.
In our advisory work, corporate tax company rules usually affect franking credits in four practical areas: the tax rate applied to profits, the timing of tax payments, the company’s franking account balance and the way dividends are declared.
The company tax rate changes the maximum franking credit
Australian companies do not all pay tax at the same rate. A base rate entity generally pays company tax at 25%, while companies that do not qualify are generally taxed at 30%. The ATO explains the current framework in its company tax rates guidance.
This matters because the maximum franking credit attached to a dividend is linked to the company’s corporate tax rate for imputation purposes. A $100 fully franked dividend from a company using a 25% rate can carry a maximum franking credit of $33.33. At a 30% rate, the maximum credit is $42.86.
| Cash dividend | Relevant franking rate | Maximum franking credit | Grossed-up dividend |
|---|---|---|---|
| $100 | 25% | $33.33 | $133.33 |
| $100 | 30% | $42.86 | $142.86 |
The distinction is material for owners comparing salary, dividends, trust distributions and retained earnings. The wrong assumption about rate can distort personal tax planning, SMSF investment returns and family group cash flow.
How the franking account actually works
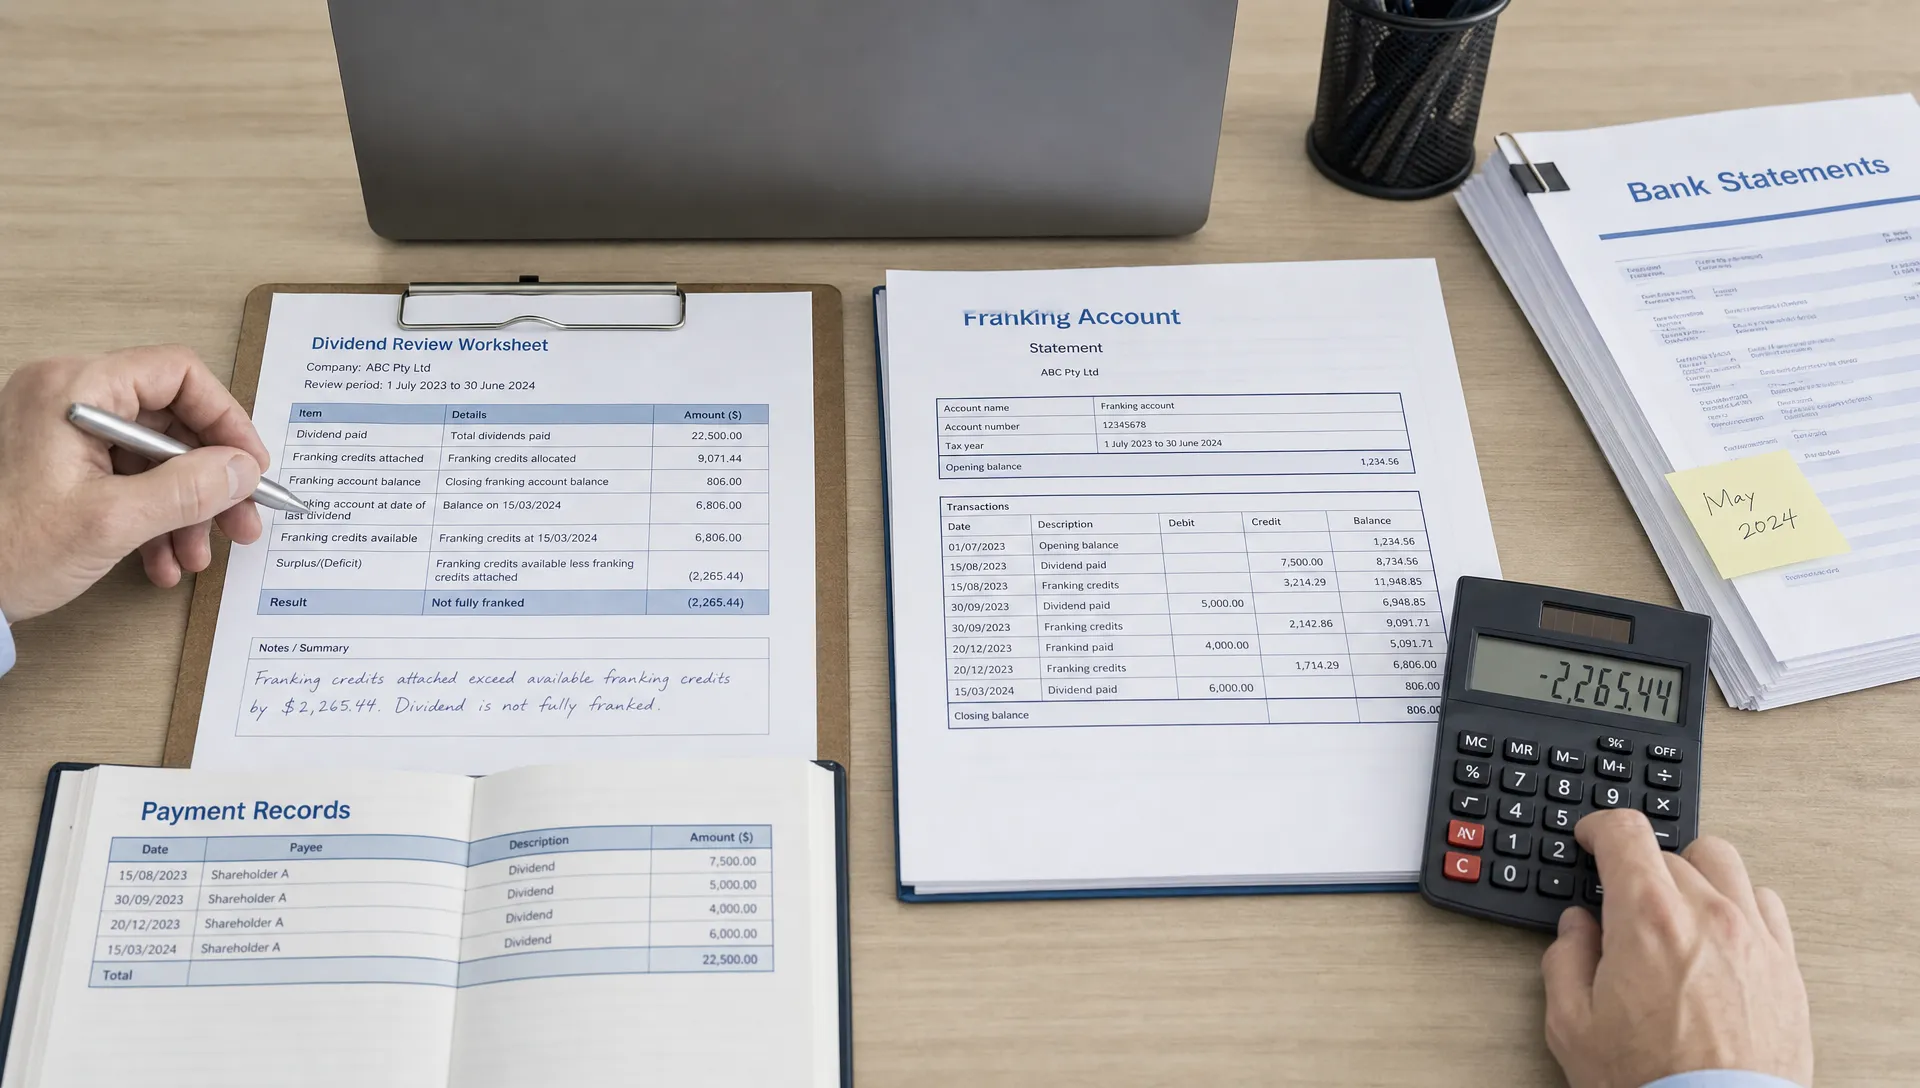
Every Australian company that pays tax and franked dividends should maintain a franking account. It is not a bank account. It is a tax record that tracks franking credits and debits.
A credit usually arises when the company pays income tax or receives a franked distribution from another company. A debit usually arises when the company pays a franked dividend, receives a tax refund or has certain adjustments that reduce its franking balance.
The corporate tax company rules matter because tax payable on the company return does not automatically mean credits are available for a dividend today. Timing is critical. A company may have taxable profit for the year but no franking credit until the related tax has actually been paid.
Why timing can create a franking gap
Consider a company that earns strong profits in June and wants to pay a fully franked dividend before 30 June. If the company has not yet paid enough PAYG instalments or prior tax liabilities, its franking account may not support the dividend.
If a company over-franks a dividend or its franking account goes into deficit, it may be exposed to franking deficit tax. In more serious cases, poor records can lead to ATO queries, amended assessments and director-level governance issues.
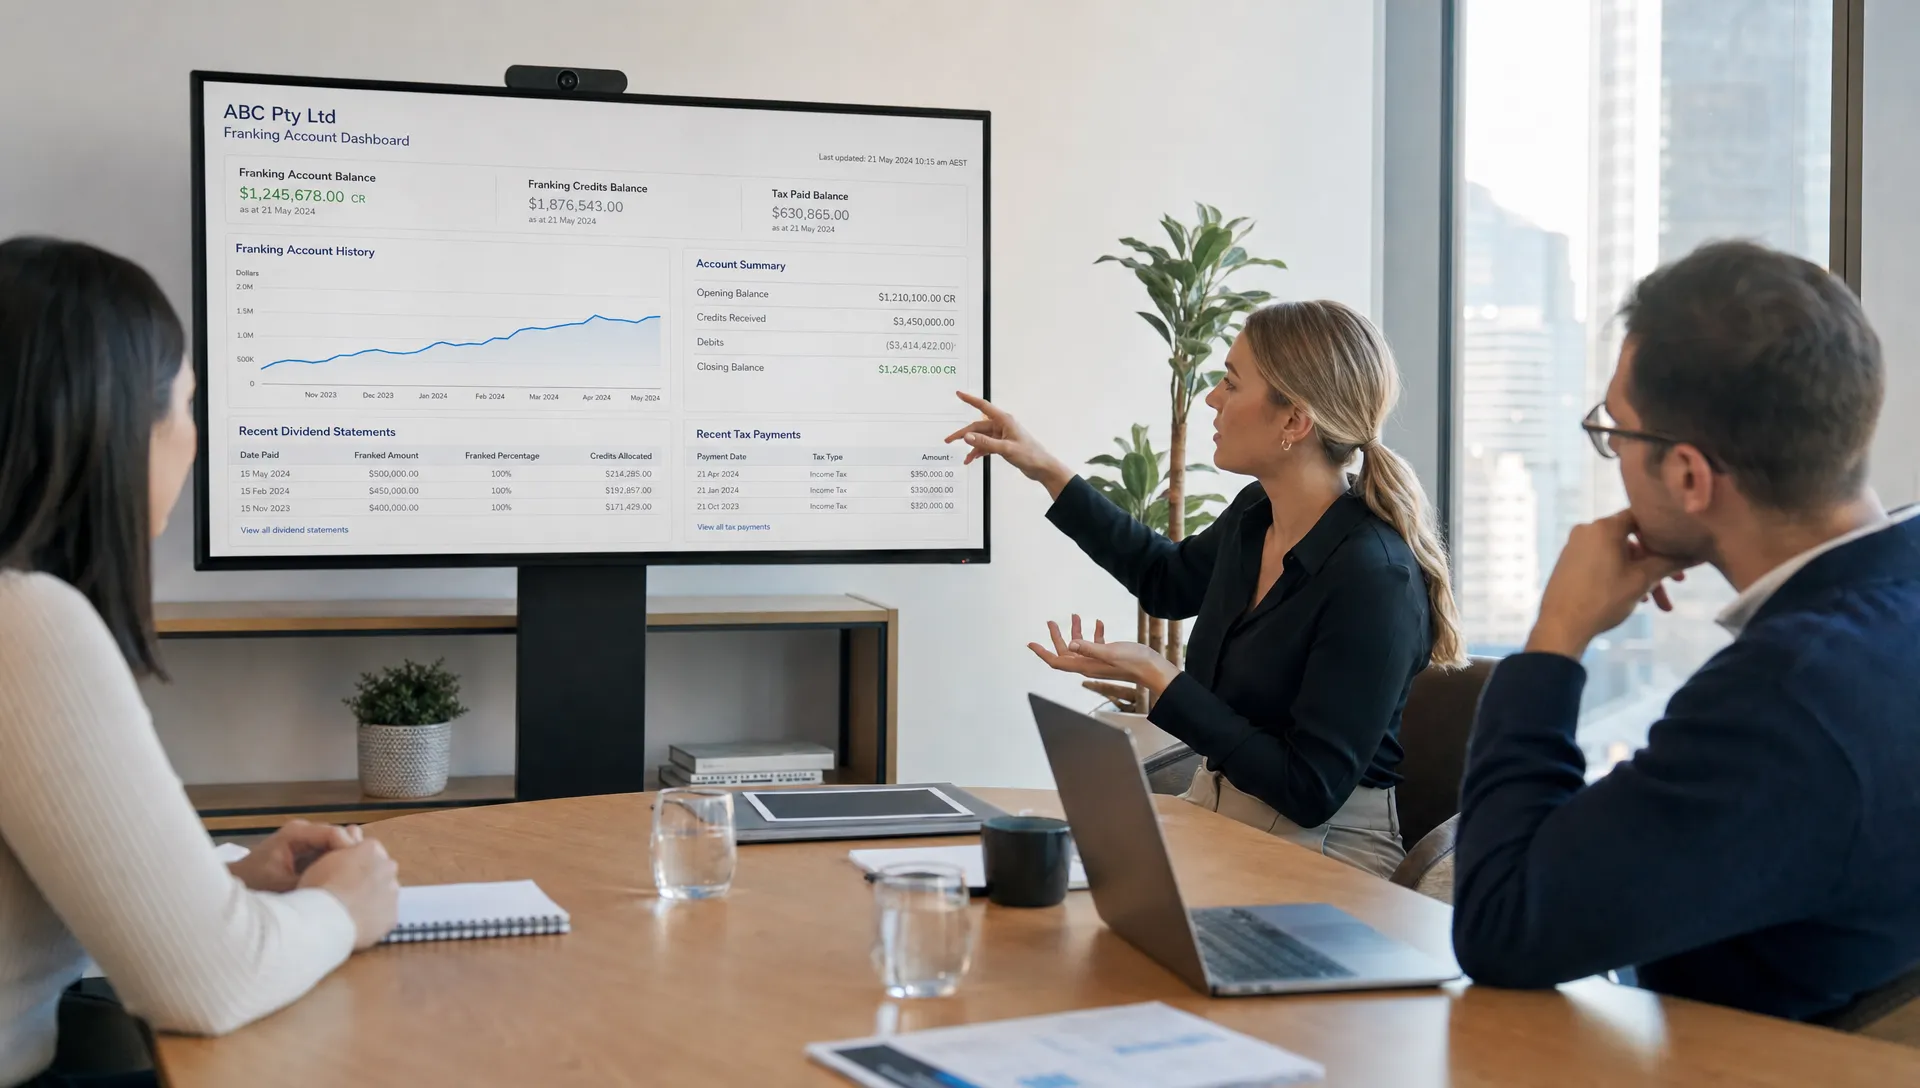
This is why we do not treat franking as a once-a-year calculation. Our AI-driven accounting processes reconcile tax payments, BAS, payroll, superannuation and dividend movements progressively, so directors can see whether proposed distributions are supported by the company’s actual franking capacity.
For a broader director-level planning framework, our guide to company taxes in Australia explains how taxable profit, remuneration, GST, PAYG withholding and Division 7A need to be reviewed together.
Base rate entity status and franking credits
Base rate entity status is one of the most common areas where directors make incorrect assumptions. A company may qualify for the 25% tax rate only if it satisfies the relevant turnover and passive income tests. The passive income test is particularly important for companies with interest, rent, royalties, net capital gains or dividends.
The corporate tax company rules can become more complex where a business has operating income in one entity and investment income in another. Family groups, property investors and corporate beneficiaries often need a deeper review before dividends are declared.
Passive income can affect more than tax payable
The base rate entity passive income test can change whether the lower company tax rate applies. It can also affect the rate used for franking purposes, which may not always align neatly with management expectations.
For example, a trading company that grows its investment portfolio may gradually increase passive income. If the passive income proportion becomes too high, the company may no longer be treated as expected for tax rate purposes. That can affect retained earnings modelling, dividend policy and shareholder after-tax outcomes.
Directors should also be careful when relying on accounting profit. Franking credits arise from tax paid, not merely from profit shown in management reports. Depreciation, instant asset write-offs, timing differences, tax losses and non-deductible expenses can all create a gap between book profit and taxable income.
Dividend strategy is a corporate growth decision
Dividend planning should not sit separately from growth planning. Every dollar distributed is a dollar no longer available for working capital, acquisitions, debt reduction, plant upgrades, technology investment or hiring.
The corporate tax company rules should therefore be considered alongside cash flow forecasts and capital strategy. A fully franked dividend may be tax-efficient for shareholders, but it may still be commercially unwise if it weakens the company’s ability to fund expansion.
Franking is valuable, but cash flow comes first
We often see companies declare dividends based on retained earnings without properly stress-testing the cash impact. This is risky in businesses with seasonal BAS liabilities, delayed customer receipts, inventory build-up or large superannuation obligations.
A better approach is to model dividends after reviewing:
- Current franking account balance and expected tax payments
- BAS, GST and PAYG withholding obligations
- Superannuation guarantee and payroll timing
- Director loan accounts and Division 7A exposure
- Debt covenants, working capital and planned capital expenditure
- Shareholder tax profiles, including trusts, SMSFs and non-residents
This is where modern accounting systems provide strategic value. Clean bookkeeping is not just about compliance. It becomes the data layer for dividend modelling, virtual CFO advice and corporate growth decisions. We explain this broader approach in our article on tax-efficient accounting and cash flow.
Shareholder outcomes depend on who receives the dividend
Franking credits do not affect every shareholder in the same way. A resident individual, resident company, discretionary trust, SMSF, charity and foreign shareholder can each have different tax outcomes.
Australian resident individuals generally include the grossed-up dividend in assessable income and claim the franking tax offset. If the shareholder’s marginal tax rate is lower than the company tax rate represented by the franking credit, the shareholder may receive a refund, subject to the usual rules.
A resident company shareholder may receive a credit in its own franking account, allowing credits to move through a corporate group or investment structure. Trusts require careful distribution resolutions so franking credits flow correctly to eligible beneficiaries.
The corporate tax company rules also matter for foreign shareholders. Fully franked dividends are generally not subject to Australian dividend withholding tax, but foreign shareholders usually cannot use the franking credit as a refundable tax offset. This can change the commercial negotiation between resident and non-resident owners.
Holding period and integrity rules cannot be ignored
Shareholders must satisfy integrity rules to benefit from franking credits. The holding period rule generally requires shares to be held at risk for more than 45 days, excluding the purchase and sale days. Preference shares are generally subject to a longer period.
There are also anti-streaming rules designed to prevent companies directing franking credits to shareholders who can use them most effectively while giving less valuable distributions to others. These rules are especially relevant in family groups, private companies with multiple share classes and restructures before an exit.
For directors, the message is clear. A dividend strategy must consider both the company’s franking capacity and the shareholder’s entitlement to claim the credit.
Division 7A, loans and unfranked tax risk
Private companies often create tax problems when owners treat company funds as personal funds. Payments, loans or forgiven debts to shareholders or their associates may trigger Division 7A if not managed correctly.
Division 7A can deem certain amounts to be dividends. Those deemed dividends are generally unfrankable, which means the shareholder may face tax without the benefit of franking credits. This is one of the most expensive ways to extract value from a company.
The corporate tax company rules should be reviewed before money is advanced to directors, shareholders, related trusts or family members. A compliant loan agreement, minimum yearly repayment and interest calculation may be required, but the better strategy is to design a clear remuneration and dividend policy before cash leaves the company.
ATO review risk increases when records are weak
The ATO is increasingly data-driven. Mismatches between company tax returns, BAS, payroll, shareholder loan accounts and dividend statements can attract attention. Weak franking account records make it harder to support fully franked dividends during a review.
Before EOFY, we typically review retained earnings, franking balances, tax instalments, Division 7A loans, trust distributions, payroll and superannuation. Our article on what a corporate tax accountant reviews before EOFY sets out the broader governance process.
How AI-driven workflows improve franking credit management
Franking credit errors usually come from timing gaps, inconsistent coding or incomplete visibility. These are operational problems before they become tax problems.
Our automated accounting workflows are designed to reduce those gaps. We connect bookkeeping, BAS preparation, payroll, tax planning and management reporting so directors have a more current view of tax paid and distributions declared.
The corporate tax company rules are easier to manage when source data is clean and reconciled. Automation helps identify unusual director loan movements, GST coding errors, unpaid PAYG instalments, late superannuation and dividend entries that do not align with available franking credits.
From compliance record to strategic dashboard
A modern finance function should show more than historical profit. It should help directors answer practical questions before decisions are made.
Can the company fund a fully franked dividend this quarter? Would a smaller dividend preserve working capital for expansion? Should the group retain profit for acquisition funding? Are shareholders better served by salary, bonus, dividend or trust distribution? Has the company’s base rate entity status changed?
These are strategic advisory questions. They require technical tax knowledge and timely financial data. When we support clients across Adelaide, Sydney, Melbourne and nationally, we use automation to improve speed and accuracy, then apply senior advisory judgement to the decision.
Practical next steps for directors
Directors should not wait until the company tax return is due to review franking credits. Dividend decisions are best made before year-end, before funds are transferred and before shareholder expectations are set.
A disciplined process should include reviewing the franking account, confirming tax rate assumptions, forecasting PAYG instalments, checking retained earnings, reconciling shareholder loans and modelling shareholder tax outcomes. The process should also consider whether the company has enough cash after GST, BAS, payroll and superannuation obligations.
The corporate tax company rules can support strong shareholder outcomes when they are managed proactively. When they are reviewed too late, directors may face unfranked distributions, franking deficit tax, Division 7A exposure or avoidable ATO scrutiny.
Frequently Asked Questions
What are franking credits in Australia? Franking credits represent Australian company tax already paid on profits distributed to shareholders. Eligible shareholders may use them as tax offsets when they include the grossed-up dividend in assessable income.
Does a 25% company tax rate mean every dividend is franked at 25%? Not automatically. The relevant franking rate depends on the company’s corporate tax rate for imputation purposes and the applicable rules for that year. Directors should confirm the rate before declaring dividends.
Can a company pay a franked dividend without enough franking credits? It may create a franking account deficit and trigger franking deficit tax. Directors should review the franking account before declaring a dividend.
Are Division 7A deemed dividends franked? Division 7A deemed dividends are generally unfrankable. This can create a poor tax outcome because the shareholder may be taxed without receiving franking credits.
Do foreign shareholders benefit from franking credits? Fully franked dividends are generally exempt from Australian dividend withholding tax, but foreign shareholders usually cannot claim franking credits as refundable tax offsets in Australia.
How we can help
We help directors move from reactive tax compliance to strategic financial control. Our team reviews company tax positions, franking accounts, shareholder loans, BAS, GST, payroll, superannuation and dividend plans as one integrated advisory process.
For growing companies, family groups and high-net-worth shareholders, we can also implement automated accounting workflows that provide clearer visibility over tax paid, franking capacity and cash flow. This gives directors better data before they make dividend, remuneration or reinvestment decisions.
If you are planning dividends, restructuring a group or reviewing shareholder extraction strategies, contact Perfect Accounting & Tax Services for a consultation. We support clients across Australia, with integrated advisory capability in Adelaide, Sydney and Melbourne, and we can show you how automation can make your tax and accounting function more accurate, timely and strategic.