Complex income changes a tax return from a reporting task into a judgement exercise. When clients ask us for “help with my tax return”, we recommend a professional review whenever the outcome depends on how income is classified, which entity earned it or when a transaction became taxable. A completed pre-fill is not evidence that those questions have been resolved.
For business owners, company directors and high-net-worth individuals, the right time to seek assistance is often before a transaction, not just before lodgement. We focus on identifying that point and connecting the return to cash flow, financial health and future growth.
Complexity is about uncertainty, not just income size
We do not assess complexity solely by the value of income or the number of investments. A substantial salary with straightforward deductions can require less judgement than a smaller income spread across consulting work, a family trust and overseas investments.
Our initial review looks for four sources of uncertainty:
- Classification: Whether a receipt is salary, business income, a dividend, a trust distribution or a capital gain.
- Timing: Whether the taxable event occurred in the financial year being reported, regardless of when cash arrived.
- Ownership: Whether income or an expense belongs to an individual, company, trust or another entity.
- Evidence: Whether records support the treatment proposed, rather than merely showing that money changed hands.
Where any of these remains unresolved, we recommend review before the return is finalised. More data will not necessarily solve a legal classification problem.
When does “help with my tax return” become urgent?
Before signing, transferring or distributing
We recommend early advice before selling a significant asset, restructuring ownership, transferring property between related parties or changing how business profits reach an owner.
For many asset sales, the relevant capital gains tax event occurs when the contract is entered into, not at settlement. The ATO’s capital gains tax guidance explains why transaction timing matters. Waiting until sale proceeds arrive can leave the gain assigned to the wrong financial year in a preliminary calculation.
Trust distributions also require advance attention. Depending on the deed and circumstances, trustee decisions may need to be made by 30 June or earlier. We do not treat a later tax return as a substitute for a valid, timely trustee decision.
If “help with my tax return” involves a transaction that has not yet occurred, we can assess the tax consequences while meaningful choices remain available. Once contracts are signed or distribution deadlines have passed, our work may be limited to reporting the outcome correctly and addressing any available remedies.
After discovering an omission or receiving ATO correspondence
An omitted foreign account, an unexplained company payment or an ATO review letter warrants prompt attention. We first establish the facts, preserve supporting records and identify any response deadline.
We avoid making a rushed amendment simply to remove an apparent discrepancy. The same issue may affect several years, related entities or earlier BAS reporting. Where returns are overdue, our guide to getting an accountant involved in back taxes explains why the recovery plan needs to address both outstanding lodgements and liabilities.
Do not confuse a lodgement extension with planning time
For the 2025-26 individual return, the usual self-lodgement deadline of 31 October falls on a Saturday. Under the standard next-business-day rule, that generally moves the deadline to Monday 2 November 2026. We confirm the applicable date against the ATO’s tax return guidance and any specific notices.
Clients seeking access to a registered tax agent’s lodgement program should generally engage the agent before 31 October. A later date is not automatic, particularly where prior returns are outstanding.
A lodgement extension also does not reopen a missed trust resolution deadline or change when an asset disposal occurred. We separate reporting deadlines from decisions that needed to happen earlier.
Income combinations that deserve a targeted review
When assessing a request for “help with my tax return”, we look at how income sources interact rather than reviewing each statement in isolation.
| Income combination | What we investigate | When to involve our team |
|---|---|---|
| Salary plus consulting income | Personal services income rules, business deductions and PAYG instalments | Before adopting a structure or finalising the business results |
| Company ownership plus personal withdrawals | Whether payments are salary, dividends, reimbursements or loans, including potential Division 7A exposure | Before making further withdrawals and before relevant corrective deadlines |
| Trust distributions plus investment income | Beneficiary entitlements, distribution components and supporting trustee decisions | Before year-end decisions and again when final statements arrive |
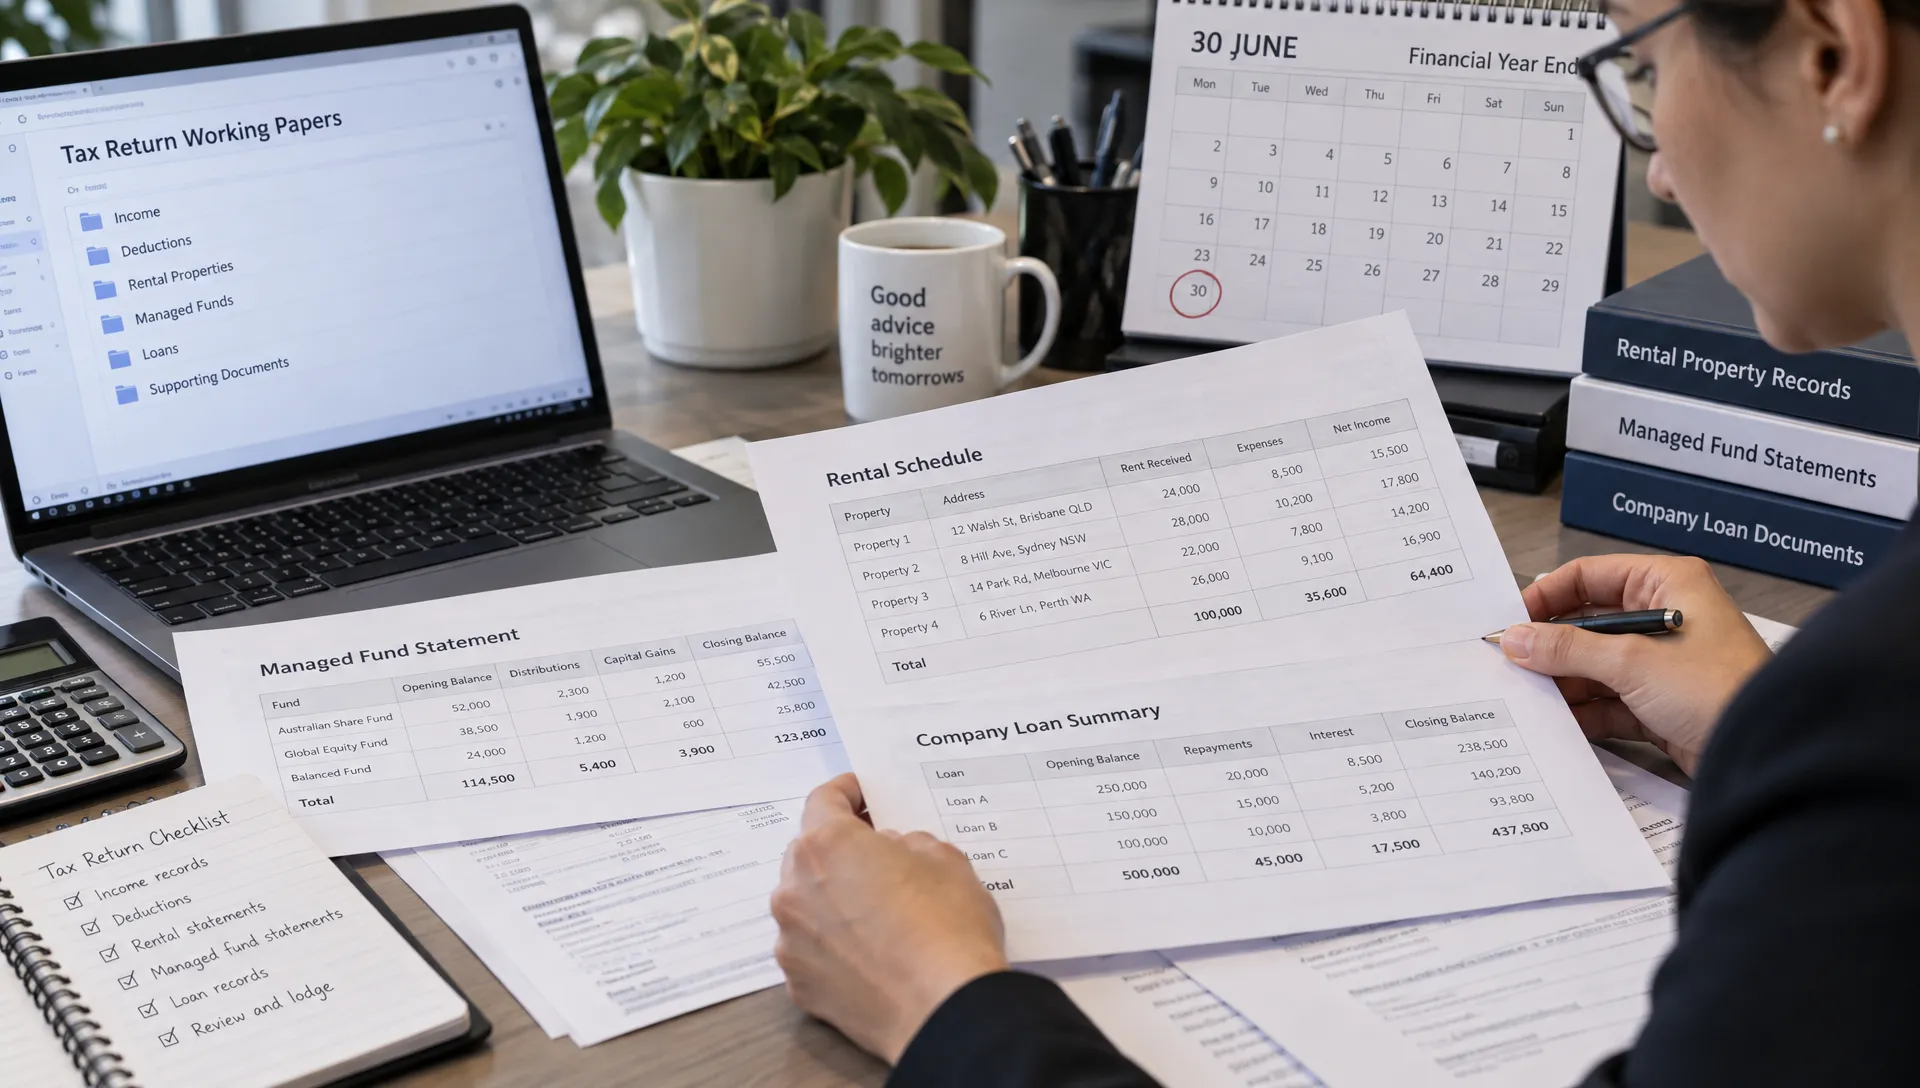
| Rental income plus refinancing | How borrowed funds were used, ownership proportions and repair versus capital expenditure | Before refinancing or undertaking substantial property work |
| Shares, managed funds and employee equity | CGT events, cost-base adjustments and employee share scheme taxing points | Before a major disposal and when final tax statements become available |
| Overseas income plus relocation | Australian tax residency, foreign income reporting and potential foreign income tax offsets | Before moving countries or changing working arrangements |
These are review triggers, not conclusions about the correct treatment. For example, refinancing a rental property does not make all subsequent interest deductible. We trace the use of borrowed funds, including any amount redirected to private purposes.
Similarly, an employee share scheme may create a taxing point before shares are sold. Managed fund statements can include tax components or cost-base adjustments that are not apparent from bank deposits.
For crypto assets, we review disposals and exchanges as well as transfers to a bank account. An exchange between crypto assets can have tax consequences even where no Australian dollars were received.
Review the individual return alongside the business
A director’s personal return cannot always be reviewed reliably without examining company records. We need to understand what each payment represents and whether the company’s reporting supports that treatment.
A transfer labelled “drawings” in bookkeeping software does not establish its tax character. Company money is not automatically the director’s personal money, and a shareholder loan requires more than a convenient year-end journal entry.
Where “help with my tax return” involves business ownership, we reconcile relevant salary, dividends, loan balances and trust distributions across the connected records. Our review of company tax return errors that attract ATO attention explains the related risks of inconsistent reporting.
We also distinguish obligations that sit outside the individual return. BAS, GST, PAYG withholding, Superannuation and FBT may require separate reviews and deadlines. Lodging an individual return does not resolve those obligations.
This connected approach turns compliance into a foundation for strategic advisory. Reliable profit figures and correctly identified owner payments support better decisions about working capital, remuneration and corporate growth.
Use automation to expose exceptions, not approve tax positions
Our AI-driven processes streamline financial workflows by helping organise records, reconcile transactions and identify items that need attention. With connected systems and maintained records, this supports faster processing, greater accuracy and more current financial visibility.
We keep professional judgement separate from automated categorisation. Software may recognise a recurring payment pattern without knowing whether the underlying expense is private, capital or deductible. It also cannot establish tax residency simply from an address field.
The practical recordkeeping risks of DIY filing are also explored in Archie Contable’s articles on professional tax preparation and organised records. We draw on that broader workflow perspective while applying Australian law and ATO requirements, not overseas tax rules.
For clients seeking “help with my tax return”, the value of automation is earlier visibility of missing information and inconsistencies. Our team then tests the proposed treatment against the underlying documents and applicable rules.
We use reconciled accounting information as the starting point for tax provisions and cash-flow planning, not as proof of a final tax liability. That distinction keeps digital efficiency connected to accountable advice.
Prepare a decision-focused handover
We recommend starting with the unresolved decisions, not sending an unstructured collection of receipts. A useful opening summary identifies what changed during the year, which entities were involved and where the tax treatment is uncertain.
For a complex-income review, we usually need a map of income sources and ownership, significant transaction dates, prior returns and details of any ATO correspondence. We then request the evidence relevant to each issue.
Our guide to the documents that matter most for complex returns provides a more detailed preparation framework. The aim is to distinguish documents that establish tax treatment from records that merely confirm payment.
When arranging “help with my tax return”, we recommend identifying any approaching contract, lodgement or response deadline in the initial enquiry. That allows us to prioritise urgent decisions before routine processing.
We also ask clients to highlight gaps openly. A missing acquisition record or unresolved loan balance is easier to address when identified at the start. We use approved, secure document-sharing arrangements for TFNs, identity documents and sensitive financial information rather than ordinary email where possible.
Frequently asked questions
Does ATO pre-fill mean a complex return is ready to lodge? No. We treat pre-fill as a useful input, not a complete assessment. It may not resolve cost bases, business expenses, foreign income, ownership questions or the correct treatment of related-party payments.
Can we obtain advice after the financial year has ended? Yes. We can review the treatment of completed transactions, reconcile records and consider amendments where appropriate. We cannot assume that advice obtained later will recreate a missed decision or change an earlier taxing event.
Should “help with my tax return” include checking the adviser’s registration? Yes. We recommend checking the Tax Practitioners Board public register before engaging someone to provide tax agent services for a fee. We also recommend confirming their experience with the specific income sources and structures involved.
Can automation replace a complex-income review? No. We use automation to improve the information available for review. Questions involving residency, trust entitlements, shareholder loans or asset classification still require professional assessment and supporting evidence.
Next steps: resolve the uncertainty before lodging
We recommend beginning with a focused consultation to identify unresolved tax positions, time-sensitive decisions and the records needed to support the return. From there, we can define an appropriate review scope and connect the findings to ongoing financial planning.
At Perfect Accounting & Tax Services, we combine 25 years of professional experience with AI-driven workflows and integrated support across Adelaide, Sydney and Melbourne. We support clients throughout Australia with tax, accounting and strategic advisory services.
Contact our team for a consultation to discuss your complex income and learn how our automated accounting workflows can support accurate reporting, clearer cash-flow visibility and better-informed business decisions.