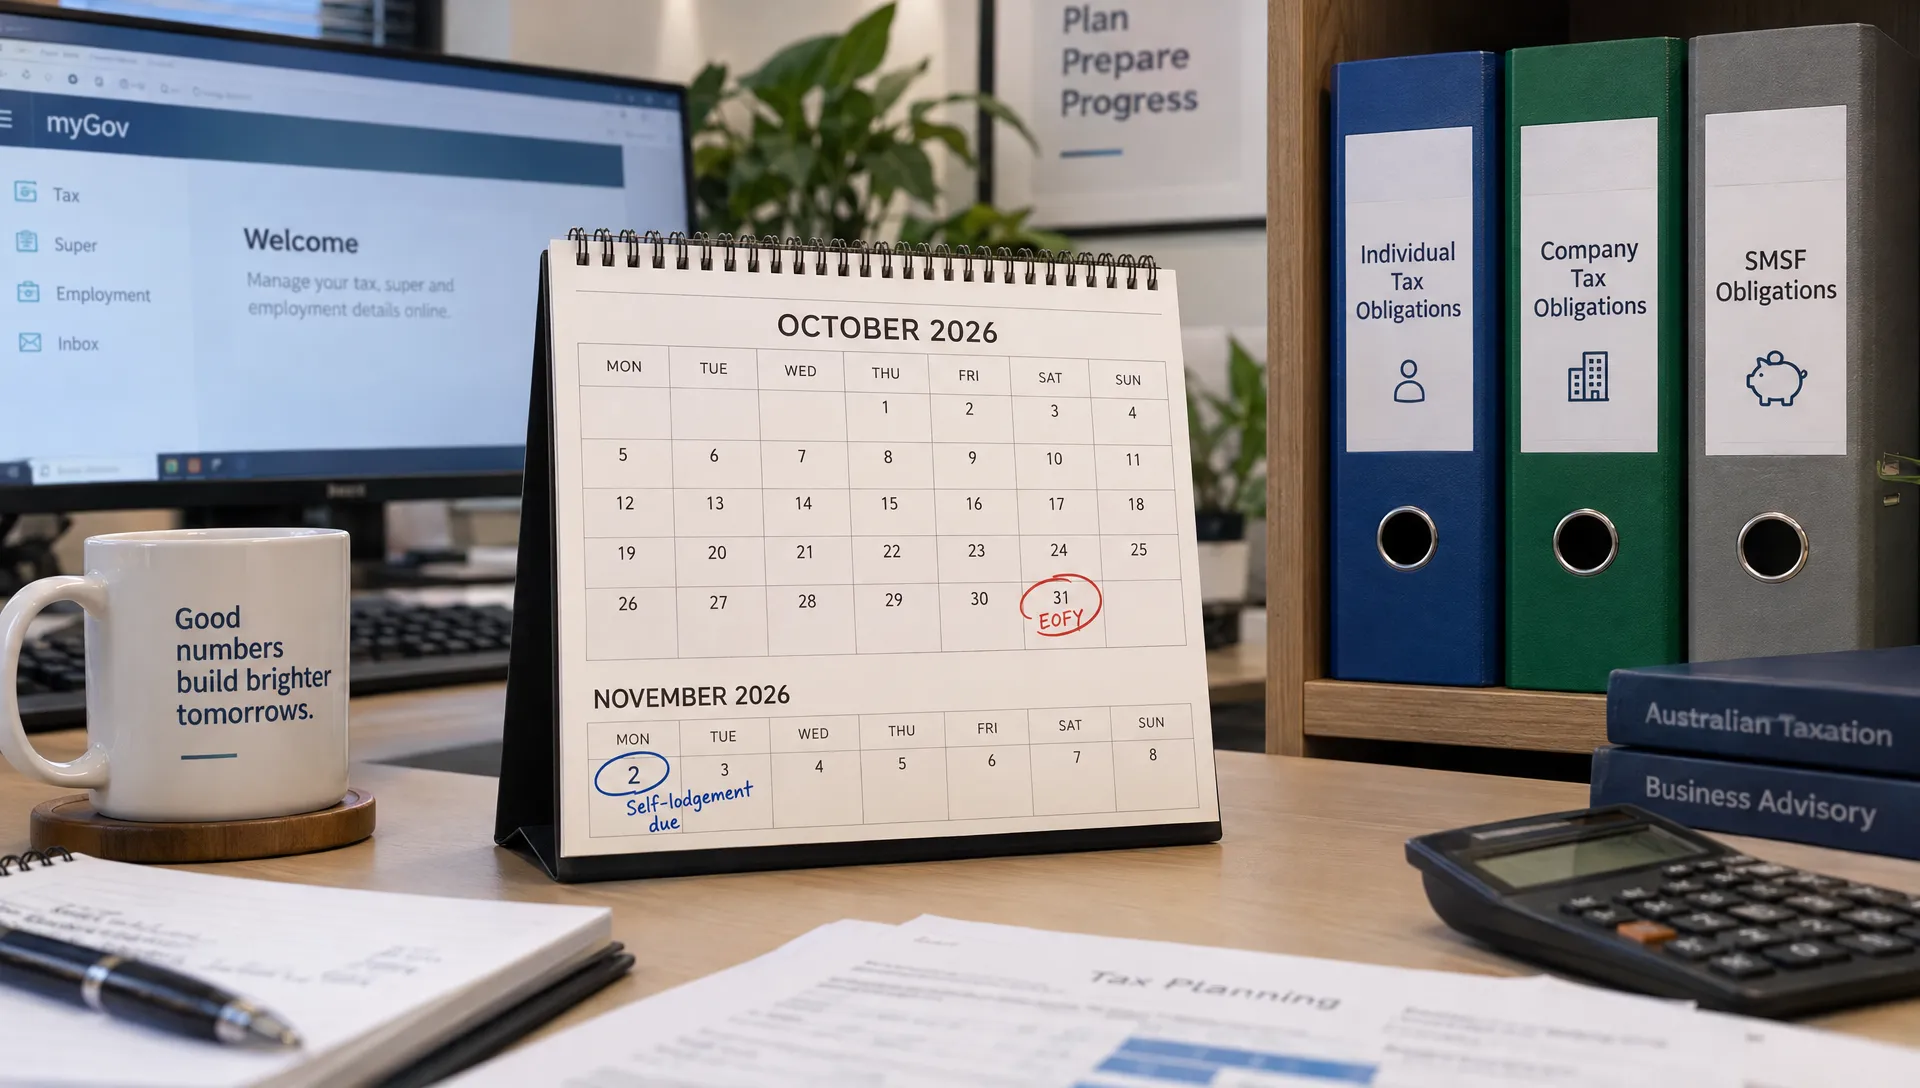
We interpret “tax deadline australia 31 octobe” as a request to confirm the date that actually applies, not simply to set an annual reminder. For individuals lodging their own 2025-26 tax return, the usual deadline is 31 October. In 2026, that date falls on a Saturday, so the ATO’s next-business-day rule moves the self-lodgement deadline to Monday 2 November 2026.
We distinguish that deadline from three other obligations: joining a registered tax agent’s client list, paying an assessed tax debt and lodging returns for separate entities. A director’s individual return, their company’s return and an associated SMSF can have different deadlines.
Our approach combines ATO-confirmed dates, reconciled financial records and professional review. Digital workflows help us identify missing information earlier, while AI-driven automation supports faster processing and more timely financial visibility. We treat deadline management as part of financial governance, rather than an isolated October task.
How we verify “tax deadline australia 31 octobe” for 2026
We start with the income year. The return generally being prepared in October 2026 covers 1 July 2025 to 30 June 2026, not the financial year currently underway.
The ATO’s guidance on lodging a tax return explains the usual 31 October deadline for individuals lodging themselves. Its due-date guidance provides the weekend and public holiday rule.
| Obligation | Our starting position for 2026 | What we confirm |
|---|---|---|
| Individual lodging their own 2025-26 return | Usually 31 October, adjusted to Monday 2 November 2026 | Whether an exceptional arrangement or different obligation applies |
| Individual using a registered tax agent | An eligible agent lodgement date may apply | Client-list status, lodgement history and the assigned date |
| Company, trust or SMSF return | No universal 31 October assumption | The entity’s specific ATO or tax agent program deadline |
| Payment of assessed income tax | Separate from the lodgement deadline | The payment date on the assessment or ATO account |
For the 31 October tax deadline in Australia, our key control is to record both the standard rule and the date applicable to the taxpayer. We retain evidence of any approved deferral rather than relying on an informal understanding.
We establish whose return is due
Individuals, sole traders and investors
We generally include a sole trader’s business income in their individual tax return. Having an ABN does not create a separate company tax return, although GST registration can create additional BAS obligations.
For directors and high-net-worth individuals, we also review investment income, capital gains, trust distributions, foreign income and relevant employee share scheme information. Pre-filled information helps, but we do not treat it as proof that every transaction has been captured correctly.
We assess the obligation to lodge separately from the expected tax payable. A nil tax outcome does not automatically remove the requirement to lodge. Where no return is required, we check whether a non-lodgment advice is appropriate.
Companies, trusts and SMSFs
We do not apply an individual’s calendar to their related entities. Corporate deadlines can depend on factors including lodgement history, prior tax assessments and the applicable lodgement program. SMSF returns also require attention to audit readiness and the fund’s circumstances.
The 31 October tax deadline in Australia is therefore a starting point for an individual’s review, not a universal deadline for a business group.
For a director with several entities, we establish one consolidated register with separate obligations for each taxpayer. This prevents an individual return marked “complete” from obscuring an outstanding company or trust return.
How we build a reliable deadline register
We separate statutory dates from internal milestones
Our preferred register contains the taxpayer, entity type, income year, obligation, confirmed due date and responsible person. We also record the source of the date, outstanding information and approval status.
We distinguish the external deadline from earlier internal milestones. These cover completion of records, technical review, client approval and final lodgement. A return that is prepared but awaiting approval is not treated as lodged.
For businesses operating across Adelaide, Sydney and Melbourne, a consolidated register gives directors visibility without assuming that every entity or state-based obligation follows the same timetable. We keep payroll tax and other state obligations distinct from federal income tax requirements.
We check tax agent eligibility before promising extra time
Using a registered tax agent can provide access to later lodgement dates, but it is not an automatic extension for every taxpayer.
We recommend engaging an agent before 31 October if access to the tax agent lodgement program is needed. An initial enquiry alone should not be treated as confirmation that onboarding, authorisation and client-list requirements have been completed.
For the 31 October tax deadline in Australia, we do not assume that the 2026 weekend adjustment also guarantees extra time to enter the agent program. We confirm that position separately.
Overdue prior-year returns can affect eligibility. Changing agents also does not, by itself, reset a deadline. We establish the applicable date before making commitments about timing.
We verify dates against the ATO record
For individuals, we recommend checking available lodgement information through ATO online services linked to myGov. Businesses can review relevant obligations through Online services for business, while a registered agent can check the information available through their authorised access.
We reconcile that information with correspondence, approved deferrals and any outstanding earlier returns. Where records conflict, we resolve the discrepancy rather than choosing the more convenient date.
We also protect access credentials. TFNs, identity documents and financial records belong in an appropriately secured exchange process. We do not ask clients to share their myGov password.
How we make records ready before the deadline
We reconcile before relying on automation
A reminder cannot correct an unreconciled ledger. We prioritise bank and credit card reconciliations, loan balances, payroll records, GST treatment and material balance sheet accounts before finalising the return.
Our AI-driven processes support efficiency and accuracy by reducing repetitive handling and helping identify items requiring attention. Professional review remains essential for tax treatment, unusual transactions and incomplete evidence. Automation does not establish that an expense is deductible merely because it has been categorised.
For the 31 October tax deadline in Australia, the operational advantage is earlier identification of gaps. Missing loan statements or unresolved director transactions are easier to address before the final approval stage.
We also use the issues covered in our corporate tax review before EOFY to move recurring problems into the annual planning cycle, rather than rediscovering them each October.
We close the approval and lodgement loop
Before submission, we review the tax position with the client and obtain the required approval. After submission, we retain the lodgement acknowledgement and check the resulting assessment or account position.
This closes a common control gap: assuming that a completed draft, an uploaded document or an email to an accountant proves lodgement. We treat acknowledgement as evidence of submission, while recognising that the ATO can still review or amend an assessment.
We track payment separately from lodgement
The date for submitting a return is not necessarily the date for paying the resulting liability. We record each obligation separately and use the assessment or relevant ATO account information to confirm payment timing.
This distinction matters for cash flow. A business owner may have enough information to lodge accurately but insufficient immediately available cash to pay the assessment. Delaying the return does not resolve that funding issue and can create an additional compliance problem.
For the 31 October tax deadline in Australia, we recommend preparing a tax cash-flow forecast alongside the lodgement plan. We consider available cash, expected receipts, existing ATO balances and other upcoming commitments, including BAS and superannuation obligations.
An approved lodgement deferral should not be assumed to defer payment. Similarly, a payment plan does not remove the requirement to lodge outstanding returns. Interest may continue to accrue on unpaid amounts under a payment arrangement, so we assess the full cash-flow implications before recommending a course of action.
What we do if a deadline has already been missed
We first establish what is overdue, whether a return is required and what the ATO has already issued. The priority is a controlled recovery plan, not waiting until every historical issue feels fully resolved.
Our immediate review covers:
- Outstanding obligations: We identify missing returns, activity statements and related entity obligations.
- Available evidence: We determine which records can support accurate preparation and where reconstruction is required.
- ATO communications: We check notices, assessed debts and any existing collection or payment arrangements.
- Recovery sequencing: We prioritise lodgement, assess payment options and consider whether a supported request for relief is appropriate.
Failure-to-lodge penalties may apply, while unpaid tax can attract general interest charge. We check current ATO rules rather than relying on an old penalty amount or interest rate. Relief or remission is not automatic.
Where earlier years remain outstanding, our guide to engaging an accountant for back taxes explains the broader recovery process. We keep that work distinct from simply requesting more time for the current return.
How deadline control supports strategic advisory
We use the 31 October tax deadline in Australia as a checkpoint for financial health. Once records are reconciled, we can assess whether tax provisioning, working capital and reporting processes are supporting the business’s growth plans.
For example, a profitable company with recurring tax payment pressure may need better cash allocation rather than more revenue. An investor facing a significant capital gains assessment may need a forward-looking liquidity plan. These are advisory questions that accurate compliance records help us answer.
Digital transformation strengthens that foundation. Faster processing and more current information allow us to spend less time reconstructing transactions and more time evaluating decisions. The benefit depends on reliable source data, clear responsibilities and accountant oversight.
For leadership teams developing broader commercial judgement, business strategy simulations provide an experiential way to practise marketing, sales and strategic decisions. We distinguish that management learning from live tax advice, where actual records and Australian law determine the outcome.
Our objective is to turn a recurring deadline into a disciplined review of tax exposure, cash availability and capacity for corporate growth.
Frequently asked questions
Can we lodge a tax return in October? Yes. We can prepare and lodge a 2025-26 return in October 2026 when the necessary information is available and checked. We do not recommend waiting until the deadline if reconciliations and approvals can be completed earlier.
Does everyone receive a later deadline through a tax agent? No. We confirm eligibility, client-list requirements, lodgement history and the taxpayer’s assigned date. A later deadline should never be assumed from an initial appointment or enquiry.
Is 31 October 2026 the final day for self-lodgement? For an individual’s standard self-lodgement obligation, the weekend rule moves the date to Monday 2 November 2026. We still check for circumstances that change the applicable obligation.
What is the deadline for the 2026-27 financial year? That income year ends on 30 June 2027. Under the usual rule, an individual self-lodger’s deadline would be 31 October 2027, subject to the next-business-day rule. We confirm the relevant ATO guidance and individual circumstances for that year.
Can we lodge if we cannot pay immediately? We generally recommend addressing lodgement and payment as separate obligations. We can review available payment arrangements, but an arrangement may involve continuing interest and does not excuse outstanding returns.
Next steps: confirm the date and the financial position
We recommend confirming each taxpayer’s deadline now, identifying missing records and setting an approval milestone before the applicable lodgement date. We also recommend checking the expected payment obligation before committing cash elsewhere.
At Perfect Accounting & Tax Services, we bring 25 years of professional experience to integrated accounting, tax and strategic advisory support across Australia, including Adelaide, Sydney and Melbourne.
Contact our team for a consultation to confirm your lodgement position, review tax cash flow or discuss how our automated accounting workflows can improve accuracy, processing speed and financial visibility.