For many Australian businesses, expert accounting is the first place where the need for a Virtual CFO becomes visible. The trigger is rarely one dramatic event. More often, we see a pattern: delayed management reports, uncertain cash flow, reactive tax decisions, uneven margins and directors making growth decisions without current financial intelligence.
A Virtual CFO is not simply a senior bookkeeper or a tax agent with a broader title. The role sits between compliance and strategy. It converts financial data into forward-looking decisions, governance discipline and commercial clarity. For company directors, property groups, professional firms and high-net-worth individuals, that shift can determine whether growth is controlled or merely busy.
What expert accounting reveals before you need a Virtual CFO
Strong accounting records do more than satisfy the ATO. They expose whether your finance function is capable of supporting the next stage of the business. If your accounts only answer what happened last month, they may no longer be sufficient for the decisions you are making this month.
We usually see the need for a Virtual CFO emerge when compliance has become accurate but strategically underused. BAS, GST, payroll, superannuation and income tax records are being prepared, yet the business still lacks timely insight into pricing, hiring, expansion, capital expenditure and funding capacity.
This is where expert accounting becomes diagnostic. It identifies whether the issue is bookkeeping discipline, tax complexity, reporting design, cash flow architecture or a genuine leadership gap in the finance function.
Signal 1: Your numbers explain the past, not the next quarter
If your profit and loss statement is only reviewed after month-end, you are managing through the rear-view mirror. That may be acceptable for a stable sole trader or a small company with predictable costs. It becomes risky when payroll is growing, stock levels fluctuate, debt is being serviced or new contracts require upfront investment.
A Virtual CFO adds forecasting discipline. We look at cash flow cycles, debtor behaviour, GST timing, PAYG instalments, loan commitments and upcoming tax liabilities before directors commit to new spending. The objective is not to produce more reports. It is to improve the timing and quality of decisions.
At this stage, expert accounting should move from historical accuracy to scenario modelling. A director should be able to ask what happens if revenue falls by 10 percent, a major client pays late or a new employee is hired three months earlier than planned.
Signal 2: Cash flow is volatile even when revenue is rising
Revenue growth can conceal financial stress. We often see businesses that appear profitable on paper but are under pressure because GST, wages, superannuation, rent, supplier payments and tax instalments land before client receipts. Growth then becomes a working capital problem.
A Virtual CFO reviews the mechanics behind cash movement. This includes debtor days, stock turnover, project billing milestones, director drawings, dividend planning and the timing of ATO obligations. For property developers, construction firms, medical practices, agencies and e-commerce operators, these timing gaps can be significant.
The issue is not always lack of profit. It is often lack of cash visibility. When expert accounting highlights a disconnect between reported profit and available cash, the business may need a finance leader who can design rolling forecasts, monitor funding headroom and align tax planning with operational commitments.
Signal 3: BAS, GST, payroll and FBT have become governance issues
Compliance becomes strategic when errors can affect cash flow, director risk or business credibility. BAS lodgements, GST treatment, payroll tax exposure, superannuation, TFN declarations and FBT positions all require more than mechanical processing once the business becomes complex.
The ATO expects businesses to keep proper records, generally for five years, and those records need to support the positions taken in lodgements. The ATO guidance on record keeping is clear that records must explain transactions and be accessible when required.
For directors, this means accounting systems must be robust enough to withstand review. Expert accounting helps identify weak controls before they become audit issues, but a Virtual CFO can go further by embedding approval workflows, reporting rhythms and accountability across the business.
Signal 4: You need board-level reporting, not bookkeeping summaries
Standard bookkeeping reports rarely answer the questions directors need answered. A balance sheet may show debtors, creditors and liabilities, but it may not explain gross margin leakage, underperforming divisions, project risk, funding runway or whether the business can support a new location.
A Virtual CFO designs reporting around decisions. We prefer management packs that link compliance data with operational drivers, so directors can see what needs action rather than just what has been recorded.
| Finance area | Basic compliance view | Virtual CFO decision view |
|---|---|---|
| BAS and GST | Lodged accurately and on time | Cash timing, GST exposure and working capital impact |
| Payroll | Wages and superannuation processed | Labour efficiency, hiring affordability and compliance risk |
| Profit and loss | Revenue and expenses recorded | Margin trends, pricing issues and performance by division |
| Balance sheet | Assets and liabilities listed | Debt capacity, solvency, asset quality and funding options |
| Tax planning | Annual estimate prepared | Structuring, timing, distributions and investment decisions |
This is the point where finance becomes governance. Directors no longer need more data. They need disciplined interpretation.
Signal 5: Growth now crosses entities, cities or investor expectations
A single-entity business operating from one location may be manageable with a competent tax accountant and bookkeeper. Complexity rises when you add trusts, companies, SMSFs, related-party loans, commercial property, interstate activity, external investors or multiple management teams.
Our team supports clients across Australia with integrated service capability in Adelaide, Sydney and Melbourne. That national lens matters when payroll obligations, state-based considerations, property activity and operational reporting need to be coordinated without fragmenting the finance function.
When expert accounting shows that structures, reporting deadlines and tax decisions are becoming interdependent, a Virtual CFO can provide the strategic coordination that conventional compliance cycles cannot. This is especially relevant for corporate groups, property investors, family-owned enterprises and scaling technology businesses.
Why the Virtual CFO role changes the operating rhythm
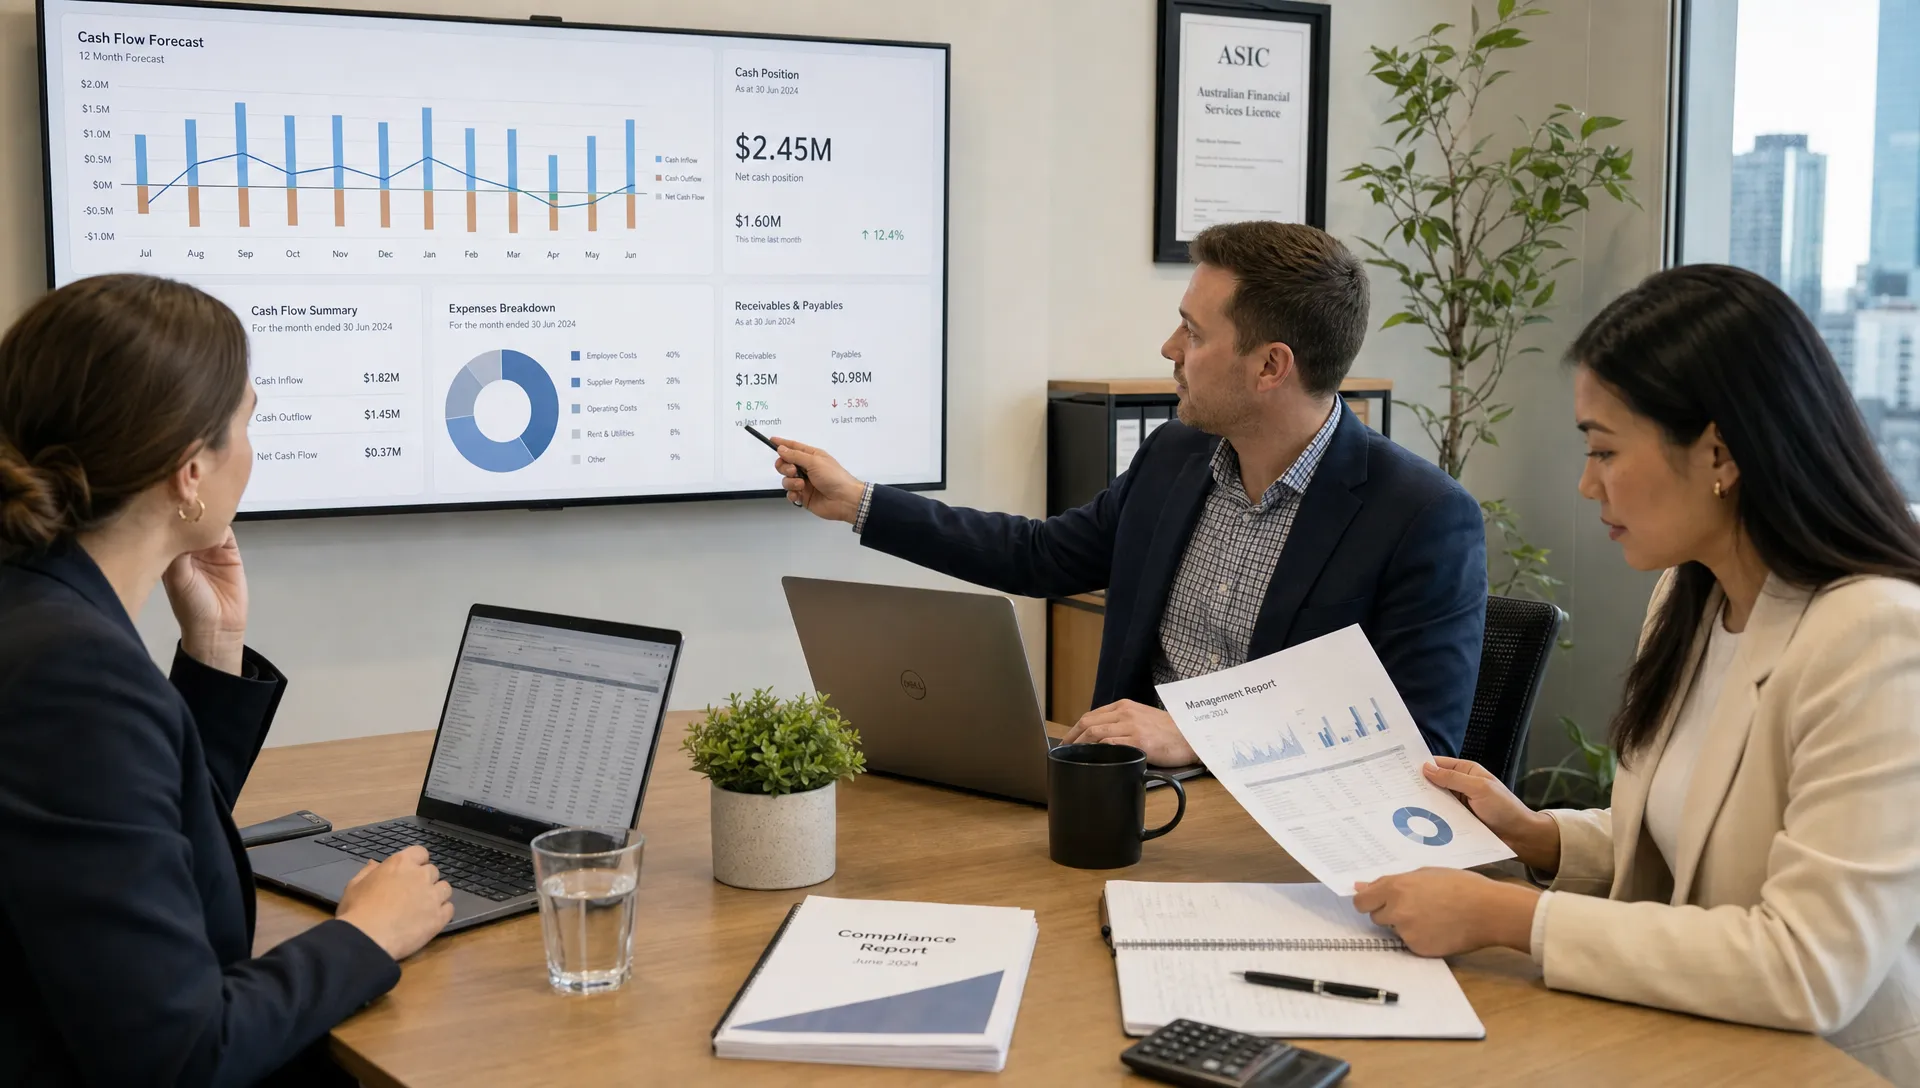
A Virtual CFO is not only engaged for crisis management. In well-run businesses, the role creates a regular financial cadence. We establish structured conversations around performance, tax exposure, cash flow and strategic priorities so decisions are made before pressure builds.
The practical value lies in rhythm. Monthly accounts, quarterly BAS, annual tax planning and ad hoc director meetings often operate separately. A Virtual CFO connects them, turning compliance information into an ongoing management system.
In our view, expert accounting is the foundation, but the Virtual CFO function is the operating layer above it. It asks whether the numbers are reliable, whether they are timely and whether they are influencing the right decisions.
Better forecasting discipline
Forecasting should not be a spreadsheet prepared once for a bank. It should be a living model that reflects debtor timing, seasonality, tax obligations, finance costs and investment plans. This is particularly important for businesses with uneven revenue, large contracts or capital-intensive growth.
Stronger tax integration
Tax planning should not sit outside commercial planning. Decisions about dividends, director remuneration, asset purchases, trust distributions, FBT and GST all affect cash flow. We have written separately about what an expert tax adviser should really deliver when tax advice needs to support broader strategy.
Clearer accountability
A Virtual CFO helps define who owns each finance process. That may include invoice approvals, payroll review, BAS preparation, debtor follow-up, KPI tracking and board reporting. Accountability reduces rework and improves confidence in the numbers.
The technology layer: AI-driven accounting as a control system
Digital transformation changes the value of accounting. Cloud platforms, automation and AI-assisted workflows can reduce manual handling, detect anomalies faster and give directors more current visibility over financial performance. The benefit is not technology for its own sake. The benefit is better control.
We use AI-driven processes to streamline workflows and improve the speed of review, but professional judgement remains essential. Automation can flag unusual transactions, late reconciliations or reporting gaps. It cannot decide the best tax structure, interpret commercial risk or advise directors on growth timing.
This is why expert accounting and automation work best together. Accurate systems create reliable data, and experienced advisers convert that data into decisions. For businesses wanting to strengthen controls before scaling, our guidance on how accounting professionals improve financial control explains the importance of reliable systems, reporting and compliance checks.
When a Virtual CFO may be premature
Not every business needs a Virtual CFO immediately. If your structure is simple, cash flow is predictable, tax obligations are current and decisions are low-risk, strong accounting and proactive tax planning may be enough.
We would usually recommend strengthening the core finance function first if bank reconciliations are late, source documents are incomplete, payroll is inconsistent or BAS preparation still requires significant correction. A Virtual CFO depends on reliable data. Without it, strategic reporting becomes expensive guesswork.
However, waiting too long also has a cost. If directors are making funding, hiring, acquisition, property or expansion decisions without forward-looking financial advice, the business may already be carrying avoidable risk.
How to prepare before engaging a Virtual CFO
Before appointing a Virtual CFO, we recommend reviewing the quality and purpose of your current financial information. This helps identify whether the immediate need is cleanup, compliance strengthening, automation or strategic oversight.
Key preparation steps include:
- Review whether reconciliations, BAS, GST, payroll and superannuation records are current.
- Identify the decisions directors are making without adequate financial reporting.
- Check whether management reports are produced quickly enough to influence action.
- Document upcoming tax, funding, hiring, property or investment decisions.
- Assess whether accounting software and approval workflows support real-time visibility.
- Clarify whether the business needs monthly, quarterly or project-based CFO support.
When expert accounting is already producing clean and timely data, the transition to Virtual CFO support is faster and more valuable. If the records need correction first, that should be addressed before advanced forecasting or board reporting is introduced.
For businesses in a growth phase, our article on how Perfect Accounting and Tax Services supports growth expands on how timely reporting and proactive tax planning can support better commercial decisions.
Frequently Asked Questions
What is the difference between an accountant and a Virtual CFO? An accountant usually focuses on accurate records, tax compliance, BAS, GST and financial reporting. A Virtual CFO uses that information to guide forecasting, funding, pricing, governance, cash flow and growth decisions.
Does a small business need a Virtual CFO? Some small businesses do, especially if they are hiring staff, expanding locations, taking on debt, managing investors or operating through multiple entities. The need depends on complexity, not just turnover.
Can a Virtual CFO help with ATO compliance? Yes, but the role should not be limited to lodgements. A Virtual CFO helps ensure ATO obligations are planned for, funded and reflected in decision-making. This includes BAS, GST, PAYG, superannuation, FBT and income tax planning.
How does automation improve Virtual CFO support? Automation reduces manual processing and improves the timeliness of financial data. With better data flow, advisers can spend more time on analysis, risk management and strategic planning.
When should directors seek Virtual CFO advice? Directors should seek advice before major decisions, such as expanding interstate, acquiring assets, restructuring entities, raising finance, hiring senior staff or preparing for sale.
Next steps: how we can help
We approach Virtual CFO work as a strategic extension of the accounting function. Our first step is to assess the reliability of your records, the quality of your reporting and the decisions your directors need to make over the next 12 to 24 months.
From there, we can help strengthen BAS, GST, payroll, superannuation and tax workflows, introduce AI-driven automation where appropriate and build management reporting that supports corporate growth. Our team works with businesses and high-net-worth clients across Australia, with integrated support in Adelaide, Sydney and Melbourne.
If expert accounting is already showing that your business needs deeper financial leadership, contact Perfect Accounting & Tax Services for a consultation. We can help you determine whether a Virtual CFO model, improved automated accounting workflows or a staged advisory approach is the right next move.